Notes for owners · Sales management
How a founder hands over selling to a sales team
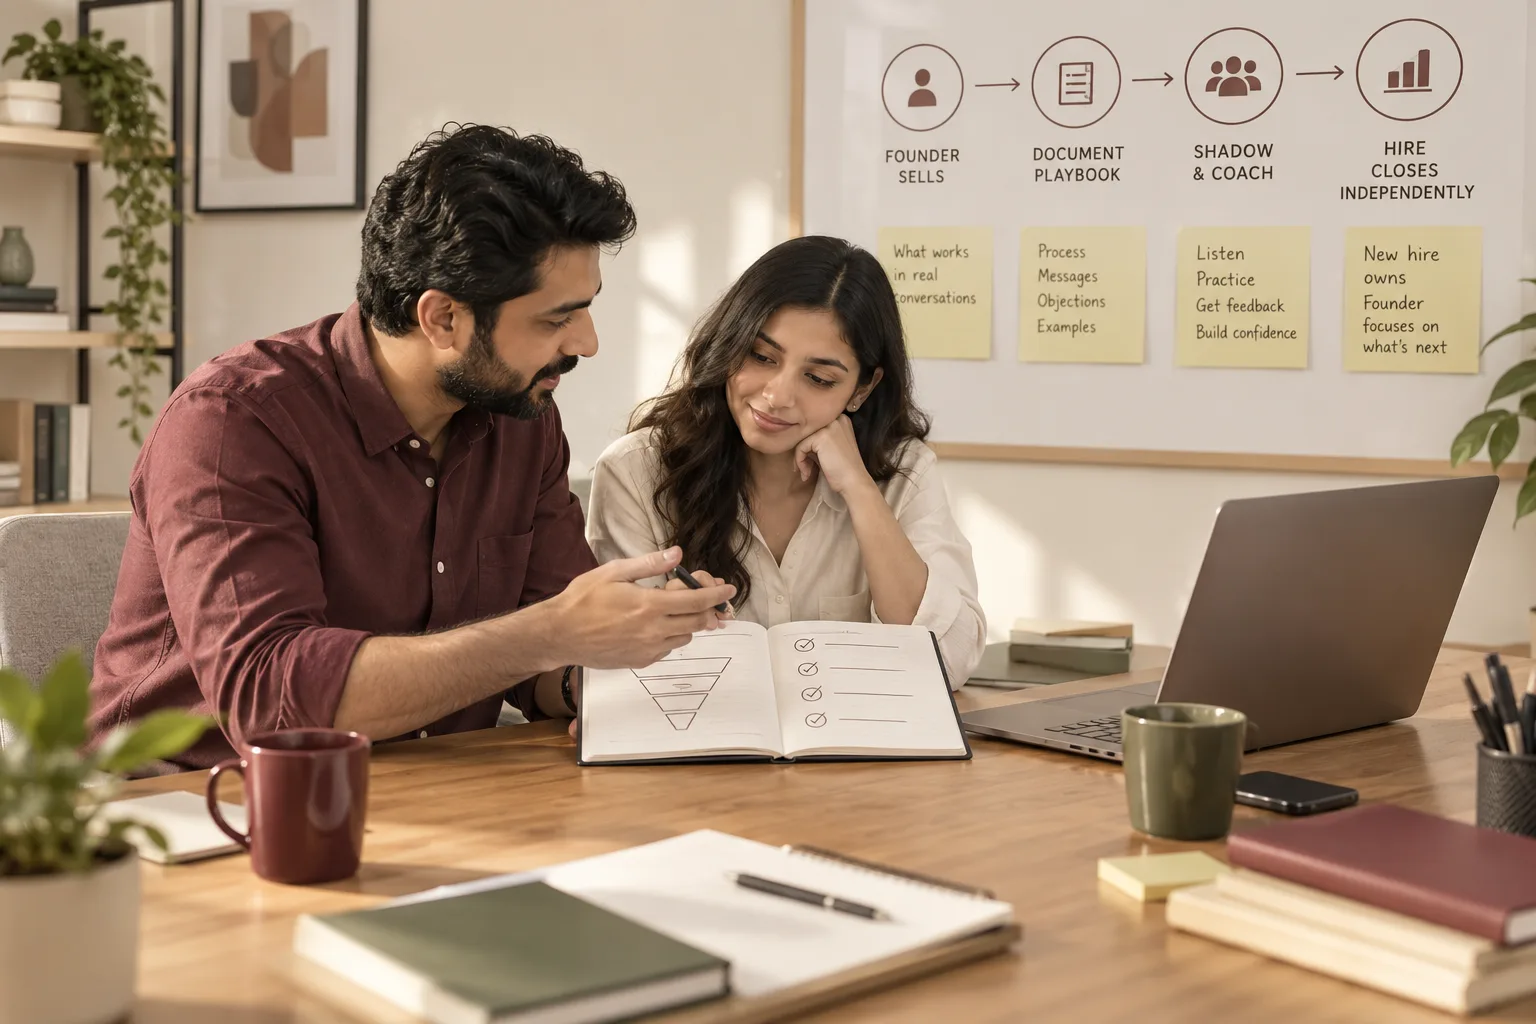
A founder hands over selling in stages: write down how you win, give the new seller the small accounts first, keep the largest relationships for a stated period, and agree what 'ready' means.
The GullySales team · Updated 17 Oct 2026 · 5 min read
On this page
You want to stop taking every call, but each time a new seller loses an order you take the next one back. The cause is often not the seller. You have never written down what you do on a call, so the new person guesses, and a guess costs an order. A handover goes best in a sensible order. You find your hidden rules, give away the least risky work first, put a date beside each piece you keep, and introduce your largest customers by telephone.
Find the rules you follow without knowing
Ask a founder how they sell and the answer is often "I just talk to them". That is the problem. For your next five calls, keep a notebook open or ask someone to listen. Write down the first question you ask and what you listen for in the answer. Note when price comes up, and what you say when a buyer asks for a quotation. Add what you refuse to do.
Here is what a list of hidden rules looks like once it is out of a founder's head.
1. I do not give a delivery date until I have checked cloth stock.
2. I ask which class sizes before I mention a price.
3. I never quote a school before I know who signs the purchase order.
4. If a buyer says "send me a quotation", I ask what it will be compared with.
5. I walk away from buyers who need 120 days' credit.
Rule 1 matters most. A new seller who promises a date from habit, and misses it, creates a problem you have to fix by phone.
A case: a school and hospital uniform maker in Sonipat
Here is an invented case. A firm makes uniforms for schools and small hospitals around Sonipat. The founder hired a seller and gave the seller the largest school account in the first month, with a short email of introduction. The principal cancelled the next meeting. The founder concluded the seller was green.
The seller was not the cause. The principal had heard nothing from the person trusted, only an email from a stranger. The founder phoned and apologised for the confusion, said who the seller was and what the seller would take over, namely measurement days and delivery questions. Anything large stayed with the founder. A fortnight later the seller ran the measurement day with the founder watching from the side. After two such days the principal called the seller first.
The founder had also never written rule 1. The seller promised a delivery date in the first week and missed it because a cloth lot was late, and the school was not pleased. Putting the rule on the first page of the playbook helped with the next hire, though the school stayed cool for a term.
Give away work in order of risk
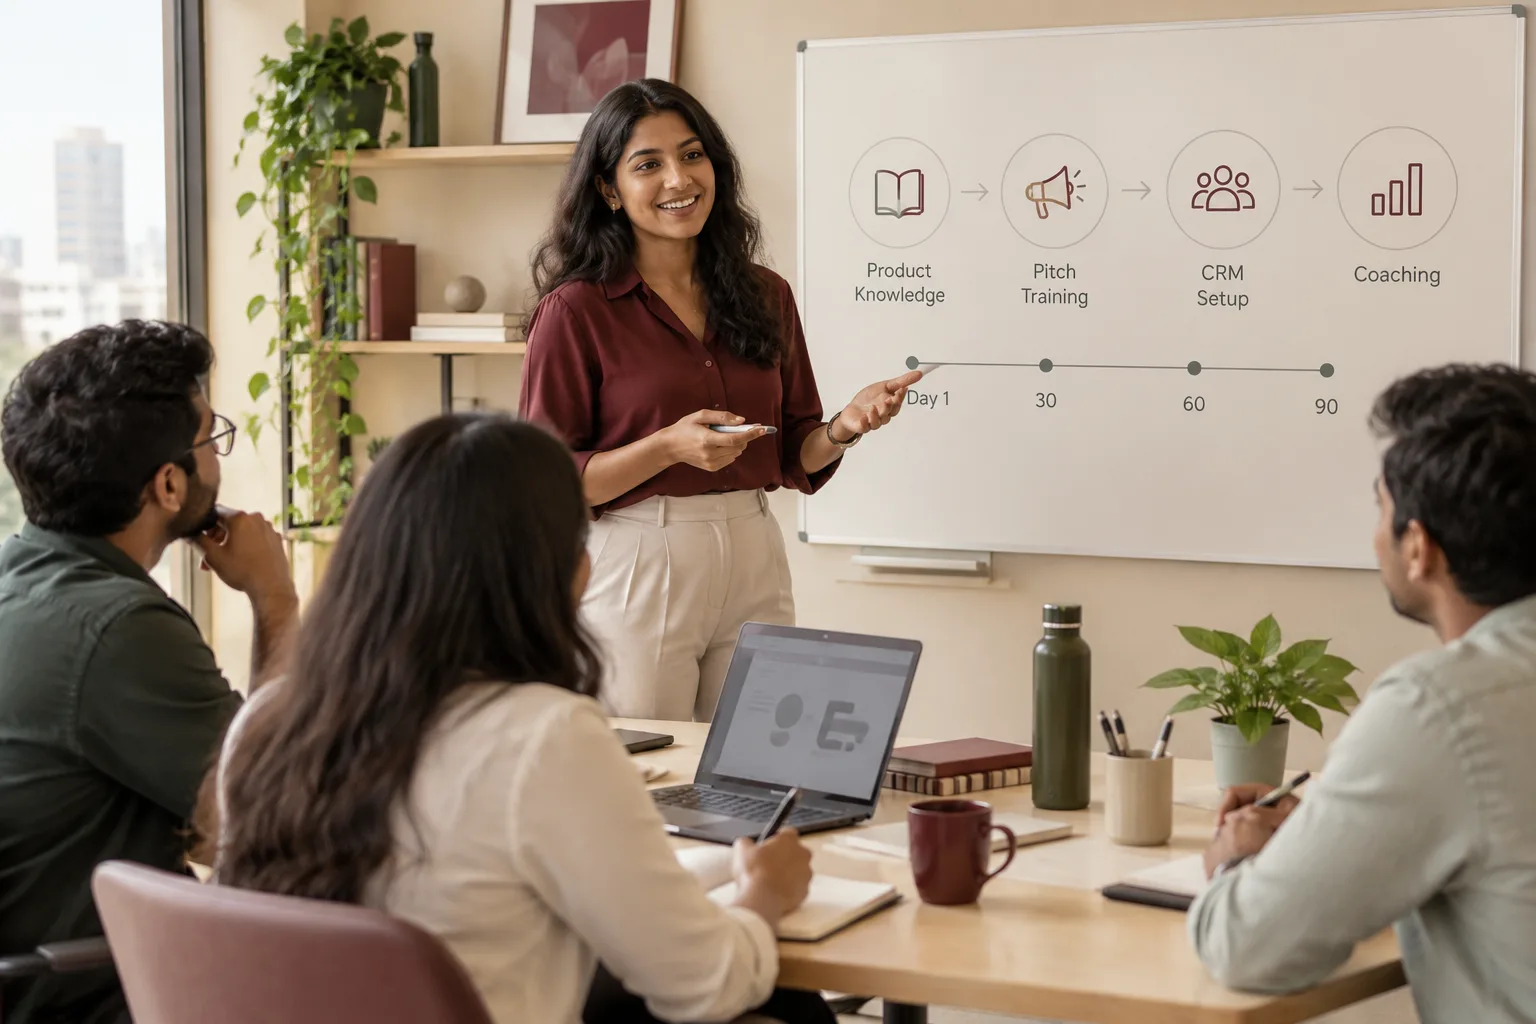
Do not hand over "sales". Hand over named pieces, and write a date beside each.
Start with replies to new enquiries and quotations within your own approval limit. These are the least risky and the most time-consuming, so the seller owns them from the first week. Next come quotations above that limit. The seller drafts, you sign, and you let go once the seller has had three accepted above the line. Repeat orders from existing customers follow once you have told each customer yourself and the customer has dealt with the seller twice.
Keep three things until you choose otherwise: your five largest accounts, pricing exceptions and old friendships. Write a review date for each now. For exceptions, publish a discount ladder so the seller is not guessing; a deal desk for an SME shows how. A handover without dates is a founder who keeps everything and a seller who waits.
How to introduce your biggest customer
Large customers often stay because they trust you personally. Pulling out suddenly can tell them they have been demoted. Ring, do not email. Say who is joining, what the seller will take over and that you remain available for anything big. At the next meeting, let the new seller speak for the first ten minutes while you listen. At the one after, the seller runs it and you attend only if the customer asks. Some buyers of large or custom orders will still want to meet you once, so plan for that meeting.
The customer should hear that there is now a second contact, not that they are being passed on. Never do this while the account is in a dispute, a late payment or a price renegotiation. Settle that first.
Write four pages, no more
The questions you ask first, with what a good answer sounds like. Your three commonest objections and the true answer to each, even when the true answer is that you are not the cheapest. Pricing rules: what you quote, what you never discount, who approves exceptions. And the kind of customer you walk away from, with an example. Founders often forget that last page, and new sellers need it. Writing sales process a new hire can run says more on the length.
Agree "ready" before the first week
Fix the test in advance, in a form a third person could check. For example: the seller has run discovery, quotation and close on three deals without you on the call, and one was a mid-sized order. Read the seller's notes on two deals as well. If you find a step you would do differently, ask whether it mattered. Different is not wrong. A seller who closes with a script you would never use has produced a result.
Hold off if these are true
Wait if you cannot say in two sentences why customers choose you over the next supplier. A seller cannot sell what you explain only by being in the room. Wait too if you have just a handful of repeat customers. There is nothing steady for a new seller to start on. A technical founder with few buyers might first want founder-led sales advisory to find what is repeatable.
Put real names and dates against each piece
Take the order of risk above, write real account names and real review dates beside each piece, and give it to your first hire before they accept the offer. Pushback on any line tells you how they will behave later. When you are ready to scope the handover, tell us what you need; who sells what is covered more widely under sales.