Notes for owners · Industry playbooks
How to keep founders after the company registration
Company registration is sold near cost, so the money is in what follows. Show founders their first year of filings on the day the certificate arrives.
The GullySales team · Updated 13 Nov 2026 · 7 min read
Rules for this trade differ by state and professional body, and they change. Check the current position with your own council or adviser before you act on anything here.
On this page
- You did not sell a company, you sold a start
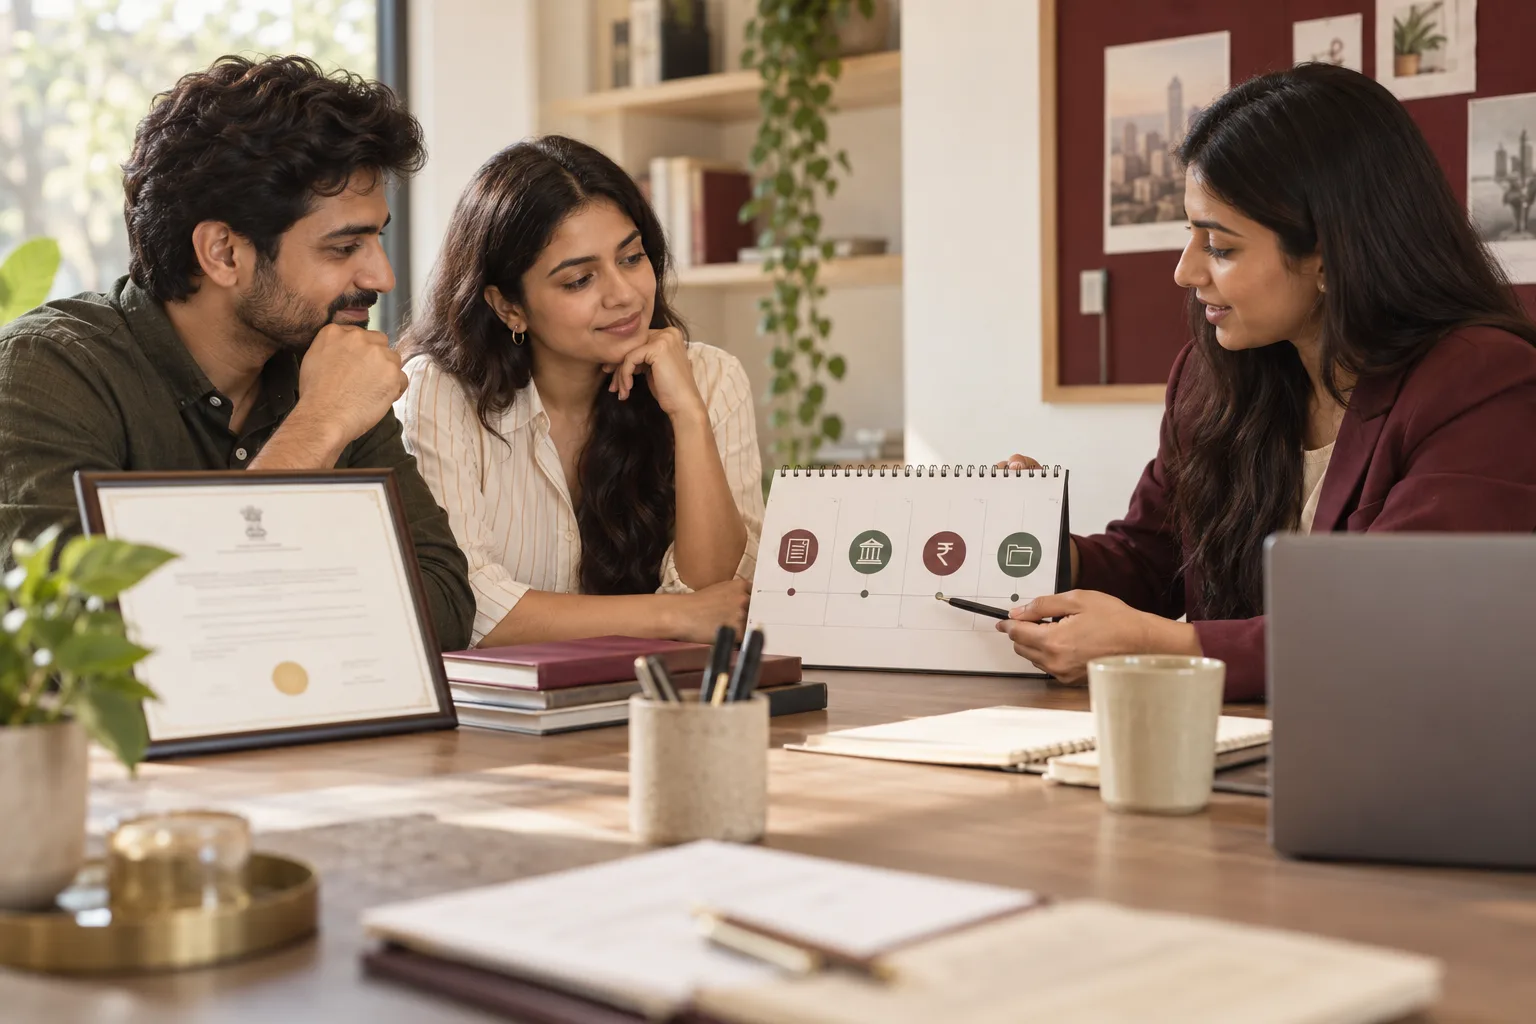
- Hand over a calendar, not a certificate
- The conversation that turns a filing into a retainer
- Go back for the ones who registered elsewhere
- What is not worth your money
- Know what the founder is afraid of
- Make a first-year folder for the founder
- Check in after the first obligation, not before
- Introduce the people the founder will need
- Be careful with what you promise
- Keep a record of why founders left
- Offer a second client conversation after the first quarter
- What to do next
Founders disappear after incorporation because the engagement ended with a certificate instead of a calendar. The registration fee is thin by design. The money is in the filings, the books and the returns that follow, and the only reliable way to keep that work is to show the founder the whole first year on the day you hand over the papers, with dates, with what each item costs, and with a name to ring.
You did not sell a company, you sold a start
Two founders who paid you to incorporate have no idea what they just signed up to. They think the hard part is finished. It has not started.
Within weeks there are obligations attached to the new company: the bank account and capital, the auditor's appointment, the declarations that follow a fresh incorporation, director identification compliance, the registers and the first board records. What exactly applies depends on the structure they chose and on rules that change, which is precisely why the founder cannot work it out from a blog post and will not try.
That confusion is the opportunity, and most registration services waste it by saying nothing. The founder's next search, three months later, finds a different firm.
Hand over a calendar, not a certificate
Make the handover a meeting rather than an email with attachments. Twenty minutes, in person or on a call, with one sheet.
| What the sheet shows | Why the founder keeps it |
|---|---|
| Every obligation that applies to their structure, in date order | It answers the question they were too embarrassed to ask |
| The dates worked out from their own incorporation date | Nothing generic, nothing to translate |
| What happens if an item is missed | Penalties focus the mind faster than any sales line |
| What each item costs if your office does it | Price raised calmly, before there is any pressure |
| The name and number of the person who handles their file | A firm with a face is harder to leave |
| The date you will ring to check | Puts the next contact in their diary, not only in yours |
Date the sheet and write on it that requirements differ by structure and change, and that the firm will confirm each item before it falls due. That line protects you and it is also true.
The conversation that turns a filing into a retainer
Have it before the first obligation is due, never after. Afterwards the founder has either done it himself, which makes you unnecessary, or missed it, which makes you part of the problem.
The conversation is short. Here is what is coming. Here is what it takes you to do it yourself, honestly described. Here is what this office charges to take it off your hands. Pick one.
Say the honest part too. A single-director company with no transactions does not need a bookkeeping retainer, and telling the founder so buys more credit than the retainer was worth. That founder will put you in front of the next three founders they meet, and every founder knows other founders.
For example, a registration firm in Koramangala, Bengaluru doing a steady run of private limited incorporations. The figures are illustrative. Say it registers sixty companies in a year, hands over documents by email to all sixty, and has the retainer conversation with eleven. The other forty-nine are not lost to a competitor. They were never asked.
Go back for the ones who registered elsewhere
A large part of this market registered through a cheap online portal, got the certificate, and heard nothing since. They are now approaching their first annual obligations with nobody to ring.
- Build a list of companies incorporated in your city in the previous year or two. Company data is published and widely available.
- Write to the director named on the record, not to a general address, and write about the deadline rather than about yourself.
- Offer to check what has and has not been filed so far. That check is the whole hook, and it is work you can do quickly.
- Follow with a call. Founders answer unknown numbers; established businesses screen them.
- Keep the ones who say not now, with a note of when their next obligation falls.
Where founders gather is the other route: incubators, co-working desks, startup meet-ups and the WhatsApp groups that form around them. One visible, useful person who answers compliance questions in those rooms does better than any advertisement, because the questions asked there are exactly the ones your sheet answers.
What is not worth your money
Competing on the headline registration price below everyone else. You will win files from people who chose on rupees and who will leave on rupees, and the compliance work, which is the actual business, follows the relationship rather than the discount.
Equally, do not quote a government processing time as a promise. Those timelines are published, they vary, and a founder who was told five days and waited three weeks writes the review that costs you the next ten enquiries.
Know what the founder is afraid of
A first-time founder is afraid of two things: missing a legal date and paying for something they did not need. A firm that speaks to both fears keeps the client. Say what is compulsory, what is optional and what depends on how the business grows. A founder who has been told the truth about the optional items trusts the firm on the compulsory ones.
Use plain words. Avoid saying "compliance" without explaining what it means for this company. "The annual return is a form that says who owns the company and who runs it" is clearer than a string of section numbers.
Make a first-year folder for the founder
Give the founder a single folder, physical or digital, with the certificate, the memorandum, the articles, the first registers and the calendar sheet. Add a one-page list of who in the firm handles what and which documents the founder must send each time. The folder is the founder's proof that the firm did a clean job, and it is what the founder hands to a bank, an investor or the next accountant. A client who holds your folder carries your name into those rooms.
Check in after the first obligation, not before
A call to ask how things are going is weak. A call to confirm that the first item on the sheet has been done, and to offer the next, is useful. Phone after the first due date has passed, tell the founder what was filed or what remains, and ask whether the bank account and the invoicing are set up. If the founder has questions on invoicing, tax registration or hiring the first employee, answer them or say honestly that they belong with another adviser.
Introduce the people the founder will need
A firm that registers companies knows the bank manager who opens current accounts for new companies, the trademark attorney, the person who prepares payroll and the tax adviser. Introduce those people, with the founder's permission, and note what you will be paid, if anything. Referrals handled honestly increase the founder's dependence on you for judgement, which is the reason a retainer exists.
Be careful with what you promise
Legal and financial work is regulated. Do not promise approvals, outcomes or tax savings. Name no penalty amount unless your professional adviser confirms the figure for the current year, and say that the founder's own accountant or company secretary decides advertising wording for the firm. Describe the work you do and the documents you prepare, and leave the guarantees out.
Keep a record of why founders left
When a founder does not retain you, ask politely why. The answer might be price, a cousin who is an accountant, a platform that bundles services, or the firm was slow to answer. Write each answer on one sheet. After a quarter the sheet will tell you whether the leak is price, speed or silence. Then address the largest one directly and measure again.
Offer a second client conversation after the first quarter
Three months in, the founder knows what the company needs. Offer a short review: what has been filed, what is coming, what has changed in the business, and whether the plan on the sheet still fits. A founder who has hired staff, taken a loan or added a product has new obligations that the first sheet did not cover. Update the sheet and note the date. The review shows the founder that the firm is watching the file, and it is the natural moment to discuss any extra work.
What to do next
Take the last twenty companies you registered and write beside each one whether anybody from your office has spoken to the founder since the documents went out. Then check which of them have obligations falling due in the next three months. Ring those first. In the first conversation this is the first list we ask for, because in this trade it is where the retained work has been sitting all along.
Put the reading to work
Try this with your own records.
Review repeat orders, inactive customers, and reasons for leaving. Separate a normal buying interval from a customer who stopped because of an unresolved problem.
How to review the result
Track the response through to a retained or repeat order, with discounts and service costs visible. Record why the customer returned rather than crediting every repeat purchase to the campaign.