Notes for owners · Branding and communication
Handling a customer complaint in a trust trade so it does not become a review
A four-step written routine for advisers, agents and lenders: acknowledge, log, own and close a complaint, then read the log to find the sales step that created it.
The GullySales team · Updated 17 Oct 2026 · 6 min read
Rules for this trade differ by state and professional body, and they change. Check the current position with your own council or adviser before you act on anything here.
On this page
- Why does a complaint here turn into a public review so quickly?
- What are the four steps?
- What goes in the log?
- How does the log fix the sales conversation?
- What did a Jabalpur home-loan consultant learn from three complaints?
- What should you not do?
- Build the log from the last few months of unhappy messages
A review often starts as something smaller: a call that went badly, a message nobody answered, or a promise the customer remembers differently from you. The review comes after they feel unheard a second time. What stops it is a four-step routine done in writing: acknowledge the same day, log it, name one owner, and close with a short note. The log then does a second job, because it shows which step of your own sales conversation created the problem.
Why does a complaint here turn into a public review so quickly?
Because the customer cannot judge the product, only you. A policy, a folio or a loan is a long promise that shows nothing for months. What they can judge is whether you pick up, whether you explain, and whether you take responsibility. When they feel you failed on those, they have no other evidence, so they write about you.
There is a quieter reason. In these trades the customer can be embarrassed. They signed something they did not fully follow, and the complaint is partly about that. Meet the embarrassment with respect, not with a copy of the form.
Rules on how complaints must be recorded and escalated differ by trade, body and state, and they change. Check with your own adviser or regulator what applies. What follows sits on top of any such rule.
What are the four steps?
- Acknowledge, the same day. A call if you can, then a message: "I understand your sanction letter has not reached you and your calls were not returned. I am looking into it myself. You will hear from me by [day you know you can keep]." Do not copy a day from this page. Name only one you control.
- Log it. One line in one place, with the customer's exact words.
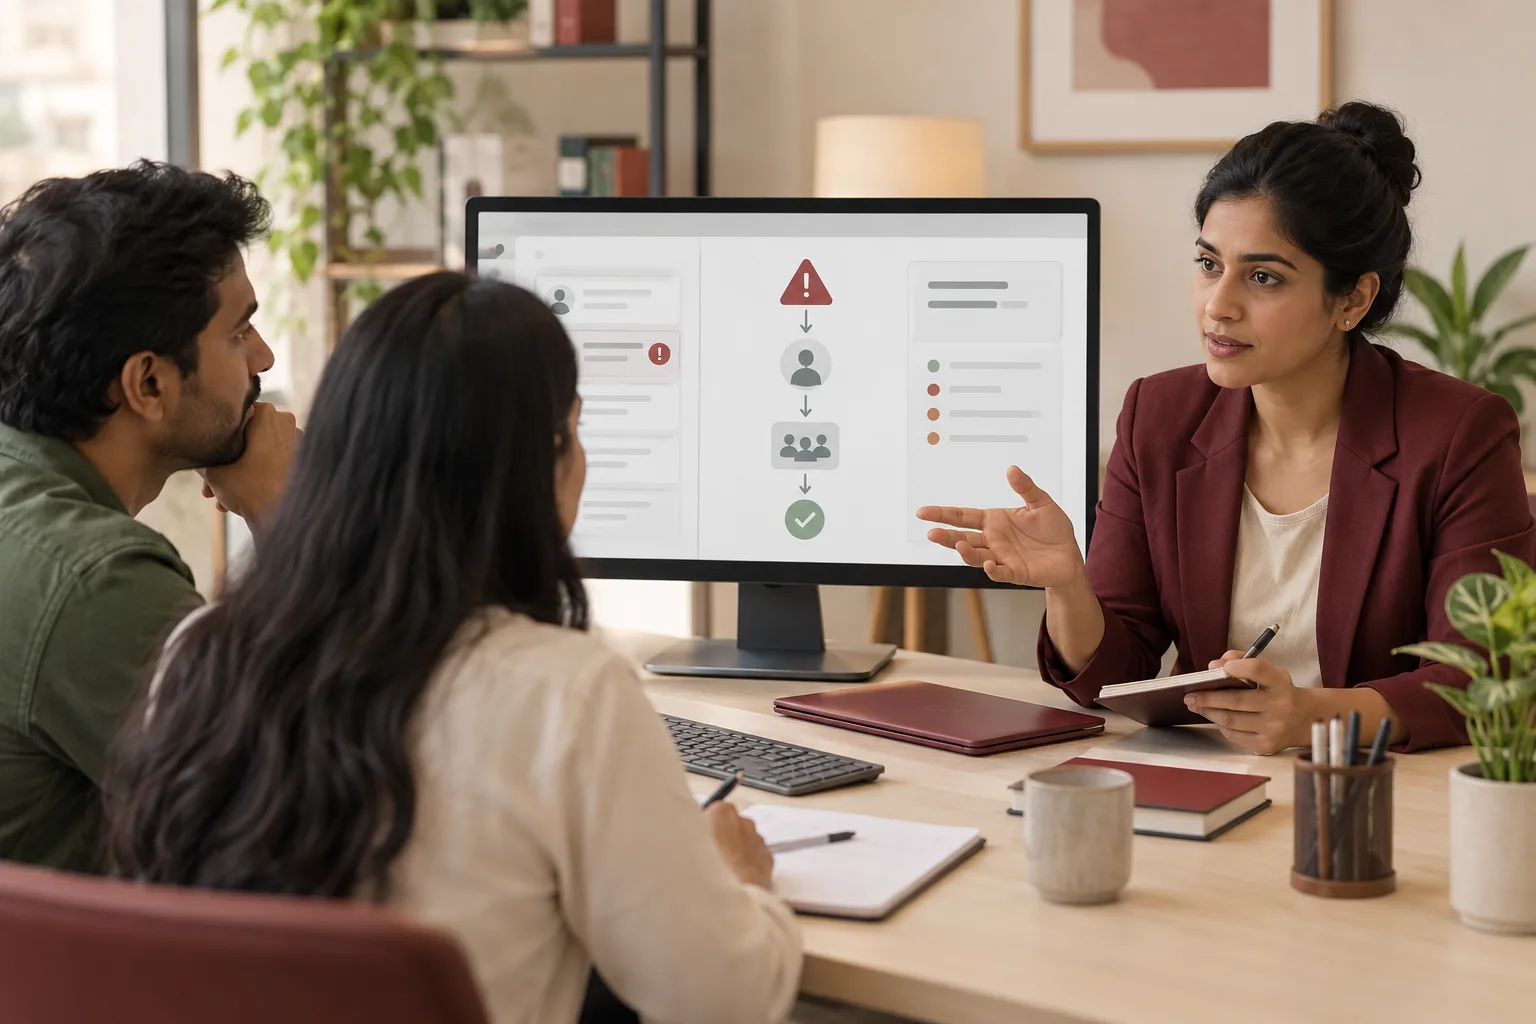
- Own it. One named person, not "the office". If another department is needed, that person chases it and the customer does not.
- Close it in writing. What you found, what you did, what happens next, and whether they are satisfied. If they are not, say what the next route is.
The common mistake is to skip the log because the problem was settled on the phone. A complaint settled by phone and never written down will be repeated for the next customer.
What goes in the log?
A shared sheet is enough. Fill every column before you close.
| Column | Entry |
|---|---|
| Date and channel | When and how: call, WhatsApp, walk-in, review |
| Customer and product | Name, and the product in your words |
| Their words | Copied, not summarised |
| Sale step it traces to | Enquiry, advice, form-filling, post-sale, renewal |
| Owner | One name |
| Promised by | The day you told them |
| Closed on / how | Date, and a line of outcome |
| Their reply | Satisfied, not satisfied, no reply |
The fourth column earns its keep. It forces the question: where did the trouble begin?
How does the log fix the sales conversation?
Read it as a list, not a set of stories. Sort by the sale-step column and count.
Many complaints tracing to advice mean the customer heard a promise where you gave a description. Look at how you speak of returns, claims or approval, and replace "you will get" with what is in the document and who decides.
Form-filling clusters mean customers sign without understanding. Slow the signing down and read the three lines that matter aloud. Post-sale silence means you need the welcome note and named contact described in what to tell a new customer straight after they sign.
If the complaints cluster around one person on your team, that is a coaching conversation and not a punishment. Listen to a call or two before you decide.
What did a Jabalpur home-loan consultant learn from three complaints?
Here is an invented case. A home-loan consultant in Jabalpur has a borrower waiting ten days for a sanction letter. The borrower rings three times in one day. The third call goes unanswered, and that night the borrower posts a one-star review: "Takes your papers, then disappears."
The consultant's first impulse was to reply with the timeline of the file. A colleague said no: facts do not belong in a public reply. So the consultant rang the next morning and apologised for the missed calls without explaining them away, then went to the lender's branch to chase the letter. It was logged, owned and closed by message once the letter was issued. The one-star review stayed up. The borrower never edited it, and the consultant let it be.
The log showed something wider. Four of the last six complaints began with an unreturned call during a wait. The consultant's sales conversation said "call me any time", which was not a promise anyone could keep. It became "ring this number first; my assistant handles it when I am in the field", with a second name. The promise now matched what the office could do.
This works when you can be reached. If you are one person, say so honestly at the start and give the lender's own helpline as the fallback.
What should you not do?
Do not offer a gift or discount to get a review taken down. Do not discuss a customer's file in a public reply. Do not promise an outcome that depends on an insurer, a lender or a regulator; say what you will do, and leave their decision to them. And do not wait for the customer to chase. The second message is yours to send.
Build the log from the last few months of unhappy messages
Open your phone, your WhatsApp and your inbox, and list every unhappy message from the last few months, including those you think you resolved. Put them in the sheet and sort by sale step. The pattern shows itself quickly, and the first row you will want to fix is the one with the most entries. Our post on handling customer complaints and escalations covers the general routine, and the wider picture for your trade is on our financial services page. If you want a hand setting up the routine across your team, our complaint and escalation management service is where that work sits, and tell us what you need is the way in.