Notes for owners · Sales management
Talking about finance and insurance at delivery without souring the sale
How a car showroom can explain loan, insurance and add-on charges once, in writing and before delivery day, so the billing desk stops being the moment a happy buyer turns sour.
The GullySales team · Updated 17 Oct 2026 · 6 min read
On this page
- Why do add-ons sour a happy sale?
- What one-page sheet should the buyer see before delivery day?
- How do you say it aloud?
- For example, a showroom in Kolhapur on a delivery Saturday
- What if the loan or the policy is not ready on the day?
- When should you not push an add-on?
- Training the people who do the talking
Nobody forgets the billing desk. A buyer has chosen the car, agreed the price and arranged for the family to be there. Then a sheet appears with a processing fee, an extended warranty, a coating, a longer insurance cover and a tracker, none of which anyone mentioned. The buyer pays, because the car is outside, and remembers. The way to avoid this is dull and effective: explain each add-on once, in writing, before delivery day, with the choice left to the buyer.
Why do add-ons sour a happy sale?
The price of the car was negotiated in the open. The price of the extras is usually not. A buyer feels a surprise at the end of a long process as a trick, whatever the item costs. Even a fair charge sounds unfair when it arrives with the car keys in the next room.
There is a second cost. The salesperson who built the relationship is not at the billing desk, so the buyer faces a stranger with a pen. If the buyer feels pushed, the story told to family and the WhatsApp group is about that moment, not the test drive.
What one-page sheet should the buyer see before delivery day?
Send it before delivery day, on WhatsApp or paper, with the same layout for every buyer. It does the explaining so that the conversation can be short.
| Item | What it is | Who requires it | Cost | Your choice |
|---|---|---|---|---|
| Ex-showroom price | Agreed price of the car | You | As quoted | n/a |
| Registration and road charges | Government and local charges for your state | Set by the authority | As per the state | Required |
| Insurance | Cover for the vehicle in the first year | Insurer sets terms; check what applies | Insurer's quote | Pick insurer and cover |
| Loan processing | Lender's charge for the loan | Lender | Lender's schedule | Only if you take the loan |
| Extended warranty | Cover beyond the standard warranty | Optional | Quoted | Yes or no |
| Accessories and coatings | Items fitted by the showroom | Optional | Quoted | Item by item |
Fill the "who requires it" column honestly. A buyer accepts a compulsory cost more easily than one suspected to be optional dressed up as required. Check the current position on statutory charges, insurance and lending terms with the insurer, the lender or your own adviser before you print numbers.
How do you say it aloud?
The sheet is not a replacement for the conversation, but it makes the conversation easy. Three lines carry most of it.
First, the frame: "Before delivery I want you to see everything you will pay, so nothing is a surprise on the day." Then, at each optional item: "This one is your choice. If you skip it, nothing else changes." Finally, for insurance and finance, say who decides: "The insurer sets the premium and the lender approves the loan. I can only show you what they have quoted so far."
Avoid "everybody takes this", which a buyer hears as pressure, and avoid "you must" about anything optional. If you are unsure whether an item is mandatory, find out before the buyer asks.
For example, a showroom in Kolhapur on a delivery Saturday
An invented Kolhapur showroom where most deliveries fall on Saturday. A buyer books a mid-range hatchback and agrees the price. At the billing desk the buyer is handed a sheet with a coating nobody asked for and a longer warranty already ticked. There is an argument, a payment and a silent drive home. The salesperson hears about it a week later from the buyer's brother-in-law, who had been about to book a car there too.
The showroom changes three things. The executive sends the one-page sheet on WhatsApp right after booking. Nothing is pre-ticked: each optional item has a blank for yes or no. And the executive stays through the billing conversation, saying little. There is a snag. Some buyers now say no to the coating, so add-on income per car falls on those deliveries, and the executive spends extra time on the sheet. Whether that is repaid in referrals is for the showroom to read from its own records after a few months.
What if the loan or the policy is not ready on the day?
Say so on the sheet, in advance, in one line. What should the buyer bring? What has the lender or insurer still to confirm? What happens to the delivery date if it is late? Loan approval and policy issue sit with the lender and the insurer, so the dealer promises neither. A delay explained beforehand costs less goodwill than a delivery that stalls at the desk while the family waits.
When should you not push an add-on?
Skip the pitch when the buyer is already stretched on the loan, when the item duplicates something the car includes, or when the buyer has said no once. A second ask turns a closed question into pressure. Skip it also when you cannot explain the benefit in two sentences without a brochure. If you cannot, the buyer will not value it either.
Do not describe a financial product as an investment, or promise savings, approvals or claim outcomes. Say what the product covers on paper and where its terms can be read.
Training the people who do the talking
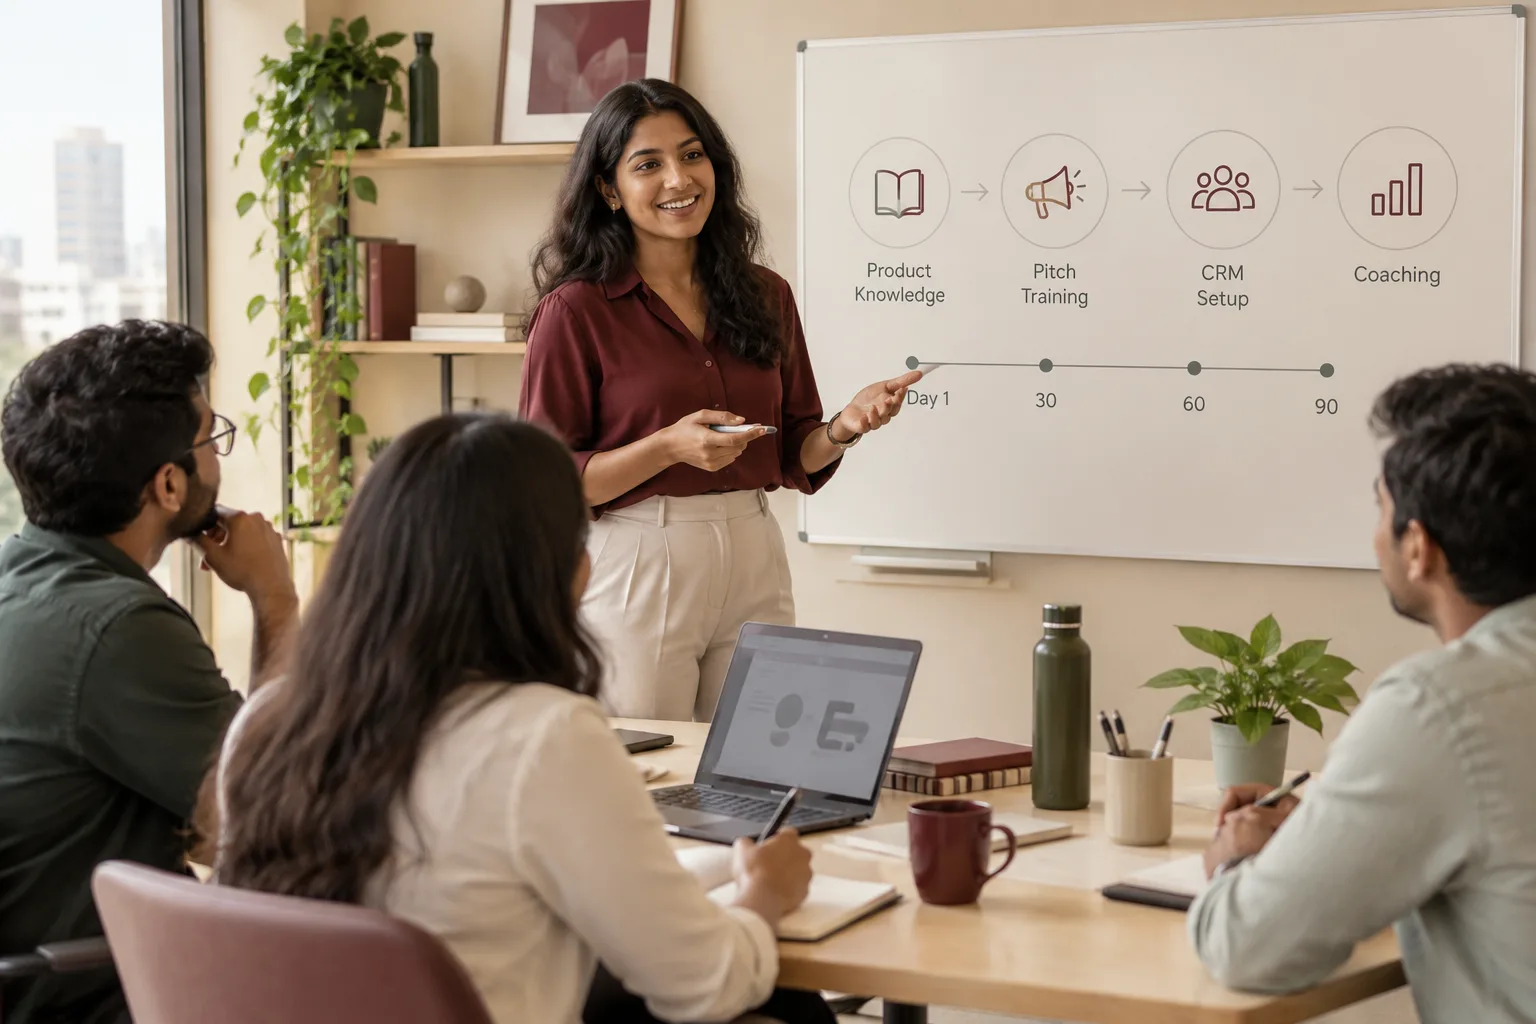
Much billing-desk friction is habit, not policy, so it is fixed by the team. Walk through the sheet together, take turns playing the buyer who says "I'll think about it", and practise saying "that's your choice" without a sigh. Respectful closing tactics and common sales objections help with the wording.
Draft the sheet this week from your own last three billing slips and send it to the next buyer who books. If you want the talking practised as well, sales closing training covers it, and the same sheet suits any automotive showroom. When delivery day is where good sales go flat, tell us what you need.
Related services
Industries