Debt recovery and collection agencies · CRM
Track every lender, empanelment and creditor enquiry to the next step.
A CRM for a collection agency is a record of lenders, empanelment applications and creditor enquiries, so no pack waits unsent and no panel reopening is missed. GullySales sets up the sheet or tool and keeps the agency's case data out of it.
Scope, fee, reporting and term are agreed in writing after we have read your brief and spoken to you.
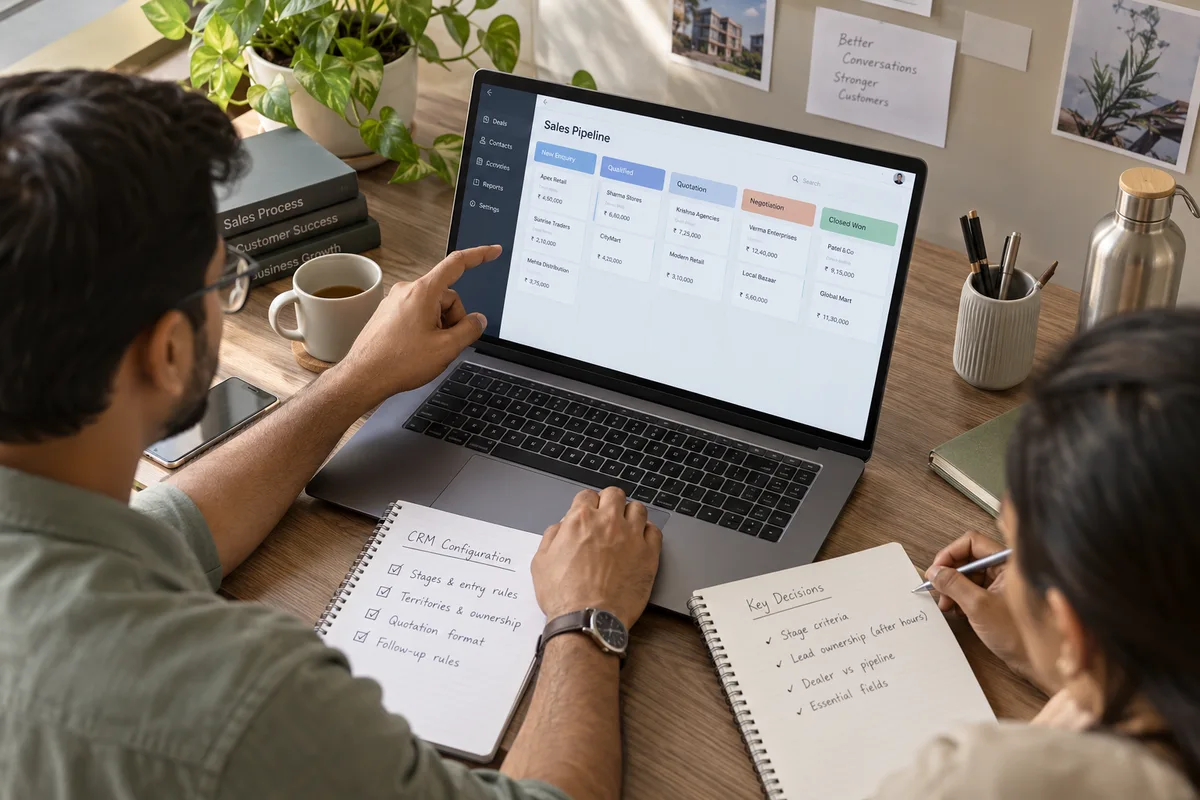
What CRM means
A CRM is the record where every enquiry, call and quote is kept against a customer, replacing separate notebooks, spreadsheets and memory. GullySales sets up or cleans an existing CRM and reports from it by enquiry outcome rather than by activity logged.
Also for debt recovery and collection agencies
- Lead generation for debt recovery and collection agencies
- Follow-up systems for debt recovery and collection agencies
- SEO for debt recovery and collection agencies
- Local SEO for debt recovery and collection agencies
- Social media marketing for debt recovery and collection agencies
- Content marketing for debt recovery and collection agencies
- Buyer personas for debt recovery and collection agencies
- WhatsApp marketing for debt recovery and collection agencies
Sales and marketing for debt recovery and collection agencies, the overview.
Last updated 14 Nov 2026. Rules for this trade differ by state and professional body, and they change. We describe restrictions in general terms, so check the current position with your own council or adviser before you publish anything.
For debt recovery and collection agencies
Where it usually goes wrong, and what we would do.
“Empanelments are tracked in email”
A lender asks for a document in an email thread, and the thread is in one person's inbox. When that person is away, the application stalls.
“Case software and sales records are mixed”
Account-level data from collection work sits in the same sheet as sales contacts. That is a data-protection risk.
“No memory of why a lender said no”
The same product or region is offered again to a lender that had already declined.
What we do
What we deliver for debt recovery and collection agencies.
The work available for this need. We agree the deliverables and responsibilities for your engagement in writing.
A lender and contact register
A sheet of each lender, the contacts, the products and regions of interest, the panel status and the date for the next step.
Result: Every lender has an owner and a date.
A document tracker
A list of what each lender asked for, when it was sent and what is outstanding.
Result: Applications do not stall for a missing paper.
An enquiry sheet for business creditors
Columns for source, type of dues, age of invoices, status and next step. No debtor details beyond what is needed.
Result: Creditor enquiries are followed up.
A data separation note
A written line between sales records and case data, with access limited to those who need each.
Result: Borrower data stays with case work.
How the result is measured
- Enquiries logged in the CRM
- Data completeness
- Reports generated from CRM data
Recorded as a baseline before work starts, so every later report has an honest comparison.
What to record, and when
What to write down for each lender and creditor enquiry, and who fills it.
- Lender, contact and role
- Filled by whoever meets the lender. Lets you know whom to write to at a panel reopening and who approved last time.
- Products and pincodes of interest
- Filled after the first call. Lets you offer new cover when you add a region and avoid offering what the lender does not need.
- Documents asked and sent
- Filled by the person preparing the pack. Lets anyone see what is pending without searching email.
- Reason for a pause or a no
- Filled by the owner of the lender. Lets you return when the reason changes, such as a panel closing or a region added.
- Do you need software yet?
- A shared sheet does for a handful of lenders. Move to software when several people update it or reminders are missed. Keep case data out of either.
Who it is for
This is written for these debt recovery and collection agencies.
- Agencies collecting for banks and small finance banks
- Agencies working for NBFCs in retail, vehicle and business loans
- Telecom and utility bill collection agencies
- Credit card and consumer finance collection teams
- Receivables follow-up for MSMEs, distributors and traders
- Tele-calling-based collection centres
- Field-agent networks covering towns and districts
- Legal-notice and pre-litigation support firms
- Agencies serving housing finance and microfinance lenders
- Collection arms of larger financial service groups
Before you decide
When this may not be the right fit.
- Your case data and sales contacts sit in one file, and that has to be separated before anything is added.
- No one owns lender relationships, so a record would have no one to fill it.
Before you decide
Agree the work. Know how to judge it.
CRM for debt recovery and collection agencies: use these checks to prepare, choose the scope, and review what changes.
Bring the right evidence
List the records your team uses and show how an enquiry becomes an order today. Bring examples of duplicate entries, missing owners, and reports that require manual correction.
Make the scope clear
Agree the stages, required fields, access roles, and integrations before configuring the system. Separate software subscriptions from setup, data work, and training.
Check the work in use
Ask the people who will use the CRM to complete a real handover and find the next action without help. Check that the management report can be traced back to individual records.
Know when to change course
If the process is unclear, buying a more complex CRM adds more places for confusion. Start with the minimum fields and rules the team can use consistently.
These are discussion points, not a fixed package. GullySales confirms the deliverables, responsibilities, fee, and term in writing after reading your brief and speaking with you.
Before we start
What to have ready before the work starts.
The records, access and decisions this work needs from debt recovery and collection agencies. Anything missing is noted in the written scope, with who will supply it.
- The sheet or notebook of lenders you use now
- Whatever records your lenders and contacts at present, even a spreadsheet or a diary. We read it to see what is kept and what is lost. We import only what you agree, and without it we design from conversation and may miss a habit that matters. Even a sheet with gaps shows how the team thinks, and we keep a copy of it as it stood so the import can be checked against the original.
- A list of documents lenders ask for
- Registrations, code of conduct, training notes, insurance, references and reporting format, as lenders have asked for them. The tracker is built on this list. If it is incomplete, the tracker misses what a lender will ask next.
- The names of people who need access
- A list by role of those who will open lender records, with the reason. Access is set to it. If not given, we limit it to the directors and the person who sends packs until you decide. Each document needs a name that matches what a lender calls it, and where a lender uses a different name, tell us, so the tracker shows both.
- A separate home for collection data
- Confirm that mandate data stays in your collection system and not in the CRM. We build around that line. If any lender's records currently sit in a shared sheet, tell us, and we advise moving them before we start. Tell us also whether any lender has asked that its data be kept apart, since that request shapes who may open the register.
- One person to own the register
- Someone must keep the register right after we leave. If no one owns it, panel dates and documents go stale, and the reminders become noise. We ask for a name before the switch date is set. If a lender's checker visits the agency, this person can show the register and answer how a pack was tracked.
How it works
How the CRM work runs
The work itself, in order. How an engagement starts, from your brief to a written scope, is set out on our method page.
- 1
Trace one lender from first meeting to panel
We follow a lender you have won, without naming figures, from the first call through the pack sent, the documents requested and the day the panel opened. You tell us where the file stalled. The CRM is shaped around that route, not around a standard sales funnel. We note, too, the point at which a lender's checker asked for something the agency did not have ready, since that gap is where the register should prompt.
- 2
Draw the register of lenders and contacts
We list the fields you need for a lender: contact roles, products, regions, empanelment status, documents sent and date of the last reply. We leave out anything that is a borrower's data. Nothing is built until you have signed off the fields. Each field has a plain name, a reason and a person who fills it, and a field no one can explain is removed before the build.
- 3
Set up the document tracker in a test copy
A lender asks for a long list of papers, and one forgotten certificate stalls a panel. We build the tracker with a line per document and a status, load invented lenders into a test copy and ask your team to try them. You tell us which document names do not match what lenders ask.
- 4
Add the enquiry sheet for business creditors
A separate sheet records a business creditor's enquiry: the type of business, the nature of the outstanding invoices and the next step. We keep it apart from the lender register. We test with invented entries until the team finds it quicker than a notebook. We also separate who may add an enquiry from who may change a stage, so an enthusiastic junior cannot mark a business creditor as won.
- 5
Write the rule that keeps debtor data out
With your adviser we write a short note that says what the CRM never holds: no debtor names, accounts or balances. The lender's mandate data stays in the collection system. We set field limits and access to match, and the director signs the note. The note is kept beside the CRM and read again whenever someone asks for a new field, so the line holds as the system grows.
- 6
Switch over and compare against the old record
On a day you choose, the notebook or sheet stops and the CRM starts. Later we compare the number of lenders, packs sent and panels reopened recorded there with the earlier sheet, and you decide what to add or remove. We stay with the team through the first real lenders, noting the fields that go unfilled, and you decide whether to keep them.
Where this fits
Three pieces of sales work, in this order.
This work sits inside sales management. A target, a review routine and someone who owns the number.
Step 1
Sales audit
Find where deals are being lost and what to fix first.
Start here if you cannot say where orders are lost.
Step 2
Sales process design
One written way to sell, from first enquiry to repeat order.
Start here if every salesperson sells differently.
Step 3 · you are here
Sales management
A target, a review routine and someone who owns the number.
Start here if the team has targets and no routine.
FAQ
Questions owners ask before they call.
Not here? More answers, or ask on WhatsApp.
Is a spreadsheet enough?
How do we get the recovery team to keep it updated?
What about WhatsApp chats with lender contacts?
Who owns the data?
Can the CRM link to our collection software?
What if the lender's checker asks who can see their data?
How much does it cost?
How long is the contract?
How soon will we see results?
Who will actually do the work?
More for debt recovery and collection agencies
Related work to consider.
Closest to this: leads and follow-up
Also for debt recovery and collection agencies
- SEO for debt recovery and collection agencies
- Local SEO for debt recovery and collection agencies
- Social media marketing for debt recovery and collection agencies
- Content marketing for debt recovery and collection agencies
- Buyer personas for debt recovery and collection agencies
- WhatsApp marketing for debt recovery and collection agencies
Or start from the overview: sales and marketing for debt recovery and collection agencies.
Your next practical step
Tell us what you are trying to grow, and we will read it before we call.
Eight short steps, mostly taps. Skip anything you would rather answer on the call.