Credit score and credit repair advisers · CRM
Keep each client's story, consent and next step in one place that is not a chat app.
A CRM for a credit adviser is the single record of every enquiry, what the person asked, what consent they gave and what happens next. GullySales sets up the fields and the habits around them, with careful handling of personal data and no storage of reports in a chat thread.
Scope, fee, reporting and term are agreed in writing after we have read your brief and spoken to you.
What CRM means
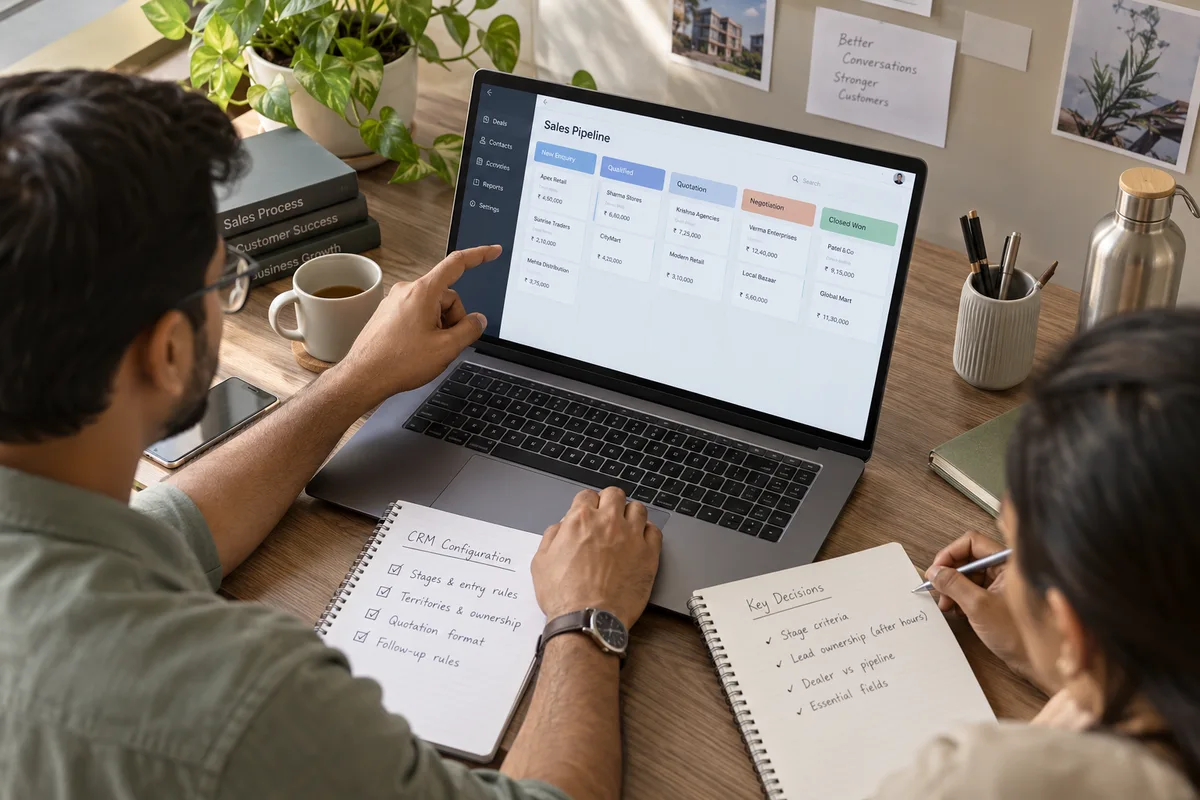
A CRM is the record where every enquiry, call and quote is kept against a customer, replacing separate notebooks, spreadsheets and memory. GullySales sets up or cleans an existing CRM and reports from it by enquiry outcome rather than by activity logged.
Also for credit score and credit repair advisers
- Lead generation for credit score and credit repair advisers
- Follow-up systems for credit score and credit repair advisers
- SEO for credit score and credit repair advisers
- Local SEO for credit score and credit repair advisers
- Social media marketing for credit score and credit repair advisers
- Content marketing for credit score and credit repair advisers
- Buyer persona for credit score and credit repair advisers
- WhatsApp marketing for credit score and credit repair advisers
Sales and marketing for credit score and credit repair advisers, the overview.
Last updated 14 Nov 2026. Rules for this trade differ by state and professional body, and they change. We describe restrictions in general terms, so check the current position with your own council or adviser before you publish anything.
For credit score and credit repair advisers
Where it usually goes wrong, and what we would do.
“The story lives in WhatsApp”
Reports, PAN images and loan statements sit in a chat that three people can open. There is no record of consent, and a staff member leaving takes the history with them.
“No field for the reason”
A sheet with name and number tells you who rang but not why. The decline reason decides the advice, so it belongs at the top of the record.
“Personal data held longer than needed”
Copies of reports and identity papers pile up years after a review ends. A record without a deletion rule becomes a liability.
“Follow-ups depend on memory”
An adviser meant to call back on a day when a client would have the statement ready, and forgot. The record should hold the next step and its date.
What we do
What we deliver for credit score and credit repair advisers.
The work available for this need. We agree the deliverables and responsibilities for your engagement in writing.
A field list for the enquiry record
A short set of fields: source, decline reason, bureau mentioned, consent given, next step and owner, with who fills each one.
Result: Every enquiry carries the same facts.
A consent record
A field and a wording for what the person agreed to, such as contact by call or message, noted with the date.
Result: You can show what a person agreed to.
A document handling rule in the record
A note on where each paper is stored, who may open it and when it is deleted, linked from the client file but kept apart from chat.
Result: Papers are not scattered across phones.
A next-step reminder list
A daily view of calls due, showing the promise made and the date named.
Result: No promised call is missed.
A hand-over view for staff changes
A summary screen that lets a new person read the history of a file in a minute.
Result: A change of staff does not lose a client.
How the result is measured
- Enquiries logged in the CRM
- Data completeness
- Reports generated from CRM data
Recorded as a baseline before work starts, so every later report has an honest comparison.
What to record, and when
What a credit adviser records for each enquiry, and the moment to record it.
- Source of the enquiry
- Write it at the first contact: search page, accountant, talk, Maps or family. Without it you cannot tell which door brings consultations.
- Decline reason as told
- Record the lender's words and the product applied for. It decides what the review covers and what to ask the client to bring.
- Consent and channel
- Note what the person agreed to and by which channel, with the date. Check it again before a follow-up message or call.
- Documents received and where kept
- Log what arrived and the place it is stored, not the file itself. Delete on the date agreed with the client.
- Next step and date
- The promise made on the call and the day it falls due, with an owner. The reminder list is built from this field.
- Do you need software yet?
- A sheet with locked columns is enough for a single adviser. Move to a CRM when two people share files or when follow-ups are being missed.
Who it is for
This is written for these credit score and credit repair advisers.
- Individual advisers who work with salaried applicants after a home or car loan decline
- Small business credit advisers helping proprietors with working capital and overdraft files
- Advisers focused on settled and written-off accounts and how lenders read them
- Report review services that explain the bureau report and mark errors for dispute
- Loan and DSA-linked advisers who prepare an applicant before a fresh application
- Advisers serving NRIs and returning residents with a thin or old Indian credit history
- Financial coaching practices that add credit education to budgeting and debt plans
- Small firms with a few advisers working across a city or online across states
Before you decide
When this may not be the right fit.
- You have only a handful of clients a month and one adviser, so a plain sheet with consent noted is enough for now.
- You have not decided how long reports and papers are kept, so the record would start storing documents without a rule.
- Your staff will not update any record, so software would be set up and then left empty.
Before you decide
Agree the work. Know how to judge it.
CRM for credit score and credit repair advisers: use these checks to prepare, choose the scope, and review what changes.
Bring the right evidence
List the records your team uses and show how an enquiry becomes an order today. Bring examples of duplicate entries, missing owners, and reports that require manual correction.
Make the scope clear
Agree the stages, required fields, access roles, and integrations before configuring the system. Separate software subscriptions from setup, data work, and training.
Check the work in use
Ask the people who will use the CRM to complete a real handover and find the next action without help. Check that the management report can be traced back to individual records.
Know when to change course
If the process is unclear, buying a more complex CRM adds more places for confusion. Start with the minimum fields and rules the team can use consistently.
These are discussion points, not a fixed package. GullySales confirms the deliverables, responsibilities, fee, and term in writing after reading your brief and speaking with you.
Before we start
What to have ready before the work starts.
The records, access and decisions this work needs from credit score and credit repair advisers. Anything missing is noted in the written scope, with who will supply it.
- Open files and who holds each
- Bring the list of live clients and where their papers and chats sit. It tells us what must move. If one adviser keeps everything in a personal phone, say so now. Add the files closed in the last season, so the record starts with history as well as live work.
- A consent wording your adviser approves
- The record notes what each person agreed to. Bring the wording you use or ask your adviser to approve ours. Without it, the consent field stays empty. Add what the person was told when they agreed, in the words used.
- A rule for how long data is kept
- Decide with your own adviser how long personal data is held and who deletes it. We set a place for the date. Data kept longer than needed is a risk. Tell us what you currently do with files of people who never returned.
- Names of staff who will use the record
- List who enters data and who only reads. Each gets their own login. A shared login hides who changed a file. Decide whether each person sees only their own files or the whole list.
- The tools you already pay for
- Tell us about any existing spreadsheet, form or messaging tool. If one fits, we use it. A new tool is a separate decision. Bring the exports if any tool can produce them.
How it works
How the CRM work runs
The work itself, in order. How an engagement starts, from your brief to a written scope, is set out on our method page.
- 1
Trace one client file from first message
We take a closed file and follow it from the first message through the consultation to the next step, with your adviser. You note where things were kept: a chat, a notebook, a folder. The stages and fields of the record are copied from this path. We also record which of those moves were made by hand, since they are the places where files get lost.
- 2
List the fields the record must hold
We agree the fields: source, the decline or worry, the question asked, the consent given and the next step. You remove any that nobody will fill. Personal data is kept to what the work needs. A field for the reason the person came, in their words, is kept free-text so the adviser can add a line.
- 3
Write the consent record
We add a place to note what the person agreed to: being contacted, a call back, a message on a given channel. You decide the wording with your adviser. A contact with no consent noted is not messaged. A reminder fires when consent is missing and the next contact is due.
- 4
Set the rule for papers and reports
We write where reports and identity papers are kept, which is not in a chat or the CRM notes, and who may open them. You approve the rule. The record links to the location without holding the file. Staff are told which papers must never be forwarded on chat, and the rule is pinned where they can see it.
- 5
Move the live files and test a hand-over
We move the open files from chats and notebooks into the record, then ask a colleague to take over one file using only the record. You see what is missing. We add the missing fields to the record, and run the hand-over test once more with a different colleague and a different file.
- 6
Read open files and next steps against before
After use, we count enquiries, consultations and files with a next step against what the old method showed. You decide which stage or habit to change. Next-step reminders that were never opened are listed for the adviser to review.
Where this fits
Three pieces of sales work, in this order.
This work sits inside sales management. A target, a review routine and someone who owns the number.
Step 1
Sales audit
Find where deals are being lost and what to fix first.
Start here if you cannot say where orders are lost.
Step 2
Sales process design
One written way to sell, from first enquiry to repeat order.
Start here if every salesperson sells differently.
Step 3 · you are here
Sales management
A target, a review routine and someone who owns the number.
Start here if the team has targets and no routine.
FAQ
Questions owners ask before they call.
Not here? More answers, or ask on WhatsApp.
Do we need a CRM or will a spreadsheet do?
How do we get staff to update the record?
What do we do with the WhatsApp chats?
Who owns the data in the CRM?
What do we do with years of old WhatsApp chats?
Can the CRM send messages to clients?
How much does it cost?
How long is the contract?
How soon will we see results?
Who will actually do the work?
More for credit score and credit repair advisers
Related work to consider.
Closest to this: leads and follow-up
Also for credit score and credit repair advisers
- SEO for credit score and credit repair advisers
- Local SEO for credit score and credit repair advisers
- Social media marketing for credit score and credit repair advisers
- Content marketing for credit score and credit repair advisers
- Buyer persona for credit score and credit repair advisers
- WhatsApp marketing for credit score and credit repair advisers
Or start from the overview: sales and marketing for credit score and credit repair advisers.
Your next practical step
Tell us what you are trying to grow, and we will read it before we call.
Eight short steps, mostly taps. Skip anything you would rather answer on the call.