Credit score and credit repair advisers · Buyer persona
Know who is asking, what just happened to them and what they fear before they call.
A buyer persona for a credit adviser is a short written picture of the person who seeks help, built from real calls rather than guesses. GullySales drafts the cards with you, marks every line as illustrative, and shows how to check each against your own clients.
Scope, fee, reporting and term are agreed in writing after we have read your brief and spoken to you.
What buyer persona means
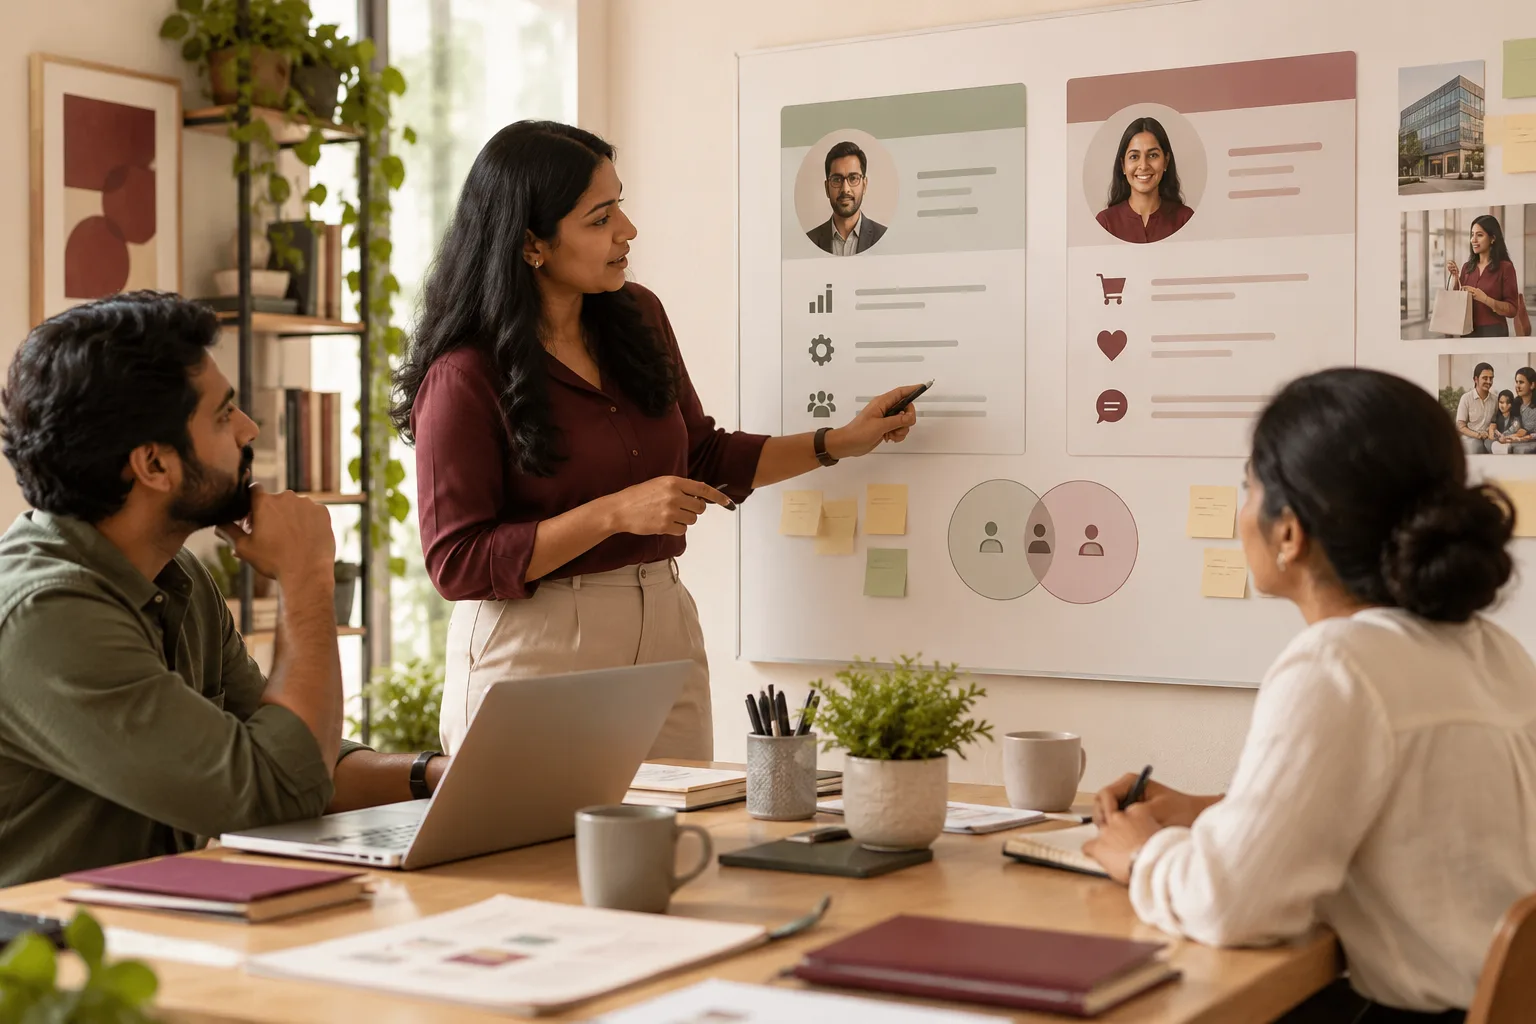
A buyer persona is a plain description of the kind of customer who actually buys from you. It includes what they search, what worries them and who else they ask before deciding. GullySales builds this from real enquiries and past sales rather than a generic template, then uses it to write every page and advert.
Also for credit score and credit repair advisers
- Digital marketing for credit score and credit repair advisers
- Lead generation for credit score and credit repair advisers
- SEO for credit score and credit repair advisers
- Local SEO for credit score and credit repair advisers
- Social media marketing for credit score and credit repair advisers
- Content marketing for credit score and credit repair advisers
- CRM for credit score and credit repair advisers
- Follow-up systems for credit score and credit repair advisers
Sales and marketing for credit score and credit repair advisers, the overview.
Last updated 14 Nov 2026. Rules for this trade differ by state and professional body, and they change. We describe restrictions in general terms, so check the current position with your own council or adviser before you publish anything.
For credit score and credit repair advisers
Where it usually goes wrong, and what we would do.
“One buyer for a varied crowd”
A salaried applicant refused a home loan, a trader refused an overdraft and an NRI with a thin file are not the same caller. A single description makes the pages and scripts blur.
“The buyer is not the only decider”
A spouse, a parent or a business partner may sit in on the decision. Pages and calls that speak only to the applicant miss the person who says yes.
“Fear is the real brief”
The stated question is about a score. The actual worry is about being refused again or being cheated. A persona that records the worry guides the first sentence of the call.
“Personas copied from other advisers”
Cards taken from a global marketing site describe people in other countries. A card is only useful when its lines are checked against your own clients.
What we do
What we deliver for credit score and credit repair advisers.
The work available for this need. We agree the deliverables and responsibilities for your engagement in writing.
A persona card for each main buyer
A card for a salaried applicant, a small proprietor and a returning NRI, each labelled illustrative and checked against your own recent clients.
Result: Your team shares a picture of each caller.
A list of who else decides
A note for each persona on the family member or partner who joins the conversation and what that person needs to hear.
Result: Calls speak to both the applicant and the second voice.
A worry-to-first-sentence guide
For each persona, the worry heard on the first call and the opening line that answers it without a promise.
Result: Callers hear that their worry is understood.
A check method against real clients
A short set of questions to ask recent clients, with consent, to confirm or correct each line of the card.
Result: Each card is tested before it guides a page.
A use guide for pages and calls
A one-page note on which card decides the page title, the call opening and the referral note.
Result: The cards change what your team says.
How the result is measured
- Enquiry match to persona
- Conversion rate by persona
- Content aligned to persona
Recorded as a baseline before work starts, so every later report has an honest comparison.
A persona card for this buyer
A persona card for a salaried applicant refused a home loan, illustrative until checked.
Each line is an illustrative answer for this trade. Check it against your own clients before using it.
- Who they are
- A salaried employee in a city such as Bengaluru or Hyderabad, with one or two loans running and a new application that a lender declined.
- What starts the search
- The lender's refusal or a higher rate quote than expected. The search happens the same evening, on a phone, in English or a home language.
- What worries them
- That the report holds an entry they do not understand, that it is a mistake, and that an adviser will promise something and disappear.
- What they compare you with
- Pages that guarantee a score, a friend's advice and the lender's own explanation. Honesty about limits is the comparison point.
- Who else decides
- A spouse who co-signs or a parent who guarantees. That person asks how the adviser handles documents and what the family is committing to.
- What makes them say yes
- A calm explanation of their own report during the first call, a clear list of what to bring and a plain statement of what is not in anyone's control.
Who it is for
This is written for these credit score and credit repair advisers.
- Individual advisers who work with salaried applicants after a home or car loan decline
- Small business credit advisers helping proprietors with working capital and overdraft files
- Advisers focused on settled and written-off accounts and how lenders read them
- Report review services that explain the bureau report and mark errors for dispute
- Loan and DSA-linked advisers who prepare an applicant before a fresh application
- Advisers serving NRIs and returning residents with a thin or old Indian credit history
- Financial coaching practices that add credit education to budgeting and debt plans
- Small firms with a few advisers working across a city or online across states
Before you decide
When this may not be the right fit.
- You have served very few clients so far, so a card would be a guess without calls to check it against.
- You want a persona to justify score promises in your advertising, which the card cannot support.
- Your team does not yet record why clients come, so the cards would have no record to be tested against.
Before you decide
Agree the work. Know how to judge it.
Buyer persona for credit score and credit repair advisers: use these checks to prepare, choose the scope, and review what changes.
Bring the right evidence
Write the decision the research must support, such as entering a market or choosing a buyer group. Separate what you know from sales records from what the team currently assumes.
Make the scope clear
Agree which buyers to speak to, which sources to review, and what access you can provide. Include lost enquiries and people who chose another supplier, where they are willing to take part.
Check the work in use
Look for source dates, sample limitations, and evidence that disagrees with the preferred answer. A recommendation should show how it follows from the findings.
Know when to change course
Do not treat a few positive conversations as proof of demand. Test the proposed offer with an actual buying decision before committing to a wider launch.
These are discussion points, not a fixed package. GullySales confirms the deliverables, responsibilities, fee, and term in writing after reading your brief and speaking with you.
Before we start
What to have ready before the work starts.
The records, access and decisions this work needs from credit score and credit repair advisers. Anything missing is noted in the written scope, with who will supply it.
- A short note on recent clients
- Bring a handful of recent cases described in general terms, with names removed. They show the situations. If you have no notes, the adviser's memory is the source and we mark the cards accordingly. Include one case where the person did not become a client, and why.
- Time to test the cards with clients
- A card is only a guess until a few clients confirm it. Block time to ask. Tell us if you cannot ask anyone, and we label every card as unconfirmed. Tell us which clients are comfortable being asked and which are not.
- A list of the main buyers you serve
- Say whether you serve salaried applicants, proprietors, NRIs or all. Describing everyone makes each card thin. We write cards for the groups you choose. Note any group, such as returning residents, whom you wish to attract more.
- Rules on handling client details
- Decide what client information can be used even in anonymised form. Check with your own adviser. We keep the cards free of anything that could identify a person. Mention if a lender or partner has restricted what you may share.
- Notes on who calls on behalf of someone
- Bring what you know about relatives or partners who call for the borrower. They change the persona. If you have none, we begin with the borrower alone.
How it works
How the buyer persona work runs
The work itself, in order. How an engagement starts, from your brief to a written scope, is set out on our method page.
- 1
Pick five recent clients from the register
With your agreement, we pick a handful of recent clients from different situations: a declined home loan, a small proprietor, an NRI with a thin file. You tell us who to avoid. We use only what you already know of them, with names removed. For each, we note the first thing they asked on the call, which is not always what they needed.
- 2
Write the first card from your memory of calls
We sit with the adviser and write one card for each main buyer: what just happened, what they fear, what they have tried and what they ask first. Every line is marked illustrative until checked. The card ends with the question the adviser should ask first, to find out which buyer is on the line.
- 3
Note who else decides
For each card we list who else has a say: a spouse, a parent, a business partner, a loan officer. You correct it from experience. This changes the pages and what the adviser says on a call. A household buyer has a second voice and a business owner a banker; we mark each.
- 4
Check each card against real clients
We give you a short method for testing a card against clients, such as asking three whether the first line fits them. You do the asking and tell us the result. Cards that do not fit are changed or dropped. Cards confirmed by fewer than a couple of clients are marked as unconfirmed in the sheet.
- 5
Turn worries into first sentences
For each worry we write the opening sentence of a page or a call, in plain words. You read them aloud to see whether they sound like a calm adviser. Those that sound like a sales line are rewritten. We also write the sentence the adviser would say to calm the fear, so page and call match.
- 6
Compare enquiries after the cards are used
After pages and calls follow the cards, we compare the enquiries and the consultations booked with the earlier record. You decide which card needs rewriting. Cards that never match a caller are retired.
Where this fits
Three pieces of sales work, in this order.
This work sits inside sales process design, at stage 0, foundation. The audit comes before it, and sales management keeps it running.
Step 1
Sales audit
Find where deals are being lost and what to fix first.
Start here if you cannot say where orders are lost.
Step 2 · you are here
Sales process design
One written way to sell, from first enquiry to repeat order.
Start here if every salesperson sells differently.
Step 3
Sales management
A target, a review routine and someone who owns the number.
Start here if the team has targets and no routine.
FAQ
Questions owners ask before they call.
Not here? More answers, or ask on WhatsApp.
How big should the persona set be?
How can recent clients confirm or correct a persona?
Do we use the persona for ads and for staff?
Is a business owner different from a household buyer?
Can we put real names on the cards?
How do we know the cards are right?
How much does it cost?
How long is the contract?
How soon will we see results?
Who will actually do the work?
More for credit score and credit repair advisers
Related work to consider.
Closest to this: strategy and research
Also for credit score and credit repair advisers
- Lead generation for credit score and credit repair advisers
- SEO for credit score and credit repair advisers
- Local SEO for credit score and credit repair advisers
- Social media marketing for credit score and credit repair advisers
- Content marketing for credit score and credit repair advisers
- CRM for credit score and credit repair advisers
Or start from the overview: sales and marketing for credit score and credit repair advisers.
Your next practical step
Tell us what you are trying to grow, and we will read it before we call.
Eight short steps, mostly taps. Skip anything you would rather answer on the call.