Gold loan and NBFC lenders · Strategic account management
Check the fit before choosing strategic account management.
This service assumes an organisational buyer or an account relationship with identifiable decision-makers. That buying model is not established by the industry profile. Confirm an appropriate business-account scope before treating individual enquiries as enterprise opportunities.
Scope, fee, reporting and term are agreed in writing after we have read your brief and spoken to you.
Specialist scope
Confirm the operating model before applying this service to gold loan and nbfc lenders.
This service assumes an organisational buyer or an account relationship with identifiable decision-makers. That buying model is not established by the industry profile. Confirm an appropriate business-account scope before treating individual enquiries as enterprise opportunities.
Individual financial advice, suitability, and approval decisions remain with the authorised team. Targets and marketing activity do not replace those assessments.
Consider the underlying work instead.
The context for Gold loan and NBFC lenders
Start with the decisions in your own enquiry records.
Read the accepted scope and the subsequent service record. Separate adoption, complaints, repeat requirements, and renewal decisions before selecting a follow-up programme.
How people choose in this industry
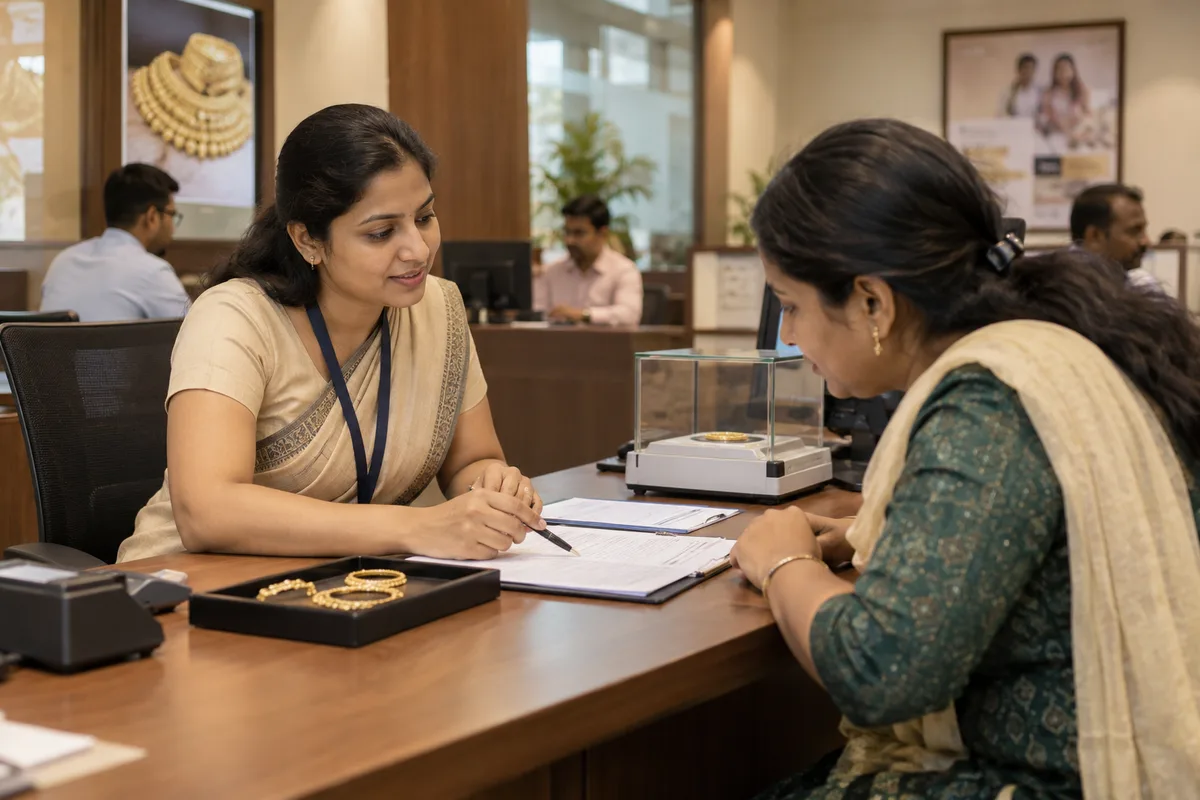
A gold loan borrower chooses on trust, distance and the amount offered, in roughly that order. Most walk in. Some ask a relative or the jeweller who sold them the ornaments, and more now type gold loan near me and ring the first branch on the map with a number that answers. Before handing over jewellery they want to know it will be safe, what it will fetch and whether anyone will embarrass them.
Discretion matters more than lenders admit. Some borrowers, women especially, are pledging family jewellery that others at home need not hear about. A branch with a private counter, staff who never discuss a loan in front of the queue, and reminders that do not spell out the amount on a shared phone wins that borrower and keeps the account.
Vehicle and small business loans from an NBFC are chosen more slowly. A kirana owner or a two-wheeler buyer weighs the dealer's financier, a bank and you, asks how many documents and how many visits, and goes with whoever explains the EMI and the charges plainly and still answers the phone after the first visit.
The decision before implementation
Resolve an outstanding delivery issue before asking for advocacy or another purchase. Respect contact preferences.
Existing industry priorities to review
- Gold loans for farmers before sowing
- Gold loans for traders' working capital
- Gold loan takeover from another lender
- Top-up loans within the loan-to-value limit when the gold price rises
- Doorstep gold loans at the borrower's home
These describe the industry's wider priorities. The written scope identifies which this service will address.
Why the scope is different
Use a service whose responsibilities match your operation.
The specialist programme has its own team, records, and approval requirements. Its name does not establish that the same engagement applies in another industry.
- Manufacturers whose largest OEM buyers account for a substantial share of invoices
- Suppliers dependent on a distributor for access to a state or sector
- Teams where one account manager holds every important customer contact
- Owners who meet senior people at major accounts only during complaints
- Professional firms or suppliers facing formal vendor reviews and rate-contract decisions
FAQ
Questions owners ask before they call.
Not here? More answers, or ask on WhatsApp.
How is strategic account management scoped for gold loan and nbfc lenders?
What should we confirm before considering this service?
What if this programme does not fit our operation?
Continue your review
Compare the service scope and the related work.
The scope, responsibilities, fee, reporting frequency, and term are agreed in writing after the requirements brief and conversation. Tell us what you need.
Your brief
Tell us what you need, and we will read it before we call.
Eight short steps about your business, what you want and who decides. Most questions are a tap, and you can skip any you would rather answer on the call.