Gold loan and NBFC lenders · Financial services
Last season's gold loan borrower pledged at the branch across the road this time.
It is the second week of June in a taluk town. A farmer walks in with two bangles and the family chain, because the seed and fertiliser bills fall due before the rain and the school reopens the same week.
Scope, fee, reporting and term are agreed in writing after we have read your brief and spoken to you.
In one paragraph
Gold loan and NBFC marketing gets a household or a small trader to your branch, and not the one across the road, on the day they need cash against jewellery or a loan for the shop. Sales is what the branch does next: the appraisal explained, the scheme made plain and the call before the due date. GullySales sets up both inside your lending rules.
The farmer did not search for you. The farmer passed three gold loan boards on the bus-stand road and chose the branch where a cousin was treated decently and the per-gram amount was written where it could be read.
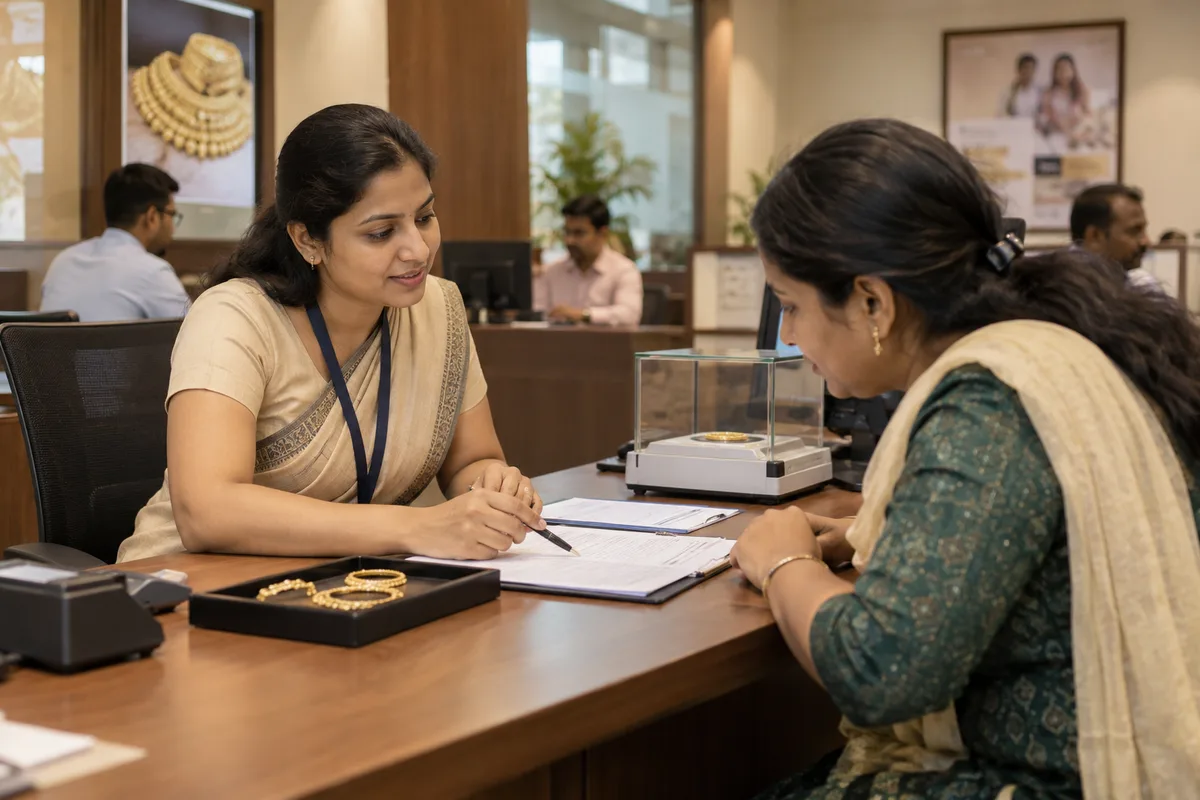
What happens at the counter decides whether the borrower comes back. If the appraiser shows the borrower the weight and the purity reading, explains the scheme in Kannada and calls before the interest falls due, the borrower releases the gold after harvest and returns next season. If the borrower gets a pledge receipt and silence, the first reminder heard is a notice, and half the street hears about it too.
Last updated 17 Oct 2026. Rules for this trade differ by state and professional body, and they change. We describe restrictions in general terms, so check the current position with your own council or adviser before you publish anything.
How buyers decide
How gold loan and NBFC lenders are chosen.
A gold loan borrower chooses on trust, distance and the amount offered, in roughly that order. Most walk in. Some ask a relative or the jeweller who sold them the ornaments, and more now type gold loan near me and ring the first branch on the map with a number that answers. Before handing over jewellery they want to know it will be safe, what it will fetch and whether anyone will embarrass them.
Discretion matters more than lenders admit. Some borrowers, women especially, are pledging family jewellery that others at home need not hear about. A branch with a private counter, staff who never discuss a loan in front of the queue, and reminders that do not spell out the amount on a shared phone wins that borrower and keeps the account.
Vehicle and small business loans from an NBFC are chosen more slowly. A kirana owner or a two-wheeler buyer weighs the dealer's financier, a bank and you, asks how many documents and how many visits, and goes with whoever explains the EMI and the charges plainly and still answers the phone after the first visit.
The problem
What usually goes wrong for gold loan and NBFC lenders.
Common situations to check against your own enquiry records.
“Borrowers close with us and pledge somewhere else next time”
Nobody rings after a release. The customer who paid off cleanly in March walks into a competitor's branch in June because their pamphlet was the last one they saw.
“Our first reminder is the auction notice”
Interest due dates pass without a call, the loan runs overdue, and the formal notice is the first the borrower hears. The borrower pays, then tells everyone at the tea shop how they were treated.
“The branch phone rings while the appraiser is testing gold”
Two staff, a queue at the counter and a landline nobody can reach. The caller asking what their chain will fetch rings the next number on the map.
“Our Google listings send people to a branch that moved”
Branches opened, shifted and closed over the years, and the map still shows the old shutter, the old hours or a number that rings out.
“Every ad says lowest rate and instant cash”
Head office copy promises what a busy branch cannot always give, and compliance worries, rightly, about rate claims printed without the conditions behind them.
“Takeover offers pull our good borrowers away”
A rival offers to take over the loan on a better-sounding scheme, and the branch learns about it only when the borrower asks for the closure amount.
What we do
What we do for gold loan and NBFC lenders.
The work available for gold loan and NBFC lenders, and the intended result of each part. Your written scope confirms the deliverables you buy.
Branch listings that match the branch
Every branch on Google Maps with the right address, staffed hours, a landline and a mobile someone answers, with duplicates closed and shifted branches moved.
Result: A borrower who searches near the bus stand finds the branch that is open.
A due-date reminder before any notice
Calls and messages to borrowers ahead of the interest date and the loan maturity, in their language, setting out how to pay, renew or close.
Result: The auction notice stops being the first contact.
A release call that brings the borrower back
A call after every closure asking how it went and noting when the borrower expects to need money again, such as sowing or school fees.
Result: Last season's borrower hears from you before a rival's pamphlet reaches them.
Advertising wording compliance has signed
Pamphlet, hoarding, Maps and search ad copy with rates, charges and conditions shown the way your compliance officer requires, and no lowest-rate or instant promises.
Result: Campaigns go out without a rewrite at head office.
A scheme sheet for the counter
One page per scheme in the local language, setting out how interest is charged, what part payment does and what happens at closure, for staff to walk through with the borrower.
Result: Every branch explains the loan the same way.
Enquiries counted by branch and source
Calls, walk-ins, WhatsApp messages and Maps clicks recorded per branch with their source, against the baseline taken before the work starts.
Result: You can see which branch and which channel brings pledges.
How the result is measured
- New pledges by branch and source
- Branch calls answered and missed
- Due dates reached with a reminder call
- Loans renewed or closed before overdue
- Closed borrowers who pledged again
- Takeover enquiries won and lost
Recorded as a baseline before work starts, so every later report has an honest comparison.
Every service, written for gold loan and NBFC lenders
Each has its own page: what it involves for gold loan and NBFC lenders, what you get, and what it is measured on.
- SEOWrite the page a borrower reads before carrying jewellery into a branch.
- Local SEOWhen someone nearby searches gold loan near me, the open branch should be yours.
- PPC adsPay for the borrower ready to pledge today, not the one checking the gold price.
- Digital marketingFix the branch listings and the reminder calls before buying a single ad.
- WhatsApp marketingRemind the borrower about the due date without telling the whole family about the loan.
- Reputation managementOne review about an auction notice can outweigh years of quiet, honest lending.
- Lead generationBorrowers reach you at the counter, the landline and the dealer, so record all three.
- Follow-up systemsThe borrower said they would bring the gold tomorrow, never came, and nobody called.
- Customer retentionA borrower who released the gold cleanly is the easiest pledge to win back.
- Sales trainingTrain the appraiser to explain the loan as well as weigh the gold.
- Social mediaPost what a borrower in your taluk wants to know, not a rate nobody can honour.
- Content marketingAnswer the question the borrower is too embarrassed to ask across the counter.
- Buyer personasDecide who is standing at the counter before deciding what to say to them.
- CRMYour loan system remembers the loans; a CRM remembers the people.
- WebsiteA borrower on a cheap phone should find the nearest branch in one tap.
Worth a page and a campaign of their own
Gold loans for farmers before sowing · Gold loans for traders' working capital · Gold loan takeover from another lender · Top-up loans within the loan-to-value limit when the gold price rises · Doorstep gold loans at the borrower's home · Two-wheeler loans through dealers · Loans against property for shop owners · Small business loans for kirana and retail
Priority campaigns
Campaigns for what gold loan and NBFC lenders most want to sell.
Each one planned around when your buyers decide, and measured against the baseline.
Sowing season gold loan campaign
Village wall paintings, auto announcements and branch boards in the weeks before the rains, with the documents a farmer needs and the branch hours on shandy day.
Result: Farmers find the branch before the seed bill falls due.
School reopening campaign
A plain message to past borrowers and the neighbourhood about gold loans in fee season, with the scheme explained and no rate claim beyond what compliance approves.
Result: Parents short of fees come to a lender they already know.
After-harvest release and renewal drive
Calls to borrowers whose loans fall due after harvest, offering release, part payment or renewal, so the ornaments come home for the wedding season.
Result: Loans close or renew in good order, and the borrower returns.
Takeover campaign for other lenders' borrowers
A plain explanation of how a gold loan takeover works, what the borrower carries and what moving costs, run on Maps, WhatsApp and the branch board.
Result: Borrowers unhappy elsewhere know how to move to you.
Dealer-point campaign for two-wheeler loans
A desk or standee at partner showrooms in the festival months, with a document checklist and a named field officer who rings the buyer back the same day.
Result: Showroom buyers leave with your loan, not the dealer's default financier.
Beyond search
Where we reach buyers of gold loan and NBFC lenders, beyond Google.
Search matters, but it is rarely the only way this industry's buyers find a supplier.
Jewellers and goldsmiths in the bazaar
A customer who comes to sell old gold sometimes only needs cash for a few months. A jeweller who knows your branch can point them to a loan instead, and the arrangement stays within your rules on referrals.
Seed, fertiliser and agri input shops
The input dealer sees every farmer before sowing. A board on the dealer's wall and your branch number on the bill book reach the right person in the right week.
Self-help groups and their federations
Women's groups meet on a fixed day and talk about money openly. A talk on how a gold loan differs from a group loan, with nothing sold, earns an invitation back.
Two-wheeler and used vehicle dealers
The showroom decides the financier for most buyers at the counter. A dealer who trusts your field officer to turn a file round puts your name forward.
APMC yards and traders' associations
Wholesale markets are full of traders who need cash for a few weeks while stock moves. A stall on a trade day and a contact at the association office reach them.
A practical starting point · Gold loan and NBFC lenders
Start with one buying journey.
Use a real enquiry to find the first useful change. You do not need to buy every service listed on this page.
- The record to review
- Use anonymised enquiry stages and response records for the first review. Keep account details, identity documents, and individual financial circumstances out of a marketing brief.
- The buyer's question
- Check whether the public page explains the service and how to speak to an authorised person. Have the firm's own compliance adviser review claims before publication.
- The handover to agree
- Separate marketing responses from advice or suitability decisions. Only the authorised team should make commitments about products, terms, or individual outcomes.
Who it is for
This is written for these gold loan and NBFC lenders.
- Gold loan NBFCs with a regional branch network
- Single-branch and family-run gold loan companies
- Licensed pawnbrokers and money lenders
- Nidhi companies lending to their members
- Credit cooperatives and souharda societies offering jewel loans
- Two-wheeler and used vehicle finance NBFCs
- MSME and small business loan NBFCs
- Microfinance lenders working with women's groups
Not for
It is not the right fit if.
- You want a guaranteed Google ranking or a guaranteed number of leads. Nobody honest can promise either.
- You need enquiries by next week and have nobody to answer them.
- You want posts and reach reported, not enquiries and orders.
How it works
How the work runs for gold loan and NBFC lenders
The work itself, in order. How an engagement starts, from your brief to a written scope, is set out on our method page.
- 1
Assess
In the first conversation we ask how last season's pledges arrived, by branch and by source, and look at how many due dates passed without a call and how many closed borrowers never returned.
- 2
Fix the branch front door
Maps listings, phone numbers that someone answers, a rate board and a scheme sheet the counter staff use, branch by branch.
- 3
Set the reminder and release routine
Due-date calls, renewal offers and the after-closure call written down, with who makes each one and what gets recorded.
- 4
Run the seasons
Campaigns timed to sowing, school fees, harvest and the festival months, with wording your compliance officer approved before the season starts.
- 5
Measure by branch
Enquiries, new pledges, renewals and returning borrowers counted per branch against the baseline, so the branch that needs help is visible to head office.
Where this fits
Three pieces of sales work, in this order.
GullySales builds every engagement from three pieces of sales work. This page is not one of them, but the same three steps apply to the business behind it.
Step 1
Sales audit
Find where deals are being lost and what to fix first.
Start here if you cannot say where orders are lost.
Step 2
Sales process design
One written way to sell, from first enquiry to repeat order.
Start here if every salesperson sells differently.
Step 3
Sales management
A target, a review routine and someone who owns the number.
Start here if the team has targets and no routine.
FAQ
Questions gold loan and NBFC lenders ask before they call.
Not here? More answers, or ask on WhatsApp.
Can we advertise our gold loan amount per gram?
Will your team speak to our borrowers about their loans?
Do you work with single-branch lenders as well as networks?
Is it safe to send WhatsApp reminders about gold loans?
Our branches are spread across two states. How does the work run?
How much does it cost?
How long is the contract?
How soon will we see results?
Who will actually do the work?
What do you need from us?
Notes for owners
Read more about gold loan and NBFC lenders.
- Why gold loan borrowers pledge elsewhere after they closeA closed gold loan is the cheapest next enquiry a branch gets. What to record on release day, when to call again, and how to answer a takeover offer.
- How buyers decide which lender or adviser to trustPeople choosing a bank, lender, adviser or insurer start with a name someone gave them, then check you before calling. See what they look for.
- Explaining financial jargon on your website so a first-time customer keeps readingWrite plain-language finance pages: define the term, show a worked example and say who the product is not for, so first-time customers keep reading.
Part of Financial services. See the other industries in the sector.
Your next practical step
Tell us what you are trying to grow, and we will read it before we call.
Eight short steps, mostly taps. Skip anything you would rather answer on the call.