Gold loan and NBFC lenders · Reputation management
One review about an auction notice can outweigh years of quiet, honest lending.
Reputation management for a gold loan or NBFC lender is how branches handle what borrowers say about them on Google, JustDial and in the neighbourhood: the valuation, the wait, the recovery calls and the auction. GullySales sets up monitoring and reply wording that never discloses a loan, and traces each complaint to a fix inside the branch.
Scope, fee, reporting and term are agreed in writing after we have read your brief and spoken to you.
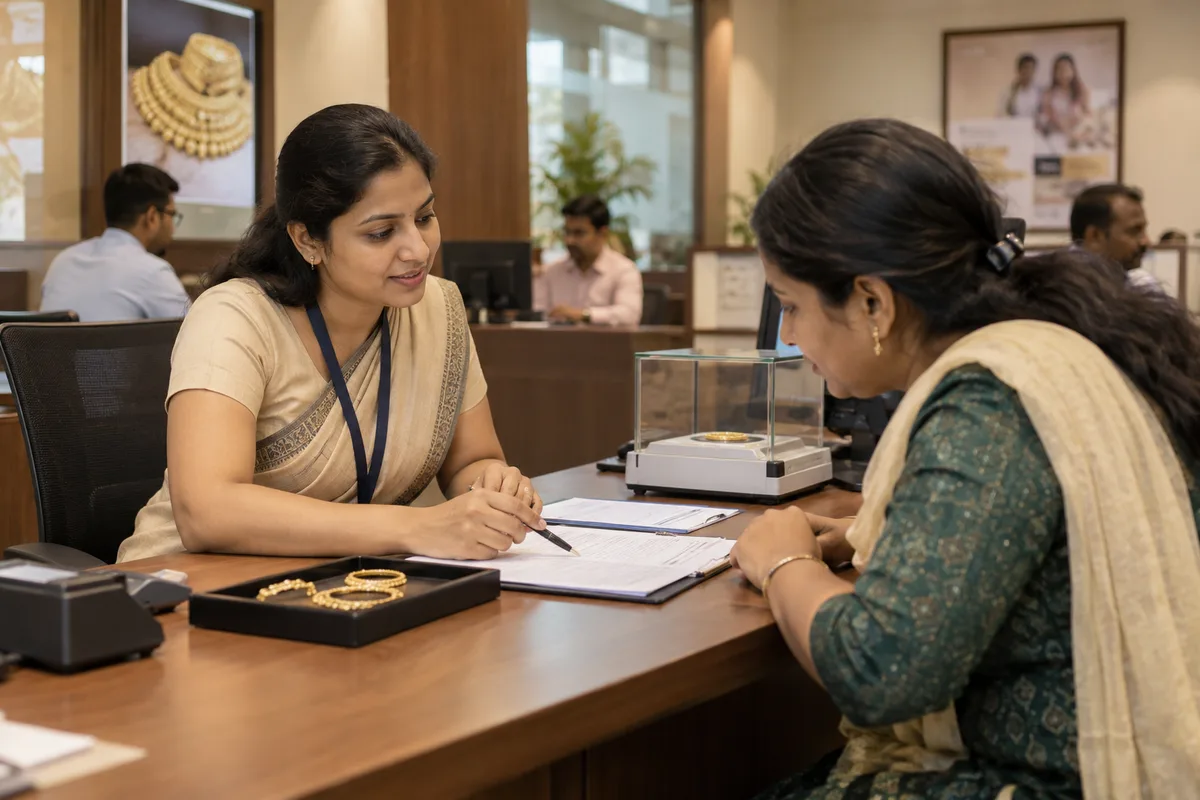
What reputation management means
Reputation management is watching what is said about your business across Google, social media and review sites, and responding to it before it changes a buyer's mind. GullySales monitors mentions, drafts responses to negative reviews and flags recurring complaints back to your team.
Also for gold loan and NBFC lenders
- SEO for gold loan and NBFC lenders
- Local SEO for gold loan and NBFC lenders
- PPC ads for gold loan and NBFC lenders
- Digital marketing for gold loan and NBFC lenders
- WhatsApp marketing for gold loan and NBFC lenders
- Lead generation for gold loan and NBFC lenders
- Follow-up systems for gold loan and NBFC lenders
- Customer retention for gold loan and NBFC lenders
Sales and marketing for gold loan and NBFC lenders, the overview.
Last updated 17 Oct 2026. Rules for this trade differ by state and professional body, and they change. We describe restrictions in general terms, so check the current position with your own council or adviser before you publish anything.
For gold loan and NBFC lenders
Where it usually goes wrong, and what we would do.
“Recovery conduct ends up in public”
A borrower who felt harassed over an overdue loan writes about it and names the branch, sometimes the caller. Lenders have rules on recovery conduct for this reason, and the reply has to show you take it seriously.
“The valuation is the most common grievance”
The borrower expected more for the chain than the branch offered. Without a plain explanation of purity and weight net of stones, they conclude they were cheated.
“A careless reply discloses a loan”
Confirming in public that the reviewer pledged gold with you, or mentioning an amount, breaches the borrower's privacy and embarrasses them. The reply says nothing about any account.
What we do
What we deliver for gold loan and NBFC lenders.
The work available for this need. We agree the deliverables and responsibilities for your engagement in writing.
Review monitoring for every branch
Google, JustDial and the main complaint sites watched for every branch, with new reviews routed to the branch manager and the regional head.
Result: A complaint is seen by someone who can act on it.
Reply wording that discloses nothing
Standing replies for praise, a valuation complaint, a long wait and a recovery complaint, approved by compliance and written in the reviewer's language.
Result: Every review gets an answer that protects the borrower's privacy.
A route from review to grievance desk
Any review describing harm or a recovery complaint copied to your grievance officer, logged and answered through the formal process.
Result: Serious complaints get the formal handling they need.
A valuation explainer shown during appraisal
One page on how weight, stones and purity affect the amount, put in front of the borrower while the appraiser works.
Result: Fewer borrowers leave feeling short-changed.
An honest review ask after a clean release
A short request when a borrower collects the ornaments and leaves happy, with no gift, staff quota or pressure, and never while a complaint is open.
Result: Recent reviews reflect ordinary good service, not only anger.
Ratings and complaint themes by branch
Ratings, recurring complaint themes and replies sent per branch, set against the baseline taken before the work starts.
Result: The branch with a conduct problem shows up early.
How the result is measured
- Average rating
- Response time to reviews
- Negative mentions resolved
Recorded as a baseline before work starts, so every later report has an honest comparison.
What to do with each review
How a gold loan branch replies to praise, valuation complaints, recovery complaints and auction reviews.
- Praise after the gold is released
- Thank the borrower without mentioning the loan, the amount or the ornaments. Pass the praise to the named staff member and note what went well.
- The amount was lower than expected
- Reply that you would be glad to explain how the valuation was done, and give the branch number. Inside, check whether the appraiser showed the weight and purity readings.
- Complaint about recovery calls
- Reply that you take conduct seriously and give the grievance contact. Inside, pull the call record, check the calls against your fair practice code and act on what you find.
- Review about an auction
- Do not discuss the account. Say you cannot talk about any customer's loan in public and invite a call. Inside, check that every reminder and notice went out as your process requires.
- Long wait in a crowded branch
- Apologise for the wait and mention the quieter hours if you know them. Inside, look at whether a second appraiser or booked slots are needed on market days.
- Review that looks fake or planted
- Check the name against your borrower records. If nothing matches, report it through the platform's process and reply once, plainly. Never post reviews of your own in return.
Who it is for
This is written for these gold loan and NBFC lenders.
- Gold loan NBFCs with a regional branch network
- Single-branch and family-run gold loan companies
- Licensed pawnbrokers and money lenders
- Nidhi companies lending to their members
- Credit cooperatives and souharda societies offering jewel loans
- Two-wheeler and used vehicle finance NBFCs
- MSME and small business loan NBFCs
- Microfinance lenders working with women's groups
Not for
It is not the right fit if.
- Complaints about auction notices are still open at branch level, so asking for reviews now would only attract more of them
- You have no named person who can reach a borrower with a grievance, so a public reply would promise a call that no one makes
Before you decide
Agree the work. Know how to judge it.
Reputation management for gold loan and NBFC lenders: use these checks to prepare, choose the scope, and review what changes.
Bring the right evidence
Collect recurring public feedback and the internal record of how the issue was handled. Separate factual corrections from genuine complaints that need a response.
Make the scope clear
Agree who checks facts, approves replies, and resolves problems outside marketing. Any request for reviews or testimonials must fit the trade's rules and the customer's permission.
Check the work in use
Read the response from the customer's point of view. It should address the issue without exposing private information or promising an outcome the team cannot provide.
Know when to change course
Do not buy or invent reviews. If the same complaint keeps returning, resolve its cause before publishing more positive material.
These are discussion points, not a fixed package. GullySales confirms the deliverables, responsibilities, fee, and term in writing after reading your brief and speaking with you.
How it works
How the reputation management work runs
The work itself, in order. How an engagement starts, from your brief to a written scope, is set out on our method page.
- 1
Coverage and responsibility agreement
After your requirements brief and conversation, we agree the names and sources in scope. You nominate the person who approves replies, with the scope, fee, and term recorded before work starts.
- 2
Baseline review and priorities
We record the search results and public mentions, then ask your team to verify disputed facts. Together, we decide which items need a reply, a correction request, or internal investigation.
- 3
Response approval
Drafts go to the agreed approver before publication. Questions about refunds, clinical care, legal claims, or named employees go to the responsible person instead of being decided by the copywriter.
- 4
Publication and correction handoff
Approved replies are published through the agreed account access or handed to your account owner. Corrections and outside requests are logged separately, with any platform or publisher decision recorded.
- 5
Open-issue review
We repeat the agreed checks and compare findings with the baseline. Unresolved matters return to the responsible person, while relevant public concerns are passed to your sales lead with approved wording.
Where this fits
Three pieces of sales work, in this order.
This work sits inside sales management. A target, a review routine and someone who owns the number.
Step 1
Sales audit
Find where deals are being lost and what to fix first.
Start here if you cannot say where orders are lost.
Step 2
Sales process design
One written way to sell, from first enquiry to repeat order.
Start here if every salesperson sells differently.
Step 3 · you are here
Sales management
A target, a review routine and someone who owns the number.
Start here if the team has targets and no routine.
FAQ
Questions owners ask before they call.
Not here? More answers, or ask on WhatsApp.
Can we ask borrowers for Google reviews?
The review is in Kannada. Should we reply in English?
A review names one of our branch staff. What do we do?
Can a negative review be taken down?
How much does it cost?
How long is the contract?
How soon will we see results?
Who will actually do the work?
What do you need from us?
What if we are not happy with the work?
From the blog
Further reading for gold loan and NBFC lenders.
 6 min read · 6 Oct 2026How buyers decide which lender or adviser to trustPeople choosing a bank, lender, adviser or insurer start with a name someone gave them, then check you before calling. See what they look for.
 5 min read · 6 Oct 2026Why gold loan borrowers pledge elsewhere after they closeA closed gold loan is the cheapest next enquiry a branch gets. What to record on release day, when to call again, and how to answer a takeover offer.
 6 min read · 21 Jun 2026Explaining financial jargon on your website so a first-time customer keeps readingWrite plain-language finance pages: define the term, show a worked example and say who the product is not for, so first-time customers keep reading.
More for gold loan and NBFC lenders
Related work to consider.
Or start from the overview: sales and marketing for gold loan and NBFC lenders.
Your next practical step
Tell us what you are trying to grow, and we will read it before we call.
Eight short steps, mostly taps. Skip anything you would rather answer on the call.