Gold loan and NBFC lenders · Lead generation
Borrowers reach you at the counter, the landline and the dealer, so record all three.
Lead generation for a gold loan or NBFC lender brings enquiries from walk-ins, calls, the map, dealers, jewellers and village field visits, and records each one with its source. GullySales sets up the sources that suit your branches and the record that shows which ones end in a pledge or a disbursed loan.
Scope, fee, reporting and term are agreed in writing after we have read your brief and spoken to you.
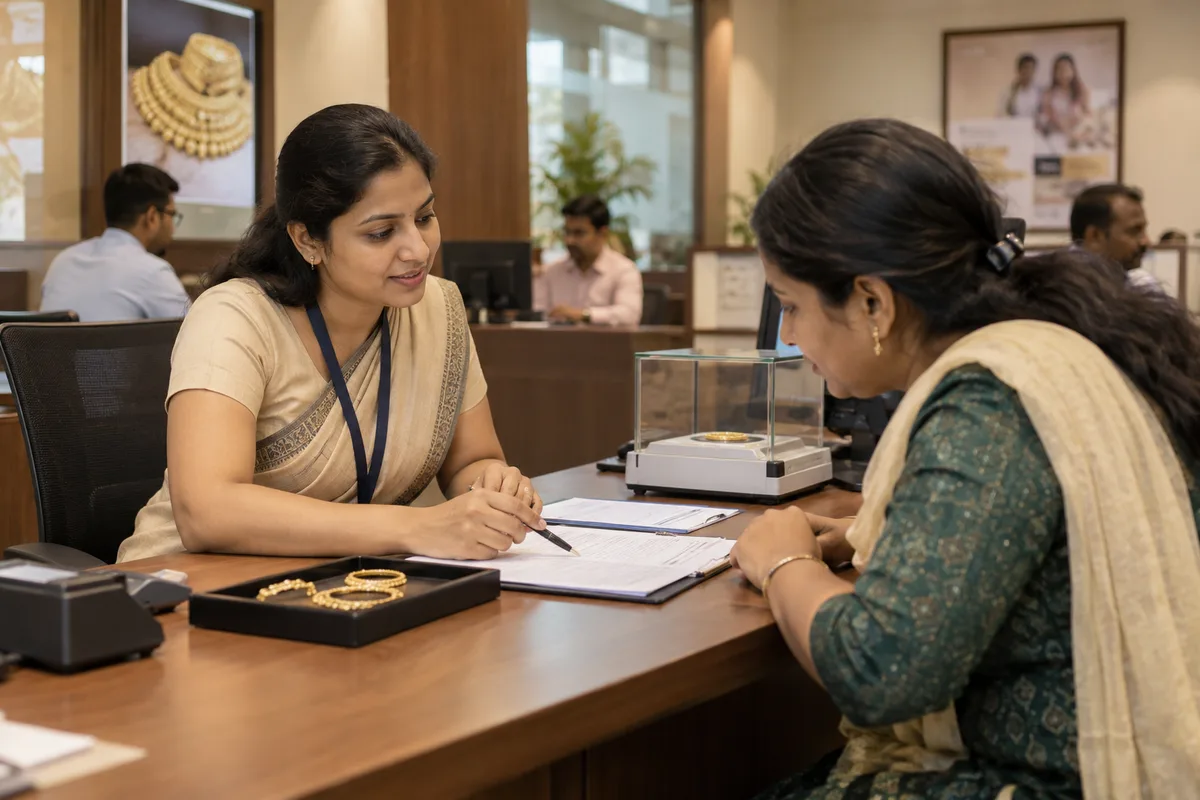
What lead generation means
Lead generation is the combined work of every channel that brings in a new enquiry, whether from search, adverts, referrals or a stall at an exhibition. GullySales runs these channels together and reports the number of enquiries each one produced, not the activity behind it.
Also for gold loan and NBFC lenders
- Follow-up systems for gold loan and NBFC lenders
- CRM for gold loan and NBFC lenders
- SEO for gold loan and NBFC lenders
- Local SEO for gold loan and NBFC lenders
- PPC ads for gold loan and NBFC lenders
- Digital marketing for gold loan and NBFC lenders
- WhatsApp marketing for gold loan and NBFC lenders
- Reputation management for gold loan and NBFC lenders
Sales and marketing for gold loan and NBFC lenders, the overview.
Last updated 17 Oct 2026. Rules for this trade differ by state and professional body, and they change. We describe restrictions in general terms, so check the current position with your own council or adviser before you publish anything.
For gold loan and NBFC lenders
Where it usually goes wrong, and what we would do.
“Walk-ins are never written down”
A borrower asks the rate, hears the amount for the chain and leaves. Nobody notes a name, so there is no lead to follow and no reason recorded for the loss.
“Bought loan leads rarely hold gold borrowers”
Personal loan lead lists sell the same salaried applicant to several lenders. A gold loan borrower is local, in a hurry, and does not fill in comparison forms.
“Field officers carry leads in their heads”
The officer who visits villages and dealers knows who needs a loan after harvest. Unless it is in the system, that knowledge leaves when the officer does.
What we do
What we deliver for gold loan and NBFC lenders.
The work available for this need. We agree the deliverables and responsibilities for your engagement in writing.
A walk-in enquiry slip
A half-page slip at the counter for anyone who asks but does not pledge: name, mobile, product, the reason they did not proceed and consent to call.
Result: Walk-outs become a list somebody can ring.
Source recorded on every new loan
A field on the loan entry, picked from a short list: walk-in, Maps, call, WhatsApp, dealer, jeweller, field visit, referral or ad.
Result: Head office can see which sources end in pledges.
A partner enquiry form for dealers and shops
A simple WhatsApp or paper form for two-wheeler dealers and agri input shops to pass on a buyer's name, need and consent to your branch.
Result: Partner leads arrive with what the branch needs to call.
Field visits planned around shandy days
Visits timed to markets, SHG meetings and harvest, with every conversation logged as a lead when the person agrees.
Result: Field work produces names, not just goodwill.
A rule for duplicate enquiries
One owner per borrower when the same person rings two branches or arrives through a dealer and a call, decided by first contact.
Result: Branches stop arguing over the same borrower.
Enquiries and loans by source
Enquiries, pledges and disbursed loans by source and branch, against the baseline taken before the work starts.
Result: Staff time goes to the sources that lend.
How the result is measured
- Enquiries generated
- Cost per enquiry
- Enquiries by source
Recorded as a baseline before work starts, so every later report has an honest comparison.
Where enquiries come from
Where a gold loan or NBFC branch hears from borrowers, and what to note for each.
- Walk-in at the counter
- Note the name, mobile, product and what was offered, even when the borrower leaves. Ask why they did not go ahead and write the answer as they said it.
- Call to the branch landline or from Maps
- Record the caller, what they asked about and the branch they can reach. Give the branch hours and the documents to carry before the call ends.
- Two-wheeler or used vehicle dealer
- Log the dealer, the model, the buyer's income type and the down payment discussed. Ring the buyer the day the name arrives and tell the dealer you did.
- Jeweller or goldsmith introduction
- Record the jeweller, and whether the customer meant to sell or only needed cash for a while. Keep the arrangement inside your rules on referrals.
- Field officer at a shandy or SHG meeting
- Write down the village, the meeting and the need, such as sowing money or stock for a shop. Take consent to call before taking the number.
- Takeover enquiry from another lender's borrower
- Note the current lender, the release amount the borrower mentions and the scheme they want. Explain the steps and what to carry, without running down the other lender.
Who it is for
This is written for these gold loan and NBFC lenders.
- Gold loan NBFCs with a regional branch network
- Single-branch and family-run gold loan companies
- Licensed pawnbrokers and money lenders
- Nidhi companies lending to their members
- Credit cooperatives and souharda societies offering jewel loans
- Two-wheeler and used vehicle finance NBFCs
- MSME and small business loan NBFCs
- Microfinance lenders working with women's groups
Not for
It is not the right fit if.
- Branch staff cannot call a new enquiry back on the day, so the names you gather would go cold in the register
- You have no single place where a walk-in, a call and a dealer introduction are written down, so leads would be counted twice or lost
Before you decide
Agree the work. Know how to judge it.
Lead generation for gold loan and NBFC lenders: use these checks to prepare, choose the scope, and review what changes.
Bring the right evidence
Define the organisations or buyers you can serve and the reasons they would consider a conversation. Bring examples of accepted and rejected prospects so the selection rule is visible.
Make the scope clear
Agree the research sources, contact approach, qualification rules, and handover. Clarify which meetings count as accepted and what happens to replies that are not ready to buy.
Check the work in use
Review why a prospect was selected and what was learned from the response. Count held, relevant conversations separately from contacts found, messages sent, or meetings booked.
Know when to change course
If the same objection appears repeatedly, adjust the offer or buyer group before increasing outreach. Respect a request to stop contact and keep the exclusion in the record.
These are discussion points, not a fixed package. GullySales confirms the deliverables, responsibilities, fee, and term in writing after reading your brief and speaking with you.
How it works
How the lead generation work runs
The work itself, in order. How an engagement starts, from your brief to a written scope, is set out on our method page.
- 1
Requirements and capacity decision
Send the requirements brief, then discuss your offer and available sales capacity with us. You receive the scope, fee, and term in writing before committing to the work.
- 2
Source review and baseline approval
We review available enquiry records and channel dashboards. You confirm the starting figures for enquiries by source, reply time, conversion, and cost per order, including gaps in the records.
- 3
Offer and capture approval
Your sales lead approves the audience and the questions needed before a call. Page copy and contact-use wording go through your internal review before publication.
- 4
Test enquiry and sales handoff
We test the agreed routes from submission to the shared record and first reply. The person responsible for sales checks that the record contains enough information to act.
- 5
Launch and source decisions
Traffic starts on the approved channels. We compare enquiry quality with the baseline and use your sales outcomes to decide which sources need changes or less spend.
Where this fits
Three pieces of sales work, in this order.
This work sits inside sales process design, at stage 1, prospecting and lead generation. The audit comes before it, and sales management keeps it running.
Step 1
Sales audit
Find where deals are being lost and what to fix first.
Start here if you cannot say where orders are lost.
Step 2 · you are here
Sales process design
One written way to sell, from first enquiry to repeat order.
Start here if every salesperson sells differently.
Step 3
Sales management
A target, a review routine and someone who owns the number.
Start here if the team has targets and no routine.
FAQ
Questions owners ask before they call.
Not here? More answers, or ask on WhatsApp.
Should we buy loan leads from aggregator sites?
What counts as a qualified gold loan enquiry?
Are village visits and market-day stalls still worth doing?
Can jewellers send customers to us?
How much does it cost?
How long is the contract?
How soon will we see results?
Who will actually do the work?
What do you need from us?
What if we are not happy with the work?
From the blog
Further reading for gold loan and NBFC lenders.
 5 min read · 6 Oct 2026Why gold loan borrowers pledge elsewhere after they closeA closed gold loan is the cheapest next enquiry a branch gets. What to record on release day, when to call again, and how to answer a takeover offer.
 6 min read · 6 Oct 2026How buyers decide which lender or adviser to trustPeople choosing a bank, lender, adviser or insurer start with a name someone gave them, then check you before calling. See what they look for.
 6 min read · 21 Jun 2026Explaining financial jargon on your website so a first-time customer keeps readingWrite plain-language finance pages: define the term, show a worked example and say who the product is not for, so first-time customers keep reading.
More for gold loan and NBFC lenders
Related work to consider.
Closest to this: leads and follow-up
Also for gold loan and NBFC lenders
Or start from the overview: sales and marketing for gold loan and NBFC lenders.
Your next practical step
Tell us what you are trying to grow, and we will read it before we call.
Eight short steps, mostly taps. Skip anything you would rather answer on the call.