Gold loan and NBFC lenders · CRM
Your loan system remembers the loans; a CRM remembers the people.
A CRM for a gold loan or NBFC lender holds the borrower, the enquiry, the call history and the next step in one place beside the loan system that holds the accounts. GullySales helps you choose a tool you can afford, set up the fields and the routine, and train branches to use it.
Scope, fee, reporting and term are agreed in writing after we have read your brief and spoken to you.
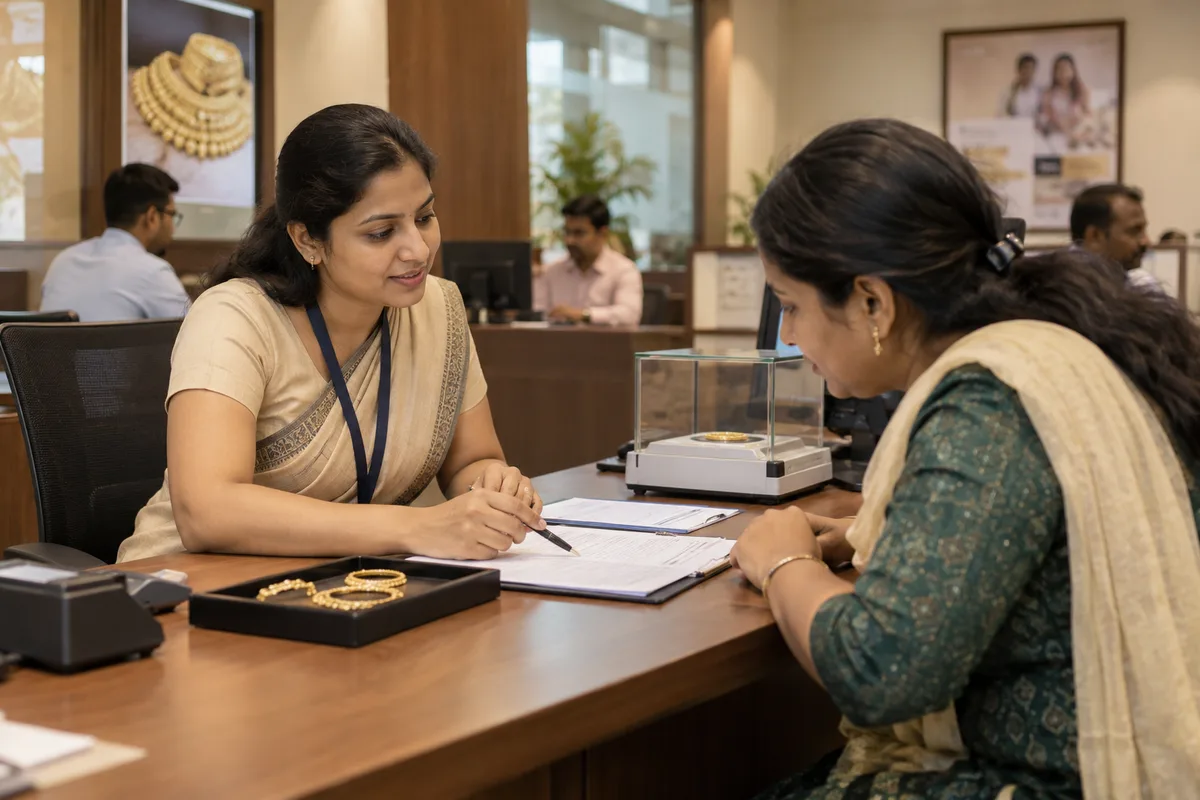
What CRM means
A CRM is the record where every enquiry, call and quote is kept against a customer, replacing separate notebooks, spreadsheets and memory. GullySales sets up or cleans an existing CRM and reports from it by enquiry outcome rather than by activity logged.
Also for gold loan and NBFC lenders
- Lead generation for gold loan and NBFC lenders
- Follow-up systems for gold loan and NBFC lenders
- SEO for gold loan and NBFC lenders
- Local SEO for gold loan and NBFC lenders
- PPC ads for gold loan and NBFC lenders
- Digital marketing for gold loan and NBFC lenders
- WhatsApp marketing for gold loan and NBFC lenders
- Reputation management for gold loan and NBFC lenders
Sales and marketing for gold loan and NBFC lenders, the overview.
Last updated 17 Oct 2026. Rules for this trade differ by state and professional body, and they change. We describe restrictions in general terms, so check the current position with your own council or adviser before you publish anything.
For gold loan and NBFC lenders
Where it usually goes wrong, and what we would do.
“The loan software is not a sales tool”
It records pledges, interest and closures accurately, and says nothing about the enquiry that did not pledge or the call due tomorrow. Sales needs its own simple record, linked to the loan by mobile number.
“Fields nobody fills in are worse than none”
A long form at the counter is skipped at the busiest hour. A few fields that the appraiser fills while weighing, such as name, mobile, product, source and outcome, get completed. Add more only when those are reliable.
“A lender's customer data carries duties”
Borrower details, KYC and consent bring obligations on storage and access. Settle your data protection duties and your regulator's expectations with your compliance officer before choosing where the records live.
“Staff phones are the real database”
Branch staff keep borrowers' numbers and call history in their own phones. When one leaves, the relationship leaves too. A shared record owned by the company is the fix.
What we do
What we deliver for gold loan and NBFC lenders.
The work available for this need. We agree the deliverables and responsibilities for your engagement in writing.
A short list of tools that fit
Two or three CRMs in ordinary use in India, compared against your branch count, languages, phone-first working and budget, with the loan system's export options noted.
Result: You choose with the costs and limits in front of you.
A minimum record at the counter
The fields every enquiry and pledge must carry, agreed with branch managers and filled while the appraisal is under way, with consent recorded.
Result: The record gets filled without slowing the queue.
Import of the existing borrower list
Closed and active borrowers brought in from the loan system with branch, product, last pledge date and consent status, cleaned of duplicates.
Result: The CRM starts with the borrowers you already have.
Views for each role
A list for the branch manager of open enquiries and due dates, one for the field officer and one for head office showing branch totals.
Result: Each person sees what they need to act on.
Tasks in place of memory
Due-date calls, renewal calls and enquiry callbacks created as tasks with a named owner, instead of sitting on a sheet.
Result: Nothing depends on someone remembering.
Access and consent rules
Who sees which borrowers, how records are exported and when they are deleted, written with compliance and the IT lead.
Result: A departing member of staff takes no data away.
Training in the branch language
Sessions at the branch on filling the record, with a one-page guide in the local language.
Result: The record is filled at the counter, not afterwards.
How the result is measured
- Enquiries logged in the CRM
- Data completeness
- Reports generated from CRM data
Recorded as a baseline before work starts, so every later report has an honest comparison.
Fields worth keeping
Fields a gold loan branch can fill at the counter without slowing the queue.
Keep the loan system for accounts. These fields sit beside it and are filled by the person who spoke to the borrower.
- Preferred language
- The counter staff pick it from a short list at the first conversation. It lets the callback, the WhatsApp message and the handout reach the borrower in Kannada, Tamil or Hindi.
- Season of need
- Sowing, school fees, festival or stock, recorded by the appraiser from what the borrower says. It tells you when to ring after the loan closes.
- How they reached the branch
- Walk-in, map call, dealer, jeweller or a relative, ticked at the counter. It shows which route brings borrowers and which is only a guess.
- Consent to call and message
- Taken in writing at pledge time and recorded with the date by the branch officer. Without it, no reminder or promotional message leaves the system.
- Interest due date and last reminder
- Copied from the loan system by the branch clerk and updated after each call. It prevents the first contact being the overdue notice.
- Reason for not going ahead
- Written in the borrower's own words by whoever lost the pledge, such as lower amount or distance. Branch managers read these to see what to change.
Who it is for
This is written for these gold loan and NBFC lenders.
- Gold loan NBFCs with a regional branch network
- Single-branch and family-run gold loan companies
- Licensed pawnbrokers and money lenders
- Nidhi companies lending to their members
- Credit cooperatives and souharda societies offering jewel loans
- Two-wheeler and used vehicle finance NBFCs
- MSME and small business loan NBFCs
- Microfinance lenders working with women's groups
Not for
It is not the right fit if.
- Staff share one phone and one register at the counter, so no one could be held to a record of who spoke to the borrower
- You have no policy on how long borrower details may be kept, so a database would store more than you may hold
Before you decide
Agree the work. Know how to judge it.
CRM for gold loan and NBFC lenders: use these checks to prepare, choose the scope, and review what changes.
Bring the right evidence
List the records your team uses and show how an enquiry becomes an order today. Bring examples of duplicate entries, missing owners, and reports that require manual correction.
Make the scope clear
Agree the stages, required fields, access roles, and integrations before configuring the system. Separate software subscriptions from setup, data work, and training.
Check the work in use
Ask the people who will use the CRM to complete a real handover and find the next action without help. Check that the management report can be traced back to individual records.
Know when to change course
If the process is unclear, buying a more complex CRM adds more places for confusion. Start with the minimum fields and rules the team can use consistently.
These are discussion points, not a fixed package. GullySales confirms the deliverables, responsibilities, fee, and term in writing after reading your brief and speaking with you.
How it works
How the CRM work runs
The work itself, in order. How an engagement starts, from your brief to a written scope, is set out on our method page.
- 1
Sales journey agreement
Your sales lead explains how an enquiry becomes an order, using open deals as examples. We agree which steps belong in the CRM and identify decisions needing your approval.
- 2
Configuration approval
You approve stage definitions, required fields, ownership rules, and access. Unresolved choices are settled before configuration starts.
- 3
Test environment decision
We confirm whether your plan provides a trial copy or separate pipeline. Where neither is available, changes to the live system need an agreed approach before work proceeds.
- 4
Connection and rule checks
Enquiry connections are checked before automations are activated separately. Your nominated owner verifies where records arrive and which person receives each task.
- 5
Sales team acceptance
The people handling enquiries test open deals from entry through closure. Required corrections are resolved before you approve the switch.
- 6
Switch and ownership handover
The agreed configuration goes into use, and your CRM owner receives the final record. Any post-switch corrections included in the scope are documented before handover closes.
Where this fits
Three pieces of sales work, in this order.
This work sits inside sales management. A target, a review routine and someone who owns the number.
Step 1
Sales audit
Find where deals are being lost and what to fix first.
Start here if you cannot say where orders are lost.
Step 2
Sales process design
One written way to sell, from first enquiry to repeat order.
Start here if every salesperson sells differently.
Step 3 · you are here
Sales management
A target, a review routine and someone who owns the number.
Start here if the team has targets and no routine.
FAQ
Questions owners ask before they call.
Not here? More answers, or ask on WhatsApp.
Can the CRM sit inside our loan software?
Is a spreadsheet enough for a single branch?
Should borrowers' documents be stored in the CRM?
Who should be able to see a borrower's records?
How much does it cost?
How long is the contract?
How soon will we see results?
Who will actually do the work?
What do you need from us?
What if we are not happy with the work?
From the blog
Further reading for gold loan and NBFC lenders.
 5 min read · 6 Oct 2026Why gold loan borrowers pledge elsewhere after they closeA closed gold loan is the cheapest next enquiry a branch gets. What to record on release day, when to call again, and how to answer a takeover offer.
 6 min read · 6 Oct 2026How buyers decide which lender or adviser to trustPeople choosing a bank, lender, adviser or insurer start with a name someone gave them, then check you before calling. See what they look for.
 6 min read · 21 Jun 2026Explaining financial jargon on your website so a first-time customer keeps readingWrite plain-language finance pages: define the term, show a worked example and say who the product is not for, so first-time customers keep reading.
More for gold loan and NBFC lenders
Related work to consider.
Closest to this: leads and follow-up
Also for gold loan and NBFC lenders
Or start from the overview: sales and marketing for gold loan and NBFC lenders.
Your next practical step
Tell us what you are trying to grow, and we will read it before we call.
Eight short steps, mostly taps. Skip anything you would rather answer on the call.