Gold loan and NBFC lenders · Pay per click advertising
Pay for the borrower ready to pledge today, not the one checking the gold price.
Pay-per-click (PPC) advertising for a gold loan or NBFC lender means bidding on people who need a loan near a branch now, and blocking the far larger crowd checking gold prices or looking to sell. GullySales sets up the campaigns within Google's rules for financial services and counts pledges at the branch, not clicks.
Scope, fee, reporting and term are agreed in writing after we have read your brief and spoken to you.
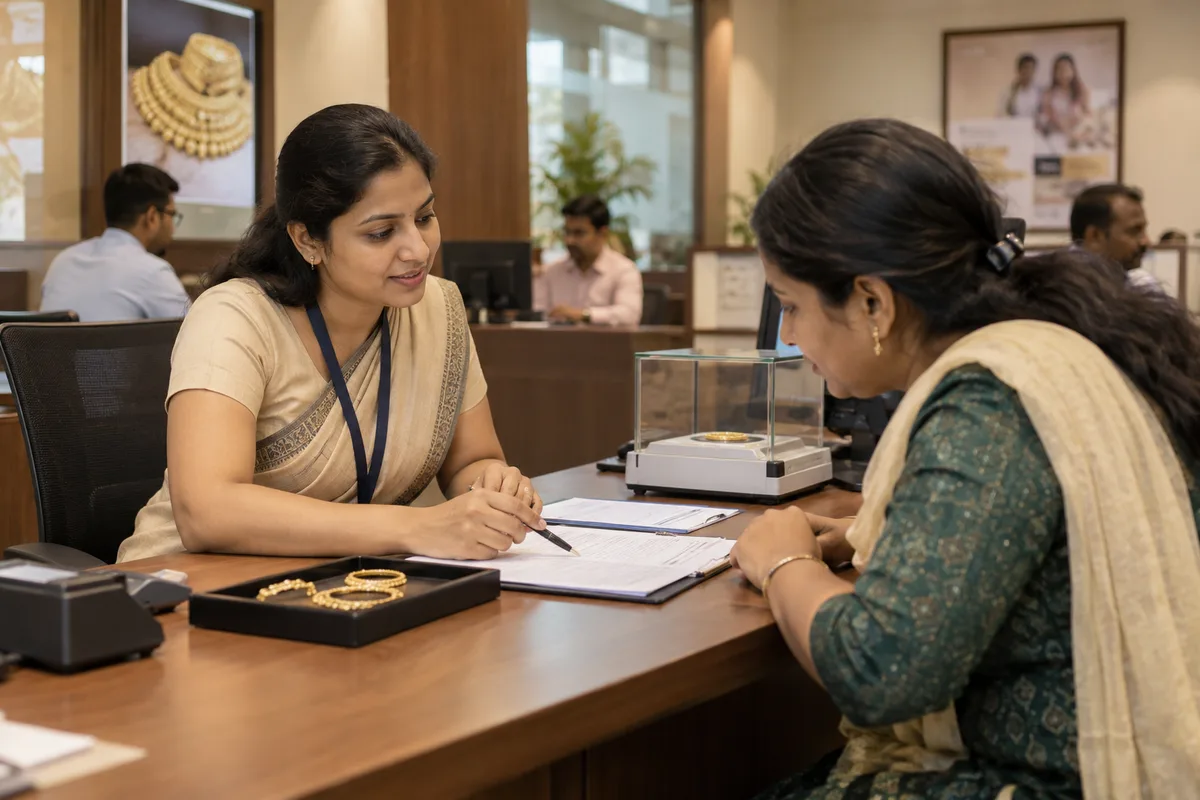
What pay per click advertising means
Pay per click advertising (PPC) is paying a fee each time someone clicks your advert on Google or another platform. It puts you at the top of a search page immediately, instead of waiting for ranking to build. GullySales sets the targeting, writes the ad text and checks spend against enquiries received.
Also for gold loan and NBFC lenders
- SEO for gold loan and NBFC lenders
- Local SEO for gold loan and NBFC lenders
- Digital marketing for gold loan and NBFC lenders
- WhatsApp marketing for gold loan and NBFC lenders
- Reputation management for gold loan and NBFC lenders
- Lead generation for gold loan and NBFC lenders
- Follow-up systems for gold loan and NBFC lenders
- Customer retention for gold loan and NBFC lenders
Sales and marketing for gold loan and NBFC lenders, the overview.
Last updated 17 Oct 2026. Rules for this trade differ by state and professional body, and they change. We describe restrictions in general terms, so check the current position with your own council or adviser before you publish anything.
For gold loan and NBFC lenders
Where it usually goes wrong, and what we would do.
“Gold rate searches are not loan searches”
Most people typing gold rate today want the price before buying jewellery. Without a long negative list, the budget pays for curiosity.
“Financial services ads need verification first”
Google asks lenders and loan advertisers in India to verify and show certain details before ads run, and the rules change. Check the platform's current rules before building anything.
“A click is worth nothing until the gold is on the counter”
A gold loan is decided at the branch, not on a form. The campaign needs a way to know which callers walked in and pledged.
What we do
What we deliver for gold loan and NBFC lenders.
The work available for this need. We agree the deliverables and responsibilities for your engagement in writing.
Campaigns split by branch catchment
Location targeting drawn around each branch, with budget moved towards branches that have counter capacity and away from those already queueing.
Result: Ads send borrowers to branches that can serve them.
A negative keyword list built for gold
Gold rate, sell gold, gold buyer, hallmark, jewellery shop, coin, appraiser job and appraiser course, kept current from the search terms report.
Result: Spend goes to borrowers, not to shoppers and job seekers.
Call ads that ring the branch
Call assets and call ads routed to the nearest branch's answered number in counter hours, and to a central desk outside them.
Result: The caller reaches someone who can say what the gold will fetch.
Landing pages per scheme and town
Pages carrying the scheme in plain words, the documents to bring, the nearest branch and the disclosures your compliance officer requires.
Result: The ad, the page and the counter say the same thing.
A reference code that closes the loop
A short code given to every ad caller, which the branch writes into the loan entry when that borrower pledges.
Result: You can count pledges from ads, not just calls.
Verification papers kept in one place
Registration details, verification status and the history of disapproved ads held centrally, so a new campaign is not held up by a missing document.
Result: Campaigns stop stalling on paperwork.
How the result is measured
- Cost per click
- Cost per enquiry
- Enquiries from paid search
Recorded as a baseline before work starts, so every later report has an honest comparison.
Searches to bid on and block
The searches from a borrower ready to pledge, and the ones that waste a gold loan budget.
- gold loan near me, and gold loan in your branch towns
- Bid, inside each branch's catchment. These borrowers want a counter today. Show the branch hours in the ad and route call assets to the branch number.
- gold loan takeover and transfer gold loan
- Bid. A borrower moving from another lender has already decided to borrow. Send the click to a takeover page and keep other lenders' names out of the ad.
- gold rate today and 22 carat price
- Block. These are buyers checking the price for jewellery or coins. Add rate today, price today and hallmark as negatives, and watch the terms report for gold loan per gram, which you want.
- sell old gold and gold buyers near me
- Block. Selling is a different decision. A small separate campaign offering a loan instead of a sale is worth testing only if your compliance officer agrees the wording.
- Where the click lands
- On the page for that scheme or branch, with the documents to bring, a call button to the nearest branch and the disclosures compliance requires. Never land a loan click on the home page.
- Counting a real enquiry
- Count a call long enough to discuss the gold or the loan, or a form with a product and town. Then count pledges from the reference the branch records. Clicks alone prove nothing.
Who it is for
This is written for these gold loan and NBFC lenders.
- Gold loan NBFCs with a regional branch network
- Single-branch and family-run gold loan companies
- Licensed pawnbrokers and money lenders
- Nidhi companies lending to their members
- Credit cooperatives and souharda societies offering jewel loans
- Two-wheeler and used vehicle finance NBFCs
- MSME and small business loan NBFCs
- Microfinance lenders working with women's groups
Not for
It is not the right fit if.
- Compliance has not approved any wording for a paid advertisement, so every draft would wait unused
- Branches do not write down how a walk-in heard of you, so you could not tell whether the ads brought anyone
- Your only offer is a headline rate you cannot honour at the counter
Before you decide
Agree the work. Know how to judge it.
PPC ads for gold loan and NBFC lenders: use these checks to prepare, choose the scope, and review what changes.
Bring the right evidence
Bring search-term reports, conversion definitions, and the sales outcome of past enquiries where available. Identify products, locations, and enquiries you cannot serve.
Make the scope clear
Choose the offer and landing page before setting a media budget. Agree who pays the platform, which actions count as conversions, and how unsuitable searches will be reviewed.
Check the work in use
Trace a test enquiry from the advert to the sales record. Review qualified enquiries and orders alongside spend, and separate duplicates or spam from genuine buyer demand.
Know when to change course
If the advert generates enquiries that do not fit, revise targeting and qualification before increasing spend. If suitable enquiries are lost after contact, work on the sales process.
These are discussion points, not a fixed package. GullySales confirms the deliverables, responsibilities, fee, and term in writing after reading your brief and speaking with you.
How it works
How the pay per click advertising work runs
The work itself, in order. How an engagement starts, from your brief to a written scope, is set out on our method page.
- 1
Budget and responsibility approval
You approve the channels, total spend, account ownership, and budget-movement limits. We name the person who approves campaigns and the sales contact responsible for enquiry outcomes.
- 2
Tracking readiness decision
We check account tracking against your enquiry sheet, call log, or CRM. Missing access and unreliable conversion events are identified before deciding what is ready to launch.
- 3
Sales definitions sign-off
Your sales contact agrees what qualifies an enquiry and what counts as a completed order. We record the baseline and decide how duplicate enquiries will be handled.
- 4
Campaign launch approval
You review the proposed campaign structure and response route. Required changes to advertising material or landing pages are identified, with any separate production work agreed before launch.
- 5
Lead-quality review
Your sales team supplies enquiry outcomes; we compare them with campaign and search-term records. Irrelevant traffic and missing source information are addressed before recommending more spend.
- 6
Allocation decision and handover
We make authorised budget moves or send decisions outside those limits for approval. The combined report records the evidence and identifies any action needed from your sales team.
Where this fits
Three pieces of sales work, in this order.
This work sits inside sales process design, at stage 1, prospecting and lead generation. The audit comes before it, and sales management keeps it running.
Step 1
Sales audit
Find where deals are being lost and what to fix first.
Start here if you cannot say where orders are lost.
Step 2 · you are here
Sales process design
One written way to sell, from first enquiry to repeat order.
Start here if every salesperson sells differently.
Step 3
Sales management
A target, a review routine and someone who owns the number.
Start here if the team has targets and no routine.
FAQ
Questions owners ask before they call.
Not here? More answers, or ask on WhatsApp.
Should we bid on our own company name?
Call ads or a form for gold loan enquiries?
Our ads keep attracting job seekers. Why?
How do we know if an ad caller pledged at the branch?
How much does it cost?
How long is the contract?
How soon will we see results?
Who will actually do the work?
What do you need from us?
What if we are not happy with the work?
From the blog
Further reading for gold loan and NBFC lenders.
 5 min read · 6 Oct 2026Why gold loan borrowers pledge elsewhere after they closeA closed gold loan is the cheapest next enquiry a branch gets. What to record on release day, when to call again, and how to answer a takeover offer.
 6 min read · 6 Oct 2026How buyers decide which lender or adviser to trustPeople choosing a bank, lender, adviser or insurer start with a name someone gave them, then check you before calling. See what they look for.
 6 min read · 21 Jun 2026Explaining financial jargon on your website so a first-time customer keeps readingWrite plain-language finance pages: define the term, show a worked example and say who the product is not for, so first-time customers keep reading.
More for gold loan and NBFC lenders
Related work to consider.
Or start from the overview: sales and marketing for gold loan and NBFC lenders.
Your next practical step
Tell us what you are trying to grow, and we will read it before we call.
Eight short steps, mostly taps. Skip anything you would rather answer on the call.