Gold loan and NBFC lenders · Buyer persona
Decide who is standing at the counter before deciding what to say to them.
A buyer persona for a gold loan or NBFC lender describes the person who needs the money, the family member who sways the choice and the dealer or jeweller who sends them. GullySales builds one from your pledge register and your branch managers' knowledge, for each product and region.
Scope, fee, reporting and term are agreed in writing after we have read your brief and spoken to you.
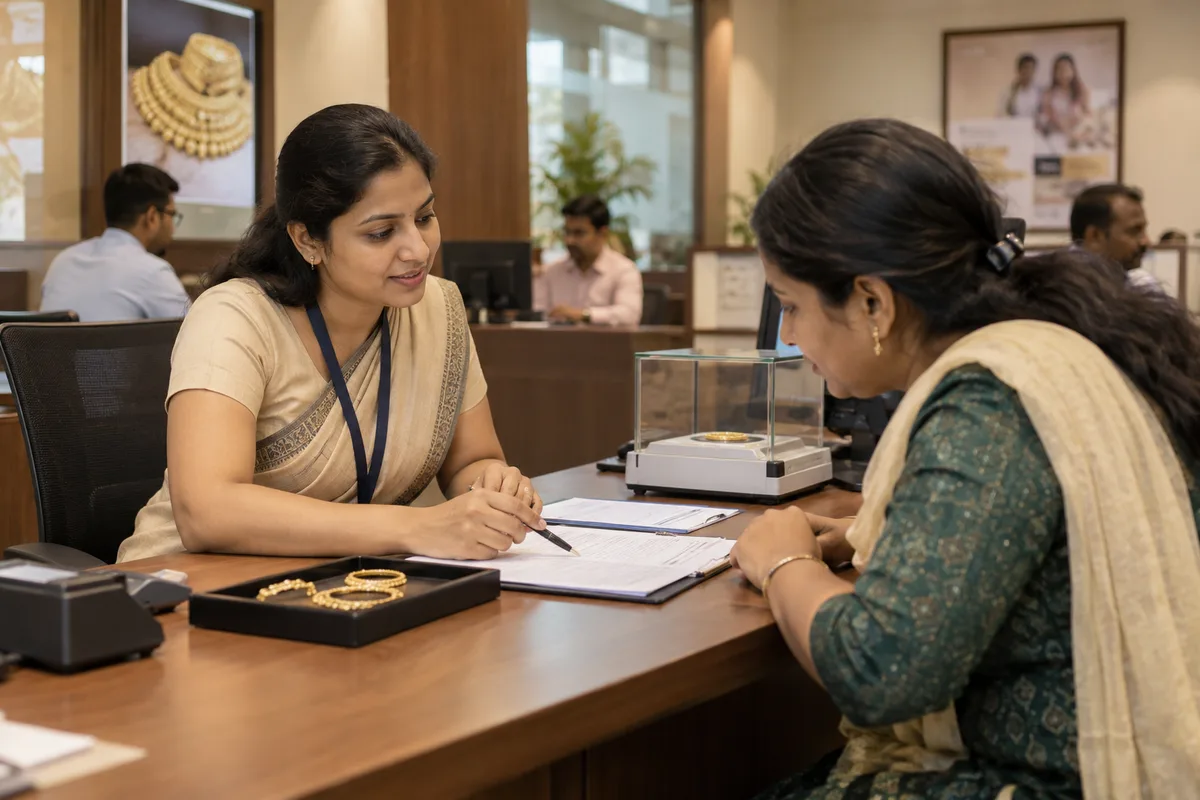
What buyer persona means
A buyer persona is a plain description of the kind of customer who actually buys from you. It includes what they search, what worries them and who else they ask before deciding. GullySales builds this from real enquiries and past sales rather than a generic template, then uses it to write every page and advert.
Also for gold loan and NBFC lenders
- Digital marketing for gold loan and NBFC lenders
- SEO for gold loan and NBFC lenders
- Local SEO for gold loan and NBFC lenders
- PPC ads for gold loan and NBFC lenders
- WhatsApp marketing for gold loan and NBFC lenders
- Reputation management for gold loan and NBFC lenders
- Lead generation for gold loan and NBFC lenders
- Follow-up systems for gold loan and NBFC lenders
Sales and marketing for gold loan and NBFC lenders, the overview.
Last updated 17 Oct 2026. Rules for this trade differ by state and professional body, and they change. We describe restrictions in general terms, so check the current position with your own council or adviser before you publish anything.
For gold loan and NBFC lenders
Where it usually goes wrong, and what we would do.
“The farmer borrows against a calendar”
A borrower in a farm belt needs money before sowing and repays after harvest. Messages, hours and repayment options built around that calendar fit. A generic city message about instant cash does not.
“The family jewellery borrower weighs privacy first”
Borrowers pledging jewellery that others at home need not hear about put discretion above the last rupee of rate. A private counter and a reminder that names no amount decide the choice more than any banner.
“The trader needs cash between market days”
A small trader borrowing against gold to bridge stock wants a short, clear closure and a branch open at the hour the market winds down. Interest matters less than being served before the next delivery.
“The vehicle buyer is persuaded at the showroom”
A two-wheeler buyer meets the financier at the dealer's desk. The person who decides there is the dealer's salesperson, who points the buyer to whichever lender turns the file round without fuss.
What we do
What we deliver for gold loan and NBFC lenders.
The work available for this need. We agree the deliverables and responsibilities for your engagement in writing.
A persona for each product and region
One written card for farm-belt gold loan borrowers, one for town traders, one for vehicle buyers and so on, built from your pledge register and field officers' notes.
Result: Each branch can see which borrower it mainly serves.
A map of who else decides
For each persona, the spouse, parent, adult child, dealer or jeweller whose opinion counts, and what that person worries about.
Result: Messages reach the person who can say no.
The questions each persona asks
Taken from the counter, the phone and WhatsApp, in the persona's language, ordered by what is asked first.
Result: Scheme sheets and replies begin with the real question.
The month the need arises
A calendar for each persona showing when money is needed and when repayment sits comfortably.
Result: Campaigns reach the borrower before the need, not after.
Doubts and the honest answer
What each persona doubts, such as safety, valuation or embarrassment, with an answer staff can give truthfully.
Result: Counter staff meet a doubt with an answer, not a pitch.
A check against borrowers who left
The cards compared with closed borrowers who did not return and enquiries that did not pledge, to see which persona is slipping away.
Result: You see which borrower a branch is failing.
How the result is measured
- Enquiry match to persona
- Conversion rate by persona
- Content aligned to persona
Recorded as a baseline before work starts, so every later report has an honest comparison.
Who is asking
Who stands at a gold loan counter, and what each wants to know.
Fill these from the pledge register and branch managers' memory. Add the persona only when a branch can name a real borrower who fits.
- Farmer before the sowing season
- Wants to know how much the family chain will raise, how repayment can follow the harvest and whether the gold is safe while away. The first question can be about the language of the scheme.
- Parent paying school or college fees
- Wants a quiet counter and to know what a part payment or renewal costs. Needs the receipt explained so the spouse sees it at home.
- Shopkeeper short of stock money
- Wants cash between market days and a clear idea of when the interest falls due. Asks whether the loan can be renewed without bringing the gold again.
- Family member sent by an older borrower
- Wants to know what to carry and whether they may collect the gold. Needs the authority letter requirements said clearly before they travel.
- Borrower returning from another lender
- Wants to compare the scheme in writing and learn what moving costs. Needs the closure amount process explained without criticism of the other lender.
- Two-wheeler buyer with farm income
- Wants to know which documents replace a salary slip and which dealers you work with. Asks about interest only after the showroom has chosen the model.
Who it is for
This is written for these gold loan and NBFC lenders.
- Gold loan NBFCs with a regional branch network
- Single-branch and family-run gold loan companies
- Licensed pawnbrokers and money lenders
- Nidhi companies lending to their members
- Credit cooperatives and souharda societies offering jewel loans
- Two-wheeler and used vehicle finance NBFCs
- MSME and small business loan NBFCs
- Microfinance lenders working with women's groups
Not for
It is not the right fit if.
- Your pledge register is not kept in a form you can read by product or branch, so a persona would rest on opinion
- Branch managers are not available to describe the borrowers they serve, so the personas would copy a national average
Before you decide
Agree the work. Know how to judge it.
Buyer personas for gold loan and NBFC lenders: use these checks to prepare, choose the scope, and review what changes.
Bring the right evidence
Write the decision the research must support, such as entering a market or choosing a buyer group. Separate what you know from sales records from what the team currently assumes.
Make the scope clear
Agree which buyers to speak to, which sources to review, and what access you can provide. Include lost enquiries and people who chose another supplier, where they are willing to take part.
Check the work in use
Look for source dates, sample limitations, and evidence that disagrees with the preferred answer. A recommendation should show how it follows from the findings.
Know when to change course
Do not treat a few positive conversations as proof of demand. Test the proposed offer with an actual buying decision before committing to a wider launch.
These are discussion points, not a fixed package. GullySales confirms the deliverables, responsibilities, fee, and term in writing after reading your brief and speaking with you.
How it works
How the buyer persona work runs
The work itself, in order. How an engagement starts, from your brief to a written scope, is set out on our method page.
- 1
Audience decision and scope approval
You send the requirements brief, then we discuss the decision these personas must support. The written scope identifies the audience groups and agreed outputs before work starts.
- 2
Record access and interview selection
Your team shares relevant purchase records and agrees which customers to approach. Customers agree before contact, and we identify gaps such as missing lost-deal notes.
- 3
Interview findings and evidence check
We ask buyers about their last purchase, including what happened before the enquiry and who else was involved. Staff conversations add objections and questions, with differences between accounts kept visible.
- 4
Persona review and corrections
Draft profiles go to the people who handle enquiries and close orders. We check disputed points against the available evidence rather than treating internal agreement as proof.
- 5
Application priorities and handover
You approve the profiles and decide which existing assets need attention first. The persona documents and application map pass to your marketing and sales owners, with implementation responsibilities recorded.
Where this fits
Three pieces of sales work, in this order.
This work sits inside sales process design, at stage 0, foundation. The audit comes before it, and sales management keeps it running.
Step 1
Sales audit
Find where deals are being lost and what to fix first.
Start here if you cannot say where orders are lost.
Step 2 · you are here
Sales process design
One written way to sell, from first enquiry to repeat order.
Start here if every salesperson sells differently.
Step 3
Sales management
A target, a review routine and someone who owns the number.
Start here if the team has targets and no routine.
FAQ
Questions owners ask before they call.
Not here? More answers, or ask on WhatsApp.
How many personas does a lender need?
Where does the information come from?
Do we need to collect more borrower data for this?
Should the persona include the borrower's caste or religion?
How much does it cost?
How long is the contract?
How soon will we see results?
Who will actually do the work?
What do you need from us?
What if we are not happy with the work?
From the blog
Further reading for gold loan and NBFC lenders.
 5 min read · 6 Oct 2026Why gold loan borrowers pledge elsewhere after they closeA closed gold loan is the cheapest next enquiry a branch gets. What to record on release day, when to call again, and how to answer a takeover offer.
 6 min read · 6 Oct 2026How buyers decide which lender or adviser to trustPeople choosing a bank, lender, adviser or insurer start with a name someone gave them, then check you before calling. See what they look for.
 6 min read · 21 Jun 2026Explaining financial jargon on your website so a first-time customer keeps readingWrite plain-language finance pages: define the term, show a worked example and say who the product is not for, so first-time customers keep reading.
More for gold loan and NBFC lenders
Related work to consider.
Closest to this: strategy and research
Also for gold loan and NBFC lenders
Or start from the overview: sales and marketing for gold loan and NBFC lenders.
Your next practical step
Tell us what you are trying to grow, and we will read it before we call.
Eight short steps, mostly taps. Skip anything you would rather answer on the call.