Gold loan and NBFC lenders · Sales training
Train the appraiser to explain the loan as well as weigh the gold.
Sales training for a gold loan or NBFC lender prepares branch staff for the conversations that decide a pledge: the amount offered, the safety of the gold, the scheme, the takeover customer and the angry caller. GullySales builds it from your own branches' lost enquiries and complaints, in the languages your counters speak.
Scope, fee, reporting and term are agreed in writing after we have read your brief and spoken to you.
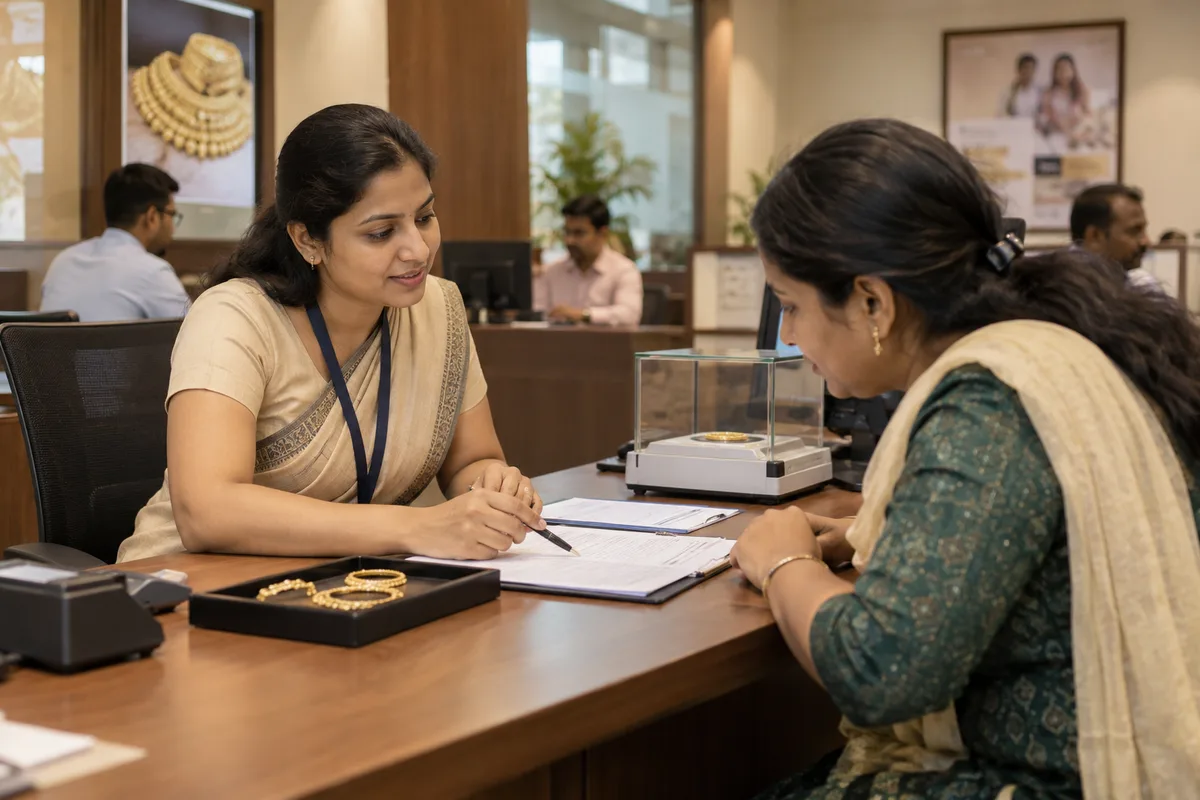
What sales training means
Sales training teaches a sales team a skill it does not yet have, such as handling a specific objection or running a proper site visit, usually through a structured session. GullySales runs these sessions around real objections and calls from your business rather than generic sales theory.
Also for gold loan and NBFC lenders
- SEO for gold loan and NBFC lenders
- Local SEO for gold loan and NBFC lenders
- PPC ads for gold loan and NBFC lenders
- Digital marketing for gold loan and NBFC lenders
- WhatsApp marketing for gold loan and NBFC lenders
- Reputation management for gold loan and NBFC lenders
- Lead generation for gold loan and NBFC lenders
- Follow-up systems for gold loan and NBFC lenders
Sales and marketing for gold loan and NBFC lenders, the overview.
Last updated 17 Oct 2026. Rules for this trade differ by state and professional body, and they change. We describe restrictions in general terms, so check the current position with your own council or adviser before you publish anything.
For gold loan and NBFC lenders
Where it usually goes wrong, and what we would do.
“Branch staff are hired to appraise, not to explain”
An appraiser who tests purity well may still say the amount, the rate and nothing else. The borrower compares that silence with the branch down the road that talked them through it.
“The safety question is the real objection”
Borrowers worry that the ornaments will be swapped, damaged or lost. Staff who show the sealed packet, the receipt and the vault process answer what the borrower is too polite to ask.
“Pressure at the counter costs more than a lost loan”
A borrower pushed into a larger amount or a longer scheme struggles at renewal and complains. Training sets what staff may and may not suggest.
What we do
What we deliver for gold loan and NBFC lenders.
The work available for this need. We agree the deliverables and responsibilities for your engagement in writing.
Role-play from real branch situations
Practice sessions built on actual lost enquiries and complaints from your branches, with names removed.
Result: Staff rehearse the conversations they really face.
A valuation walk-through for the counter
How to show the borrower the weight, the stone deduction and the purity reading, step by step, while they watch.
Result: The amount offered is understood, even when it disappoints.
Scheme explanations practised aloud
Each scheme explained by every staff member until it sounds natural in Kannada, Tamil, Telugu or the branch's own language, checked by a senior.
Result: Borrowers hear the scheme the same way at every branch.
A module for new joiners
The first conversations a new appraiser or relationship officer will have, written down with examples, so nobody learns only from whoever trained them.
Result: New staff start with the company's standard, not one branch's habits.
Conduct lines staff must not cross
What may not be promised, pushed or said about rates, approval, auction or other lenders, agreed with compliance and practised.
Result: Staff know the boundary before a borrower tests it.
Observation by the branch manager
A short checklist the manager uses to watch one counter conversation and give feedback the same day.
Result: Training carries on after the session ends.
How the result is measured
- Skill assessment scores
- Objection handling improvement
- Conversion rate after training
Recorded as a baseline before work starts, so every later report has an honest comparison.
Situations to practise
Six conversations a gold loan branch should practise, and what good looks like.
- 'The other branch gave more for the same chain'
- Show the weight, the stone deduction and the purity reading again. Explain how your amount is worked out without criticising the other lender. Practise staying calm when the borrower doubts you.
- 'Will I get the same ornaments back?'
- Show the sealed packet, the pledge receipt and how release works. Answer before they have to ask twice. Practise saying it plainly rather than defensively.
- First-time borrower who is embarrassed
- Lower your voice, use the private counter and explain the scheme slowly in their language. Practise never discussing the loan where others in the queue can hear.
- Caller who only asks the rate per gram
- Give the figure the branch is allowed to quote today, then ask what they plan to pledge and when they can come. Practise turning a rate call into a visit.
- Takeover customer asking you to match an offer
- Ask what the other lender offered in writing and set your scheme beside it. Offer only what your rules allow. Practise saying no to a match you cannot make.
- Angry borrower holding an overdue notice
- Listen first, check the reminders on record, then explain the options: pay the interest, part pay, renew or close. Practise not arguing about whose fault it was.
Who it is for
This is written for these gold loan and NBFC lenders.
- Gold loan NBFCs with a regional branch network
- Single-branch and family-run gold loan companies
- Licensed pawnbrokers and money lenders
- Nidhi companies lending to their members
- Credit cooperatives and souharda societies offering jewel loans
- Two-wheeler and used vehicle finance NBFCs
- MSME and small business loan NBFCs
- Microfinance lenders working with women's groups
Not for
It is not the right fit if.
- Your appraisers are not yet allowed to quote an amount or explain a scheme, so training them to sell would conflict with the branch rules
- Branch managers have not agreed what a good counter conversation looks like, so each trainer would teach a different one
Before you decide
Agree the work. Know how to judge it.
Sales training for gold loan and NBFC lenders: use these checks to prepare, choose the scope, and review what changes.
Bring the right evidence
Bring real questions, objections, and call examples that the team finds difficult. Agree which selling behaviour needs to change and how it will be observed at work.
Make the scope clear
Choose the roles and situations to practise. Separate a training session from coaching, manager follow-up, and any scripts or reference material to be produced.
Check the work in use
Use a realistic practice conversation, then review the same skill in live work with appropriate permission. Look for a change in behaviour before attributing a sales result to training.
Know when to change course
If the problem is an unclear offer, missing product knowledge, or no permission to make a decision, fix that first. A communication workshop cannot remove those barriers.
These are discussion points, not a fixed package. GullySales confirms the deliverables, responsibilities, fee, and term in writing after reading your brief and speaking with you.
How it works
How the sales training work runs
The work itself, in order. How an engagement starts, from your brief to a written scope, is set out on our method page.
- 1
Requirements and commercial agreement
Send the requirements brief, then discuss the roles and training problem with GullySales. The scope, fee, and term are agreed in writing before work starts.
- 2
Evidence review and skills agreement
We review available calls and CRM records with your manager, then assess the team against a proposed skills map. You approve which roles and gaps the programme will cover.
- 3
Content approval
Your nominated product expert checks the teaching material for accuracy. The sales manager approves the module order and session calendar around selling responsibilities.
- 4
Session delivery and practice
Reps work through the agreed modules and practise with scenarios from your sales conversations. Feedback records the skill demonstrated and the correction needed.
- 5
Readiness decision
Knowledge checks test product understanding; a live or recorded call check tests application. Your manager decides whether the rep is ready or needs further practice.
- 6
Manager handover
The manager receives assessment findings and the agreed refresher priorities. We show them how to continue practice, with any further delivery or individual coaching scoped separately.
Where this fits
Three pieces of sales work, in this order.
This work sits inside sales management. A target, a review routine and someone who owns the number.
Step 1
Sales audit
Find where deals are being lost and what to fix first.
Start here if you cannot say where orders are lost.
Step 2
Sales process design
One written way to sell, from first enquiry to repeat order.
Start here if every salesperson sells differently.
Step 3 · you are here
Sales management
A target, a review routine and someone who owns the number.
Start here if the team has targets and no routine.
FAQ
Questions owners ask before they call.
Not here? More answers, or ask on WhatsApp.
Our staff are shy about role-play. Will it still work?
Should new joiners sit at the counter straight away?
Should we give staff a word-for-word script?
Can the training cover recovery calls too?
How much does it cost?
How long is the contract?
How soon will we see results?
Who will actually do the work?
What do you need from us?
What if we are not happy with the work?
From the blog
Further reading for gold loan and NBFC lenders.
 5 min read · 6 Oct 2026Why gold loan borrowers pledge elsewhere after they closeA closed gold loan is the cheapest next enquiry a branch gets. What to record on release day, when to call again, and how to answer a takeover offer.
 6 min read · 6 Oct 2026How buyers decide which lender or adviser to trustPeople choosing a bank, lender, adviser or insurer start with a name someone gave them, then check you before calling. See what they look for.
 6 min read · 21 Jun 2026Explaining financial jargon on your website so a first-time customer keeps readingWrite plain-language finance pages: define the term, show a worked example and say who the product is not for, so first-time customers keep reading.
More for gold loan and NBFC lenders
Related work to consider.
Or start from the overview: sales and marketing for gold loan and NBFC lenders.
Your next practical step
Tell us what you are trying to grow, and we will read it before we call.
Eight short steps, mostly taps. Skip anything you would rather answer on the call.