NBFCs · Content marketing
Publish the answers a borrower needs before they apply, and be the lender who gave them.
Content marketing for an NBFC is writing the guides, checklists and explanations a borrower reads before choosing a lender. GullySales works on which questions to answer, who writes them with your credit team and how each piece leads to an enquiry.
Scope, fee, reporting and term are agreed in writing after we have read your brief and spoken to you.
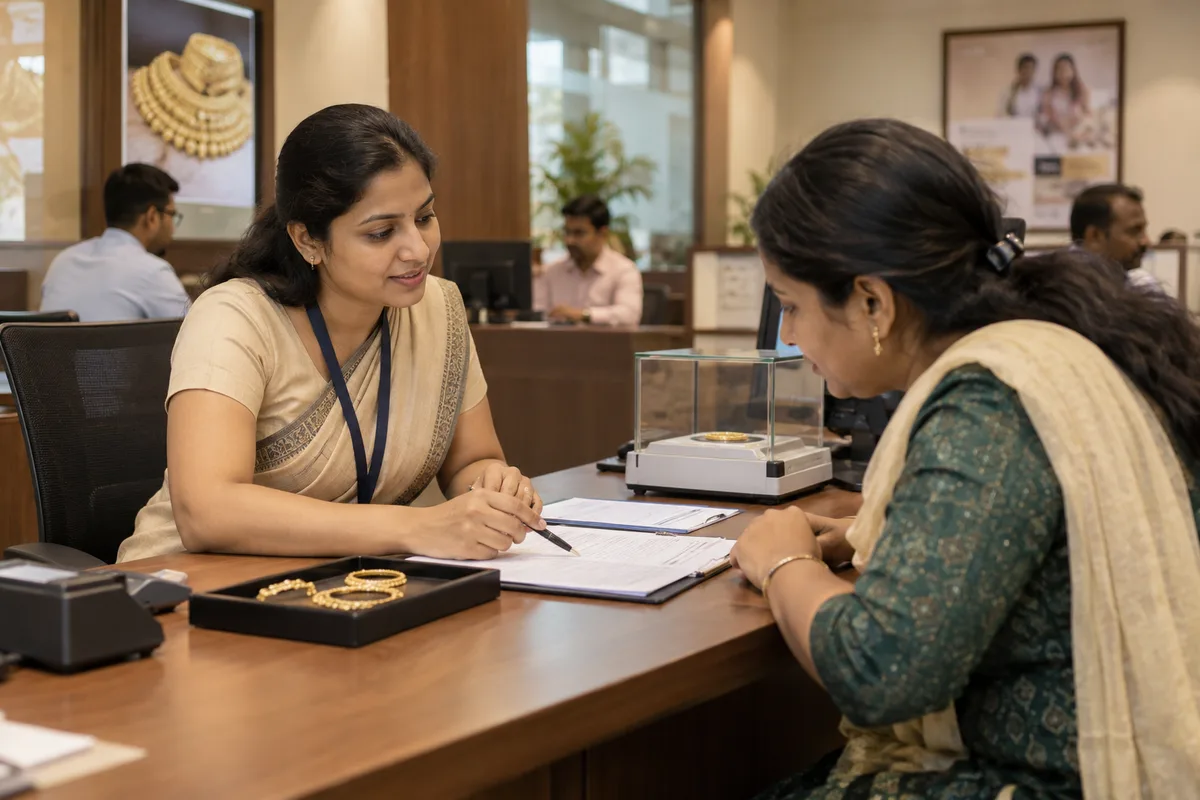
What content marketing means
Content marketing is writing articles, guides and pages that answer the questions buyers search before they are ready to enquire. This makes your business visible and trusted before the first call. GullySales plans this content from the first conversation onward, choosing topics that match real search demand rather than guesses.
Last updated 14 Nov 2026. Rules for this trade differ by state and professional body, and they change. We describe restrictions in general terms, so check the current position with your own council or adviser before you publish anything.
For NBFCs
Where it usually goes wrong, and what we would do.
“The borrower has a question the loan page does not answer”
Which papers prove income for a person with no salary slip? What happens if one instalment is missed? A page that answers this plainly earns the call from someone already close to applying.
“Credit staff know the real objections”
The people who reject and approve files hear the same confusion repeatedly. Their answers, turned into short guides, are more useful than anything a content writer invents from the outside.
“Jargon sends the borrower away”
Terms like tenure, foreclosure and processing fee are understood by your team and by few applicants. A guide that explains each term in the borrower's own words keeps the reader on your page.
“Content for partners is a different document”
A DSA wants a one-page product sheet and a clear rejection reason list, not a blog. Partner material saves their time and decides whether your name comes up when a file needs a home.
What we do
What we deliver for NBFCs.
The work available for this need. We agree the deliverables and responsibilities for your engagement in writing.
A question bank from calls and rejections
The questions borrowers actually ask, collected from callers, branches and rejected files, ranked by how badly they stall a file.
Result: Topics come from your own files, not guesses.
Document checklist guides for each product
A plain checklist for each loan type, with what proves identity, address and income for different kinds of borrower.
Result: Applicants arrive with the right papers.
Glossary of lending terms in plain words
Short entries for each term that appears in your offer letter and agreement, written for a first-time borrower.
Result: Confusion at the sanction stage falls.
Partner product sheets
One page per product for DSAs and dealers: who qualifies, what to submit and how the file is tracked.
Result: Partners can brief the borrower without calling you.
Review of every piece by credit and compliance
A sign-off step before publishing, so nothing promises approval, rate or timing.
Result: Published pages match your policy.
How the result is measured
- Pages published
- Organic traffic
- Enquiries from content pages
Recorded as a baseline before work starts, so every later report has an honest comparison.
Posts and pieces to plan
Pieces a lender can publish that answer what a borrower asks before applying.
- What a CIBIL score means for a loan
- A plain explainer on how the score is read in your credit process. Credit staff check it, and no approval is implied.
- Documents needed for each loan product
- One guide per product with the real checklist your branches use. It is the piece partners forward and callers send.
- Why a loan file can be rejected
- A page built from rejection reasons gathered from files. It tells a borrower what to fix, and it lowers repeat calls.
- EMI, tenure and processing fee in plain words
- A glossary entry for each term with a worked example, using rounded sums of money labelled as an illustration.
- Choosing between a gold loan and a personal loan
- A comparison written for a borrower in a hurry. Describe the trade-offs and leave the choice to them.
- What a dealer should know before sending a file
- A partner guide covering document quality, what is checked and who the partner calls for status.
Who it is for
This is written for these NBFCs.
- Vehicle and two-wheeler finance NBFCs working through dealers
- MSME and business loan NBFCs working through DSAs
- Home loan and loan against property housing finance companies
- Consumer durable and personal loan NBFCs
- Gold loan NBFCs with a branch-led model
- Microfinance NBFCs working with groups of women borrowers
- Digital lending NBFCs partnering with apps and platforms
- Infrastructure and equipment finance NBFCs selling to businesses
- Regional NBFCs opening branches in a new district
Before you decide
When this may not be the right fit.
- Credit and compliance cannot review drafts, so every piece would stay in a folder instead of reaching a borrower.
- Your products and charges are being revised, so guides written now would carry numbers you would have to retract.
- Nobody has recorded why files are rejected, so there is no real question bank to write from.
Before you decide
Agree the work. Know how to judge it.
Content marketing for NBFCs: use these checks to prepare, choose the scope, and review what changes.
Bring the right evidence
Bring questions from sales calls and examples of objections that delay a decision. Choose a subject expert who can check the substance, and identify evidence that can be published.
Make the scope clear
Agree the reader, buying question, format, and distribution route for each piece. Set the approval process and distinguish new research from rewriting material you already have.
Check the work in use
Ask a colleague to use the draft in a real buyer conversation. It should answer the question, support its claims, and make the next step clear without requiring a sales pitch to explain it.
Know when to change course
If the same unanswered question appears in several articles, improve the strongest page before commissioning another. More words are not a substitute for missing evidence.
These are discussion points, not a fixed package. GullySales confirms the deliverables, responsibilities, fee, and term in writing after reading your brief and speaking with you.
Before we start
What to have ready before the work starts.
The records, access and decisions this work needs from NBFCs. Anything missing is noted in the written scope, with who will supply it.
- Call notes or recordings of borrower questions
- Share notes from branch calls, with names removed, or recordings you are allowed to use. They show how a borrower phrases a worry. Without them, we write the questions we imagine, and guides answer things nobody is asking.
- Rejection reasons grouped by product
- A simple list of why files were declined, in your own words, shows where a borrower needs help before applying. If the reasons are not recorded, we start recording them in the register, and the topic list builds slowly.
- Time with a credit officer for each product
- Each guide needs a short conversation with the person who knows the product. Without that time, pieces are thin and generic. Please schedule it before writing begins, so the work does not stall mid-draft.
- A named compliance reader
- One person must read every piece before release and may strike lines. Agree the name and the route for sending drafts. If that person is unavailable, publication waits, because loan content published without a read is a risk we will not take.
- Existing partner brochures and sheets
- Send what dealers and DSAs currently receive. We compare it with the new product sheets so the two do not contradict each other. If old brochures carry outdated terms, tell us, and we flag them for withdrawal.
How it works
How the content marketing work runs
The work itself, in order. How an engagement starts, from your brief to a written scope, is set out on our method page.
- 1
Gather the questions behind rejections
We read call notes, rejection reasons and the questions partners ask, with someone from credit. Tell us which questions keep returning. The result is a question bank sorted by loan product, and it decides which guide gets written first, because the strongest topics are the ones that stop files from going forward.
- 2
Choose the first guides with the credit head
From the question bank you select the pieces to write: a document checklist, a plain explanation of how a part-payment works, a guide for a shop owner on what proof of income counts. Each is assigned to a named person in your team who will verify its facts, so a guide never goes out on our reading alone.
- 3
Interview a credit officer for each piece
We speak with the officer who handles that product and write from the answers, in the words a borrower uses. Lending jargon is explained the first time it appears. You supply any internal document we should follow. The draft that comes out reflects how your company actually lends, not a generic loan article.
- 4
Send each draft to credit and compliance
Credit reads for accuracy and compliance reads for promises. Anything suggesting approval is certain is removed. If the regulator's text is relevant we point to it, and we do not copy its wording onto your pages. A piece is released only when both reviewers have signed it.
- 5
Place pieces where borrowers and partners look
Approved pieces go on the product pages, in the branch sheets and in partner messages. Partner product sheets are a separate document, written for the person placing the file. You decide where each piece is published and who receives it. Every piece ends with a way to start an enquiry that is logged in the register.
- 6
Read which pieces led to files
We compare the pieces with the figures recorded at the start: enquiries tagged to a guide, calls where the caller mentioned it, and partner questions that fell. You and the credit head decide which topics to extend or retire. We report what the record shows, and we do not promise traffic.
Where this fits
Three pieces of sales work, in this order.
This work sits inside sales process design, at stage 0, foundation. The audit comes before it, and sales management keeps it running.
Step 1
Sales audit
Find where deals are being lost and what to fix first.
Start here if you cannot say where orders are lost.
Step 2 · you are here
Sales process design
One written way to sell, from first enquiry to repeat order.
Start here if every salesperson sells differently.
Step 3
Sales management
A target, a review routine and someone who owns the number.
Start here if the team has targets and no routine.
FAQ
Questions owners ask before they call.
Not here? More answers, or ask on WhatsApp.
How do we avoid promising approval?
Who writes the content?
Should we publish customer stories?
Can we reuse a regulator's wording on our pages?
Should we publish stories of borrowers we have funded?
To whom does the content belong once written?
How much does it cost?
How long is the contract?
How soon will we see results?
Who will actually do the work?
More for NBFCs
Related work to consider.
Closest to this: content and social
Also for NBFCs
Or start from the overview: sales and marketing for NBFCs.
Your next practical step
Tell us what you are trying to grow, and we will read it before we call.
Eight short steps, mostly taps. Skip anything you would rather answer on the call.