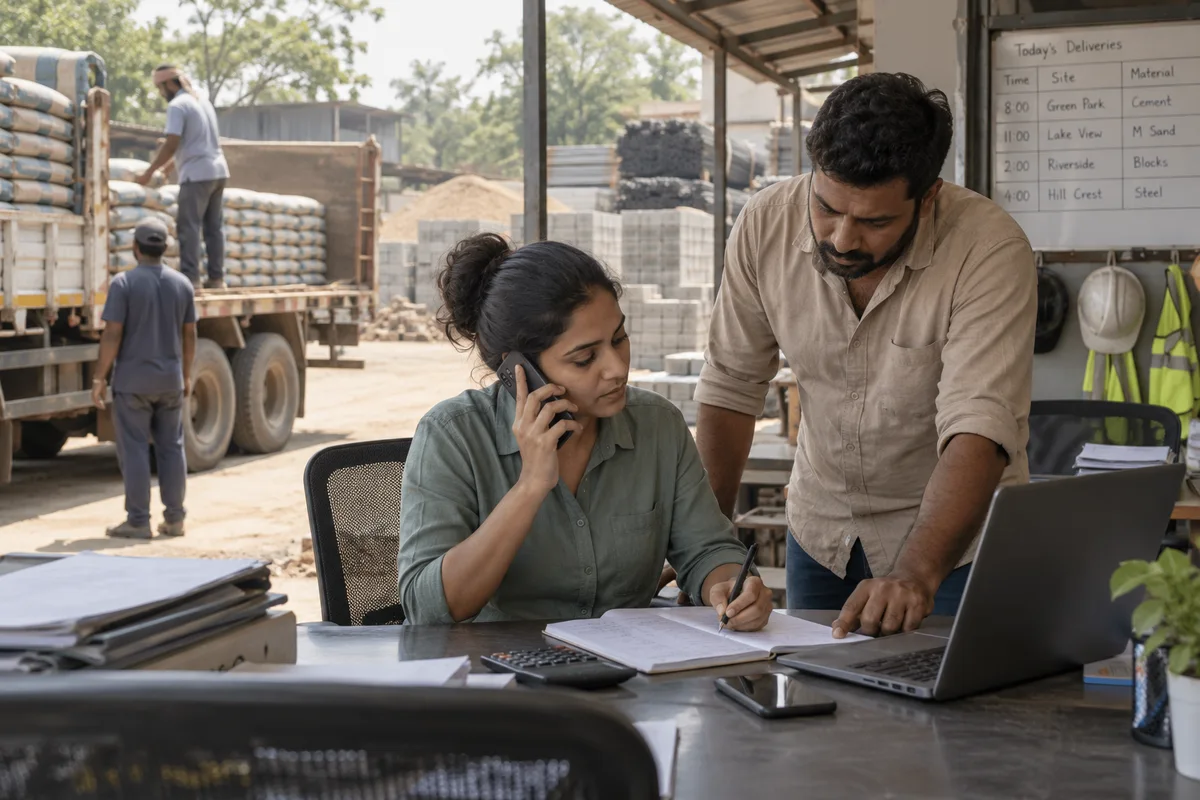
Credit sits with the owner's memory
Who owes what and who is overdue is known to one accountant, so a good buyer waits and a late one is served.
Output to assess: Cross-border order rules
Review whether “Cross-border order rules” addresses this specific issue. Confirm that connection from the example before including the work in the scope.
What to bring
Bring the partner role, agreement, and a sample opportunity or activity record. Confirm that a commercial partner model actually applies.
Proposed completion check
Trace the output back to the selected source record. The reviewer distinguishes confirmed information from assumptions and records any unmet requirement before accepting the handover.