FMCG distributors · Sales profitability analysis
The biggest outlet on your beat may leave less in the till than a small one.
Sales profitability analysis for an FMCG distributor shows which brands, outlets, beats and salespeople leave money after margin, schemes passed on, damaged stock, credit days and the cost of the van. GullySales works from your own Tally books and bill copies and writes the result in plain language.
Scope, fee, reporting and term are agreed in writing after we have read your brief and spoken to you.
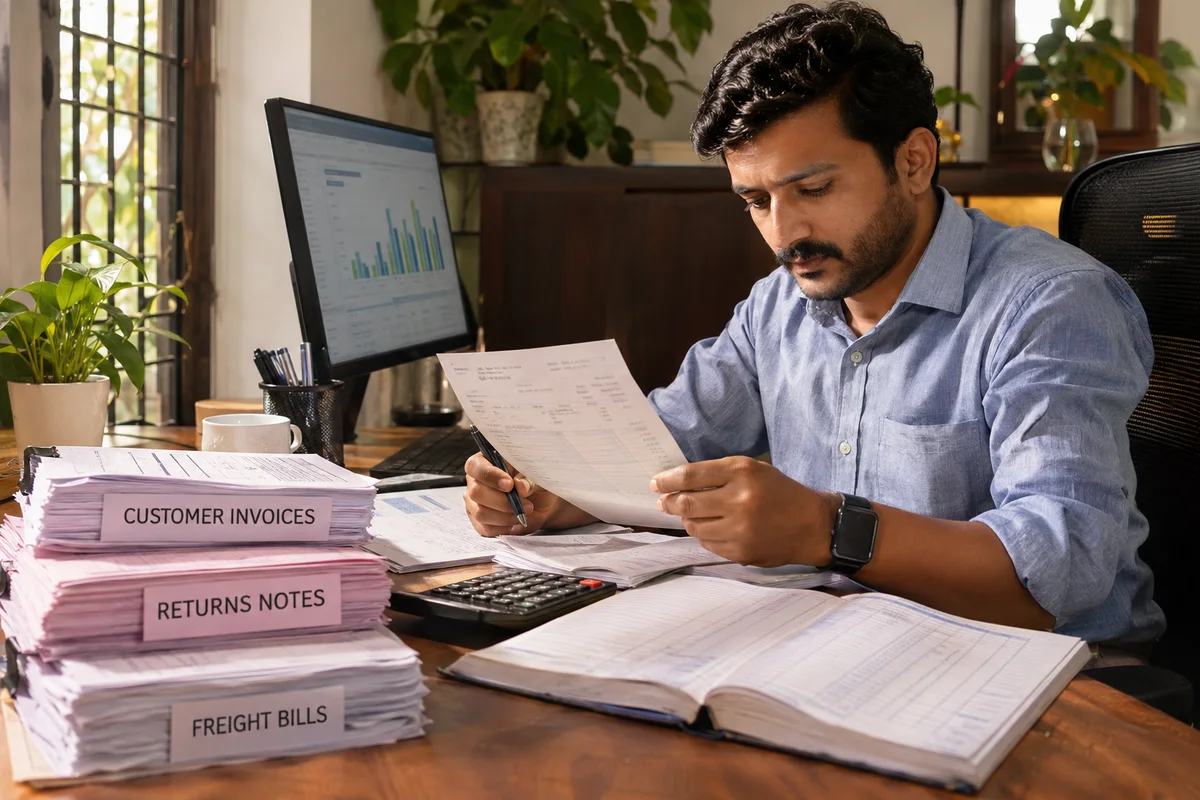
What sales profitability analysis means
Sales profitability analysis shows which products, customers, regions and salespeople leave profit after discounts, credit, returns and the cost of serving them. GullySales works from your own accounts, order by order, and gives you a plain-language report on where the money stays and where it leaks.
Also for FMCG distributors
- Sales discount management for FMCG distributors
- Sales margin improvement for FMCG distributors
- Sales certification programme design for FMCG distributors
- Pricing waterfall and discount leakage analysis for FMCG distributors
- Sales process for FMCG distributors
- Sales management for FMCG distributors
- Sales strategy for FMCG distributors
- Lead generation for FMCG distributors
Sales and marketing for FMCG distributors, the overview.
Last updated 14 Nov 2026.
For FMCG distributors
Where it usually goes wrong, and what we would do.
“Turnover is the company's number, and margin is yours”
The brand rewards turnover and coverage. The godown pays rent, salaries, fuel and interest on stock and credit. A line with heavy turnover but a thin margin and slow-moving stock can cost more to carry than a smaller line that sells off the shelf.
“A large kirana on long credit is a loan”
The owner sees a big bill and a loyal shop. The cost sits elsewhere: money tied up while the shop pays, and the overdue chasing that follows. Set against the margin earned on that account, it may leave very little.
“Damaged cartons and expiry returns land in a different register”
Breakage in the van, a near-expiry return and a missed claim are booked as small adjustments in Tally. Joined back to the outlet and the brand, they show which beats and which products quietly cost the most.
“A salesperson's target is on value, not on what the sale leaves”
If the incentive is paid on invoice value, the salesperson chases bulk lines at the lowest margin. The beat grows on paper while the business keeps less, and nobody has put a margin figure next to the salesperson's name.
What we do
What we deliver for FMCG distributors.
The work available for this need. We agree the deliverables and responsibilities for your engagement in writing.
Margin by brand and product line
A table from your sales and purchase books showing what each company code leaves after scheme pass-through, breakage and expiry returns.
Result: A list of brands ranked by what they leave, with the workings shown.
Outlet profitability sheet
Each retailer's margin set against the credit days they take and the claims or returns linked to them.
Result: You can see which outlets earn their credit and which do not.
Beat and van cost view
Fuel, driver, helper and delivery time laid against the sales on each route, so a route can be judged as a whole.
Result: Each beat has a cost figure beside its sales figure.
Salesperson view
A comparison of salespeople by margin earned, not only value sold, with the outlets and lines behind each.
Result: A page you can bring to a talk about incentive design.
A short read-out for the owner
A written summary of what the books show, which gaps in the records limit the answer and what is worth looking at next.
Result: One document that states findings and limits plainly.
How the result is measured
- Margin by order, product, customer, region and salesperson
- Discount given against list price, by account
- Credit days taken and cash tied up in receivables
Recorded as a baseline before work starts, so every later report has an honest comparison.
Who it is for
This is written for these FMCG distributors.
- Distributors for packaged food, biscuits and snacks brands
- Home and personal care distributors for soaps, detergents and toiletries
- Beverage and bottled water distributors with chilled-outlet coverage
- Staples and edible oil distributors serving wholesalers and kiranas
- Dairy and ice cream distributors with cold-chain vehicles
- Multi-brand FMCG distributors holding four or five company codes
- Super stockists who supply sub-distributors in several towns
- Modern trade and institution suppliers to supermarkets, canteens and hotels
Before you decide
Agree the work. Know how to judge it.
Sales profitability analysis for FMCG distributors: use these checks to prepare, choose the scope, and review what changes.
Bring the right evidence
Bring the current target, pipeline, and review format. Mark which decisions the manager can make and which still require the owner's approval.
Make the scope clear
Agree decision rights and the management routine, including who runs it after the engagement. Separate advice to your sales head from taking responsibility for an agreed part of the operation.
Check the work in use
A useful review ends with an owner and next action for the deals or constraints discussed. Revisit those actions before adding more dashboard measures.
Know when to change course
If a review only collects updates already available in the CRM, shorten it. Use the time to resolve a blocked decision or coach a specific piece of selling work.
These are discussion points, not a fixed package. GullySales confirms the deliverables, responsibilities, fee, and term in writing after reading your brief and speaking with you.
Before we start
What to have ready before the work starts.
The records, access and decisions this work needs from FMCG distributors. Anything missing is noted in the written scope, with who will supply it.
- A full export of sales and purchases
- A season or more of data from Tally, with item, outlet and date. Without it, the analysis covers only the months we can get, and conclusions are weaker. The export should show the invoice number, outlet, item, quantity, rate and scheme line, so we can build every view from one file.
- Records of scheme claims received
- Claims settled by the company affect the true margin. Bring the credit notes. When they are missing, the report shows margin with and without claims, and flags the unknown part. Even a short list of the credit notes received by brand is helpful.
- Damaged stock and expiry return registers
- These sit outside the main books. Bring the registers or the clerk's notes. Missing them overstates margin, and we say so in the report.
- Van and driver cost figures
- Fuel bills, driver pay and maintenance for each vehicle. Approximate numbers are acceptable if you say so. Without them, the beat view shows stops only and no cost. If a single van carries several brands, tell us how you split the cost between them, even roughly, so the brand view does not blame one line for another line's trips.
- A rule on how credit days are counted
- Agree whether credit cost is counted at a rate or not at all. The owner decides. Without a rule, we show credit days separately and leave the money value out.
How it works
How the sales profitability analysis work runs
The work itself, in order. How an engagement starts, from your brief to a written scope, is set out on our method page.
- 1
Agree the questions the owner wants answered
We sit with the owner and list the doubts: which brand earns, which shop costs more than it gives, which beat does not pay for its van. You rank them. The ranking sets the scope, so we spend time on what you will act on. Where the owner wants an answer on one brand only, we say so and keep the scope narrow, since a report that tries to answer everything answers nothing clearly. Questions that need data you do not hold, such as shop-level margin before you began recording returns, are listed as open and carried to the end, so the owner knows what the report cannot say.
- 2
Take the sales and purchase export from Tally
Your billing clerk gives us purchase, sales, scheme and return data in a spreadsheet. We test it by matching totals to the trial balance, and list the entries that do not reconcile. You settle the doubtful items before any analysis starts. Brand codes that changed during the year, outlets renamed after a change of owner and returns posted against the wrong invoice are the common breaks, and we record how each was settled. The log of settled items stays with the report.
- 3
Fix the definitions of margin and cost
We write down how margin is counted: before or after scheme passed on, damaged stock, credit days and van cost. Your accountant reads the definitions and corrects them. Any later number follows these definitions, and a changed definition is logged. Where your accountant counts margin differently, we show both versions side by side for one brand and let the accountant explain the gap. The final definition is written at the top of every sheet.
- 4
Build the margin view by brand and outlet
From the cleaned data we calculate margin by brand and product line, then by outlet. Large kiranas on long credit are shown with the cost of the credit. You see the first table and tell us which results do not match what you expect. Shops with a high order value and a thin margin sit beside shops with small orders and a fat margin, which is the surprise for the owner. We mark outlets where credit days change the answer, and leave the others alone.
- 5
Add the cost of the van and the beat
We take driver wages, fuel, loading staff and the number of stops for each beat. Dividing across the drops gives a cost per stop. You check the van log and fuel records, and tell us where our estimate is wrong. Where a van serves two beats on one run, the cost is split by stops, and we say that on the sheet. A beat that loses on its own but feeds another is marked so you do not close it by mistake.
- 6
Present the owner read-out and the salesperson view
We walk you through a short report: brands, outlets, beats and salespeople. We name what is clear and what rests on thin data. You decide what to act on, and which numbers to recheck next. The salesperson view shows margin on what each person sold, not on what each person was targeted for. It is read in private with the sales head first, and the person is told what the numbers show before anyone else sees them.
Where this fits
Three pieces of sales work, in this order.
This work sits inside sales process design, at stage 1, prospecting and lead generation. The audit comes before it, and sales management keeps it running.
Step 1
Sales audit
Find where deals are being lost and what to fix first.
Start here if you cannot say where orders are lost.
Step 2 · you are here
Sales process design
One written way to sell, from first enquiry to repeat order.
Start here if every salesperson sells differently.
Step 3
Sales management
A target, a review routine and someone who owns the number.
Start here if the team has targets and no routine.
FAQ
Questions owners ask before they call.
Not here? More answers, or ask on WhatsApp.
Do we need clean books before we start?
Is this the same as our accountant's profit and loss?
What do you do with the findings?
Do our books need to be tidy before we start?
Is this the same as the profit and loss account from our accountant?
How much does it cost?
How long is the contract?
How soon will we see results?
Who will actually do the work?
What do you need from us?
More for FMCG distributors
Related work to consider.
Closest to this: sales craft
- Sales discount management for FMCG distributors
- Sales margin improvement for FMCG distributors
- Sales certification programme design for FMCG distributors
- Pricing waterfall and discount leakage analysis for FMCG distributors
- Sales process for FMCG distributors
- Sales management for FMCG distributors
- Sales strategy for FMCG distributors
Also for FMCG distributors
Or start from the overview: sales and marketing for FMCG distributors.
Your next practical step
Tell us what you are trying to grow, and we will read it before we call.
Eight short steps, mostly taps. Skip anything you would rather answer on the call.