Chartered accountants and accounting firms · Lead generation
Lead generation for chartered accountants and accounting firms connects interest to a useful first conversation.
Lead generation for chartered accountants and accounting firms connects interest in your services to an enquiry your team can assess. GullySales plans the capture route for the enquiries your team handles, records the source, and passes the business problem, scope, decision-maker, available information, and intended start to the person responsible for responding.
Scope, fee, reporting and term are agreed in writing after we have read your brief and spoken to you.
What lead generation means
Lead generation is the combined work of every channel that brings in a new enquiry, whether from search, adverts, referrals or a stall at an exhibition. GullySales runs these channels together and reports the number of enquiries each one produced, not the activity behind it.
Also for chartered accountants and accounting firms
- CRM for chartered accountants
- Follow-up systems for chartered accountants
- Inbound marketing for chartered accountants
- Cold email outreach for chartered accountants and accounting firms
- Buyer personas for chartered accountants
- WhatsApp for chartered accountants
- Website for chartered accountants
- Corporate branding for chartered accountants
Sales and marketing for chartered accountants and accounting firms, the overview.
Plan the next part of the work
Last updated 21 Nov 2026. Rules for this trade differ by state and professional body, and they change. We describe restrictions in general terms, so check the current position with your own council or adviser before you publish anything.
For chartered accountants and accounting firms
Where it usually goes wrong, and what we would do.
“A requirement needs a clear next step”
For chartered accountants and accounting firms, check the business problem, scope, decision-maker, available information, and intended start. Do not move the record forward just because a conversation took place.
“Evidence before a commitment”
Use a discovery note confirming the problem and who can approve the proposal as the decision to check. A missing approval should stay visible to the person who can resolve it.
“The receiving team needs the full record”
Check the accepted scope, exclusions, access requirements, and engagement owner before responsibility moves to another person. Record any unresolved question beside its owner.
What we do
What we deliver for chartered accountants and accounting firms.
The work available for this need. We agree the deliverables and responsibilities for your engagement in writing.
Audience and offer brief
A brief connecting the work your team handles to the person commissioning the work and the person approving the engagement. It states which requirements your team accepts and which it cannot serve.
Result: The campaign and the responder use the same definition of a relevant enquiry.
Enquiry page and capture questions
A page and enquiry form asking for the business problem, scope, decision-maker, available information, and intended start. The copy explains the next step without promising an outcome.
Result: The first reply can address the stated requirement.
Source tracking and response handover
A record connecting the enquiry source to its assigned responder and a discovery note confirming the problem and who can approve the proposal. Duplicate and unsuitable enquiries remain identifiable.
Result: Channel totals can be checked against enquiries sales actually accepts.
Source-quality review
Let an enquiry describe the problem before asking for a meeting. A specific brief gives the first conversation a purpose and exposes work outside your expertise. Record rejection reasons and accepted next steps beside each source before changing the channel plan.
Result: Budget decisions use enquiry quality as well as volume.
How the result is measured
- Relevant enquiries by source
- Duplicate and unsuitable enquiries
- Time to the first response
- Accepted enquiries reaching an agreed next step
Recorded as a baseline before work starts, so every later report has an honest comparison.
Who it is for
This is written for these chartered accountants and accounting firms.
- Sole practitioner chartered accountants
- Small and mid-sized CA partnership firms
- Statutory and internal audit practices
- GST and indirect tax specialists
- Company secretaries in practice
- Accounting and bookkeeping service firms
- Firms serving startups and funded companies
- Firms serving NRIs and cross-border clients
- Second-generation practices modernising their client base
Before you decide
When this may not be the right fit.
- A team seeking a guaranteed volume of enquiries or a promised sales result.
- A business unable to provide a responsible owner for enquiries and commercial decisions.
Before you decide
Agree the work. Know how to judge it.
Lead generation for chartered accountants and accounting firms: use these checks to prepare, choose the scope, and review what changes.
Bring the right evidence
Define the organisations or buyers you can serve and the reasons they would consider a conversation. Bring examples of accepted and rejected prospects so the selection rule is visible.
Make the scope clear
Agree the research sources, contact approach, qualification rules, and handover. Clarify which meetings count as accepted and what happens to replies that are not ready to buy.
Check the work in use
Review why a prospect was selected and what was learned from the response. Count held, relevant conversations separately from contacts found, messages sent, or meetings booked.
Know when to change course
If the same objection appears repeatedly, adjust the offer or buyer group before increasing outreach. Respect a request to stop contact and keep the exclusion in the record.
These are discussion points, not a fixed package. GullySales confirms the deliverables, responsibilities, fee, and term in writing after reading your brief and speaking with you.
Before we start
What to have ready before the work starts.
The records, access and decisions this work needs from chartered accountants and accounting firms. Anything missing is noted in the written scope, with who will supply it.
- Recent enquiry records
- Bring anonymised examples of enquiries and their outcomes. Use your existing priorities to select them: Statutory and tax audit; Monthly accounting and bookkeeping retainers; GST registration, returns and notices.
- Decisions and responsibilities
- Identify who speaks to the person commissioning the work and the person approving the engagement, who approves commitments, and who receives the work after acceptance.
- Current selling materials
- Share the forms and messages used to collect the business problem, scope, decision-maker, available information, and intended start. Remove private information that is not needed for the review.
How it works
How the lead generation work runs
The work itself, in order. How an engagement starts, from your brief to a written scope, is set out on our method page.
- 1
Choose the requirement to attract
Start with the enquiries your team handles and agree what your team can supply or support. Define the enquiry acceptance criteria before selecting channels.
- 2
Build and test the enquiry route
Check the journey from the source to the form and assigned responder. Confirm that the business problem, scope, decision-maker, available information, and intended start reaches the right person.
- 3
Review accepted enquiries
Let an enquiry describe the problem before asking for a meeting. A specific brief gives the first conversation a purpose and exposes work outside your expertise. Compare sources using the enquiries the receiving team accepted and the next steps actually taken.
Where this fits
Three pieces of sales work, in this order.
This work sits inside sales process design, at stage 1, prospecting and lead generation. The audit comes before it, and sales management keeps it running.
Step 1
Sales audit
Find where deals are being lost and what to fix first.
Start here if you cannot say where orders are lost.
Step 2 · you are here
Sales process design
One written way to sell, from first enquiry to repeat order.
Start here if every salesperson sells differently.
Step 3
Sales management
A target, a review routine and someone who owns the number.
Start here if the team has targets and no routine.
FAQ
Questions owners ask before they call.
Not here? More answers, or ask on WhatsApp.
Where should chartered accountants and accounting firms start with lead generation?
What should we have ready before discussing the work?
Does this work require a new CRM?
How do we agree the scope and fee?
How long is the contract?
How soon will we see results?
Who will actually do the work?
What do you need from us?
What if we are not happy with the work?
From the blog
Further reading for chartered accountants and accounting firms.
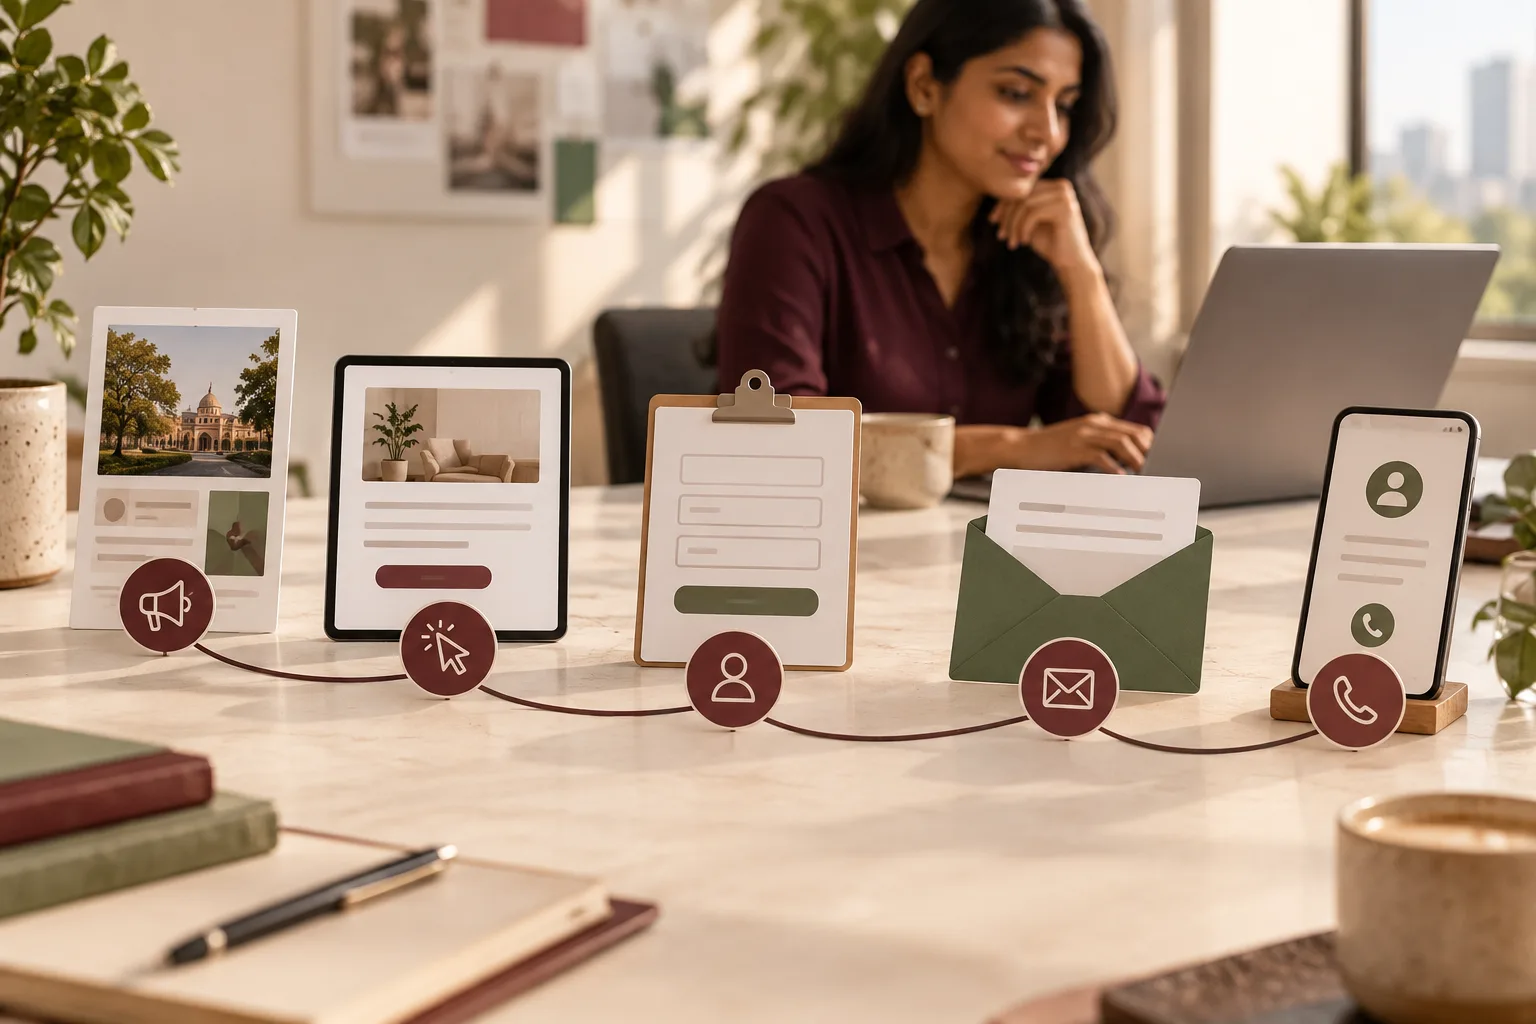 6 min read · 29 May 2026Moving from referrals to a repeatable pipeline: a small firm's second stageHow a small professional firm keeps referrals and adds two sources it controls plus one standing review, so next quarter's work is not left to luck.
 6 min read · 6 Oct 2026How companies choose an outside service firmCompanies pick an outside service firm by asking people they trust. See who is asked, what they check and where a service firm drops off the list.
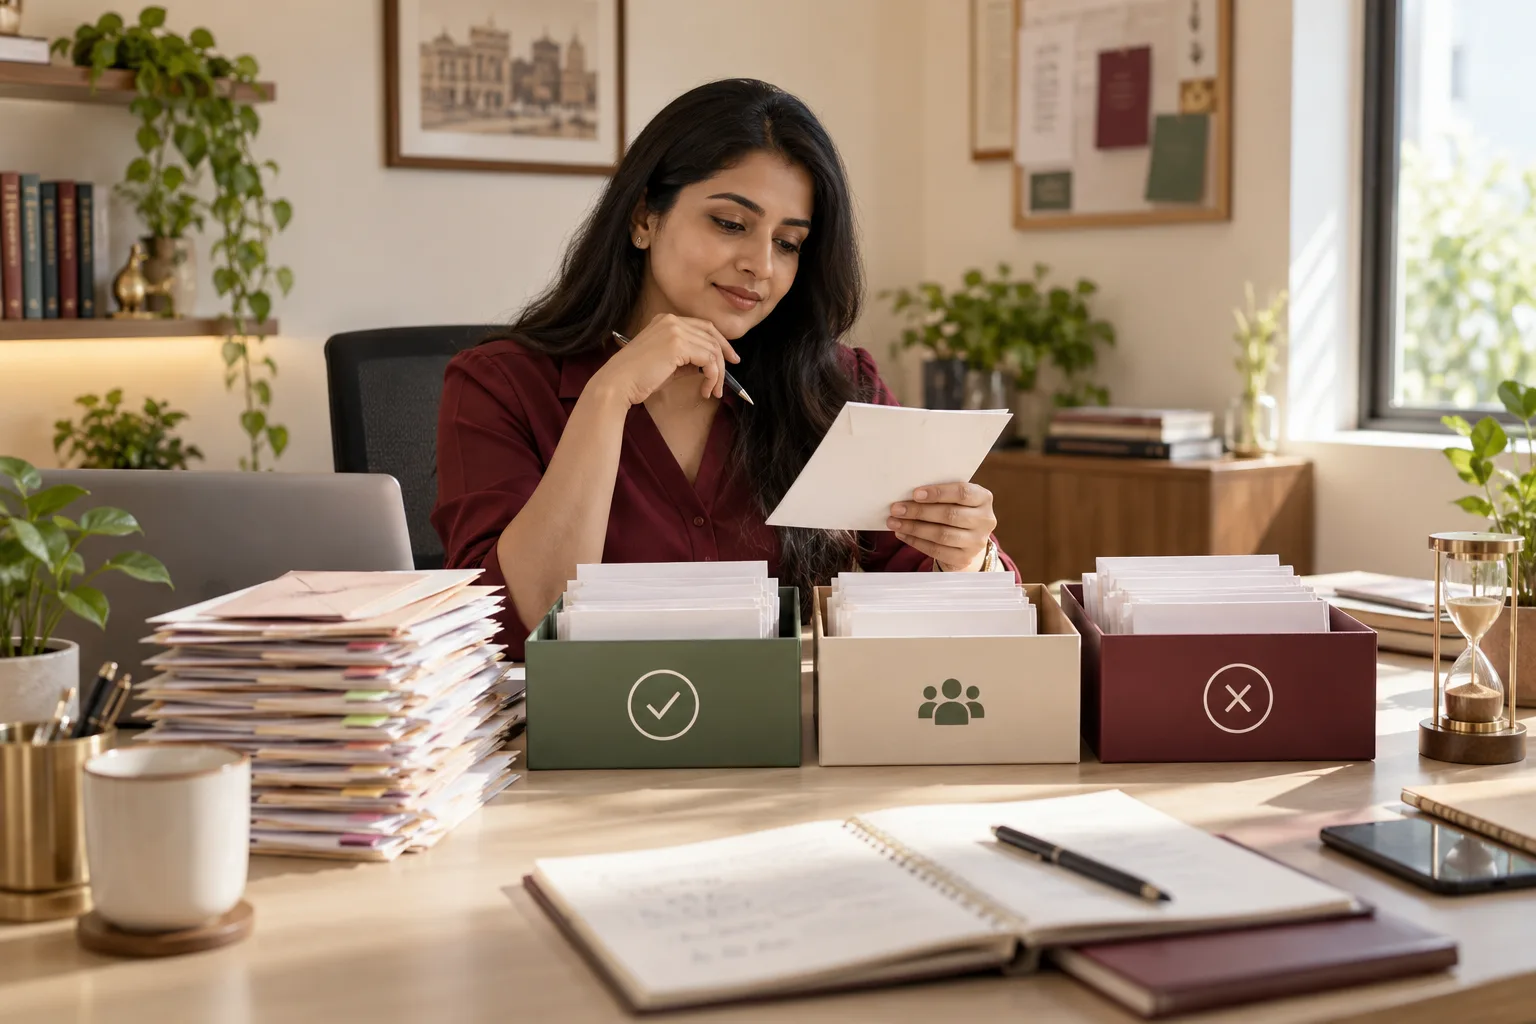 5 min read · 6 Oct 2026How CA firms choose which July enquiries to takeReturn season brings more enquiries than a firm can serve well. Sort them by fit, say no without losing the referral and keep the good ones past the rush.
More for chartered accountants and accounting firms
Related work to consider.
Closest to this: leads and follow-up
Also for chartered accountants and accounting firms
Or start from the overview: sales and marketing for chartered accountants and accounting firms.
Your next practical step
Tell us what you are trying to grow, and we will read it before we call.
Eight short steps, mostly taps. Skip anything you would rather answer on the call.