Notes for owners · Industry playbooks
Why signed-up merchants never take a live payment
Merchants stall between signup and a first live payment at four points: KYC paperwork, site review, integration and silence. Find yours and clear it.
The GullySales team · Updated 13 Nov 2026 · 5 min read
Rules for this trade differ by state and professional body, and they change. Check the current position with your own council or adviser before you act on anything here.
On this page
- Why does a signup mean so little?
- Where do applications actually stall?
- What should you record for each application?
- What can marketing do about each stall?
- For example: a payment gateway and a seller of handloom sarees on Instagram
- Who should reply to a stalled applicant, and in what words?
- What does a merchant need to see on day one?
- How do you help a merchant who has no developer?
- What should the test payment feel like?
- What do you do with the applications that will never go live?
- What about shoppers whose payment failed elsewhere?
- What to do next
Most merchants who sign up and never take a live payment stalled at one of four points: documents they did not have to hand, a website that failed the review, an integration nobody helped them finish, or silence from your side after the form. Which one it is differs from application to application, and most companies cannot tell, because they record signups and nothing after. The fix starts with knowing the stage each application stopped at.
Why does a signup mean so little?
Filling a form costs the merchant two minutes. Taking a first live payment means they have found their documents, passed a review, connected your code or plugin to a real store, and decided to let a customer's money pass through you. Those are different levels of commitment.
A marketing report that says signups rose tells you the advertisement worked. It says nothing about whether any of those people ended up as merchants. The number that matters is the first live payment.
Where do applications actually stall?
Four places, in the order the merchant meets them.
Paperwork. The merchant is asked for business documents, a bank account in the business name, and proof of identity. A small online seller may have some of these in a drawer and some with their CA. The application sits until the missing item turns up, and no one on your side knows that is why.
The website review. Your partner bank and the rules expect a merchant's site to show certain things, such as what is sold, a refund policy, contact details and terms. Rules differ by body and change, so check them with your own compliance adviser. What you can see from the sales side is that a store with no refund page gets rejected, and the merchant is told only that the application did not pass.
The integration. Someone has to put your plugin or API into a real checkout. A developer friend who does this on weekends will do it once and give up if the documentation is behind a login or the error message is unclear.
Silence. After the form, nothing arrives for days. The merchant has already forgotten why they applied, or has signed up with a rival who rang.
What should you record for each application?
One row per application, with a stage and an owner. Not a dashboard, a plain sheet or CRM view that the whole team opens every morning.
| Stage | What it means | Who owns it |
|---|---|---|
| Form filled | Contact details only | Sales |
| Documents received | Merchant sent something | Operations |
| Documents complete | Nothing further to ask | Operations |
| Site reviewed | Passed, or failed with a reason | Compliance |
| Integration started | Sandbox key issued or plugin installed | Support or developer relations |
| First live payment | Real customer, real money | Everyone |
The reason column on the failed rows is where the learning is. After a few weeks of honest entries you will see that most failures sit in one or two stages, and that is where the page, the email or the call needs to go.
What can marketing do about each stall?
It cannot approve anything. It can remove surprises.
For paperwork, publish a plain page listing the documents commonly asked for, written in general terms and approved by your compliance officer, with a line that the final list depends on the partner bank and the rules. For the website review, publish what a merchant's store should show before applying, so they fix it first. For the integration, put the documentation where a developer can read it without signing up. For silence, give every application a named person and a first reply the same day, in the merchant's language, on WhatsApp if that is how they came to you.
Say the uncomfortable part on those pages too. Some merchants will not be approved. A page that says so honestly saves both sides a week.
For example: a payment gateway and a seller of handloom sarees on Instagram
Take a seller in Kanchipuram who takes orders on Instagram and signs up for payment links after a friend recommends your gateway. The seller uploads a photo of the shop licence and stops, because the form asks for a business account and the seller's is personal. Nobody calls. A month later the seller is taking payments through a competitor's link that a cousin set up.
If the application row had a stage and an owner, someone would have seen it sit at documents received on the first morning and rung the seller to say which account is needed and what the options are. That call is not marketing and not sales exactly. It is the work in between, and it is where the money is.
Who should reply to a stalled applicant, and in what words?
The reply should come from a person with a name, not from a no-reply address. Write it the way you would say it across a counter: "Your application is with us. To go further, we need a bank account in the name of your business. If you only have a personal account, here are the choices." Give one next step and one person to answer.
Keep the message in the language the merchant used when they applied. A seller who wrote to you on WhatsApp in Tamil or Kannada does not want a formal email in English. The reply that matches the way the merchant came in is read, and the one that does not is left unopened.
What does a merchant need to see on day one?
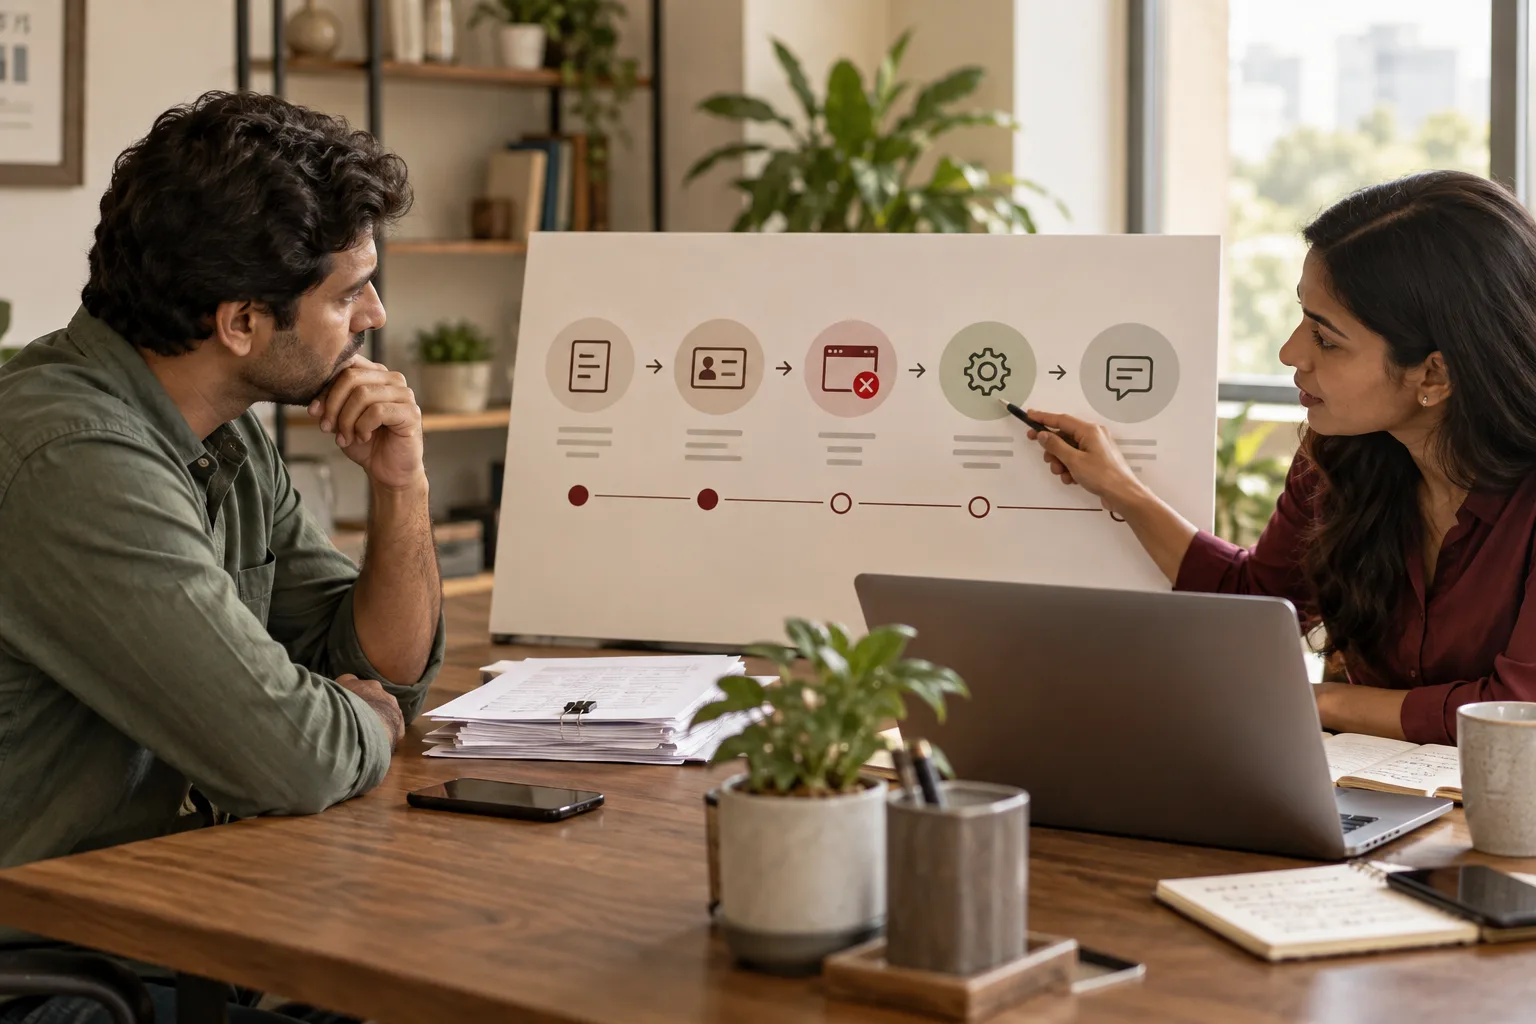
Show the merchant the steps ahead, in order, with a plain mark for the one they are on. Four or five steps are enough: documents, review, connect, test payment, live. A merchant who knows that review comes next does not read a quiet day as a refusal.
Say who looks at each step and where you rely on someone else, such as your partner bank. Do not state how long any step takes, since that depends on others. Say instead that you will tell the merchant the moment it moves, and then do it.
How do you help a merchant who has no developer?
Some small sellers are on a hosted store or a plain order-by-message flow, with no developer at all. A page that begins with an API key loses them in the first line. Offer the route that suits their set-up: a payment link, a plugin for the store platform they already use, or a short guide with screenshots. Ask during the first conversation which platform they sell on, and write it on the row.
If the merchant needs paid help to connect, say so honestly and name the options. Do not leave them to find out after an hour of trying.
What should the test payment feel like?
The test payment is the last step before live, and the merchant is nervous. Walk them through it. Tell them what they will see on screen, what amount to try, where the money will appear and what to do if it does not. Stay on the line or the chat until it works.
A merchant who sees a real payment arrive, even a token amount, has crossed the line from applicant to user. Record that day on the row. It is the first live payment that your marketing spend should be judged against.
What do you do with the applications that will never go live?
Some applications are a poor fit: the business sells something the partner bank will not take, or the merchant has changed their mind. Close them honestly. Tell the merchant it is closed and why, in plain words, and note the reason on the row.
A closed application with a clear reason is worth more than an open one that has gone quiet. It cleans your numbers, and it shows you which kinds of merchant your advertising is attracting that you cannot serve. That is a finding for the marketing brief, and it saves spend.
What about shoppers whose payment failed elsewhere?
If your inbox fills with people whose payment to some other shop failed, tag them in a separate queue and answer them with a short pointer to their own bank or the merchant. Do not let them sit in front of real merchant enquiries. The payment and fintech companies page covers how to keep the two apart.
What to do next
List the last twenty applications that never reached a live payment, and for each one write the stage it stopped at and what the merchant was last told. The gaps in that list are your marketing brief. The sales process page and the content marketing page for your trade show how to turn those gaps into pages and follow-ups. If you want help with how enquiries arrive and what happens to them, tell us what you need and we will read it before we call.
Put the reading to work
Try this with your own records.
Review repeat orders, inactive customers, and reasons for leaving. Separate a normal buying interval from a customer who stopped because of an unresolved problem.
How to review the result
Track the response through to a retained or repeat order, with discounts and service costs visible. Record why the customer returned rather than crediting every repeat purchase to the campaign.