Microfinance companies · Lead scoring
Check the fit before choosing lead scoring.
This service needs a separate suitability and compliance review in this setting. Referral, incentive, outreach, and selling activity must not be applied to individual care or financial decisions by default. Your authorised adviser must define and approve a permissible administrative or business scope first.
Scope, fee, reporting and term are agreed in writing after we have read your brief and spoken to you.
Specialist scope
Confirm the operating model before applying this service to microfinance companies.
This service needs a separate suitability and compliance review in this setting. Referral, incentive, outreach, and selling activity must not be applied to individual care or financial decisions by default. Your authorised adviser must define and approve a permissible administrative or business scope first.
Individual financial advice, suitability, and approval decisions remain with the authorised team. Targets and marketing activity do not replace those assessments.
Consider the underlying work instead.
The context for Microfinance companies
Start with the decisions in your own enquiry records.
Trace a real enquiry across the people and systems involved. Record missing information, duplicate work, and the decision that is still waiting for an owner.
How people choose in this industry
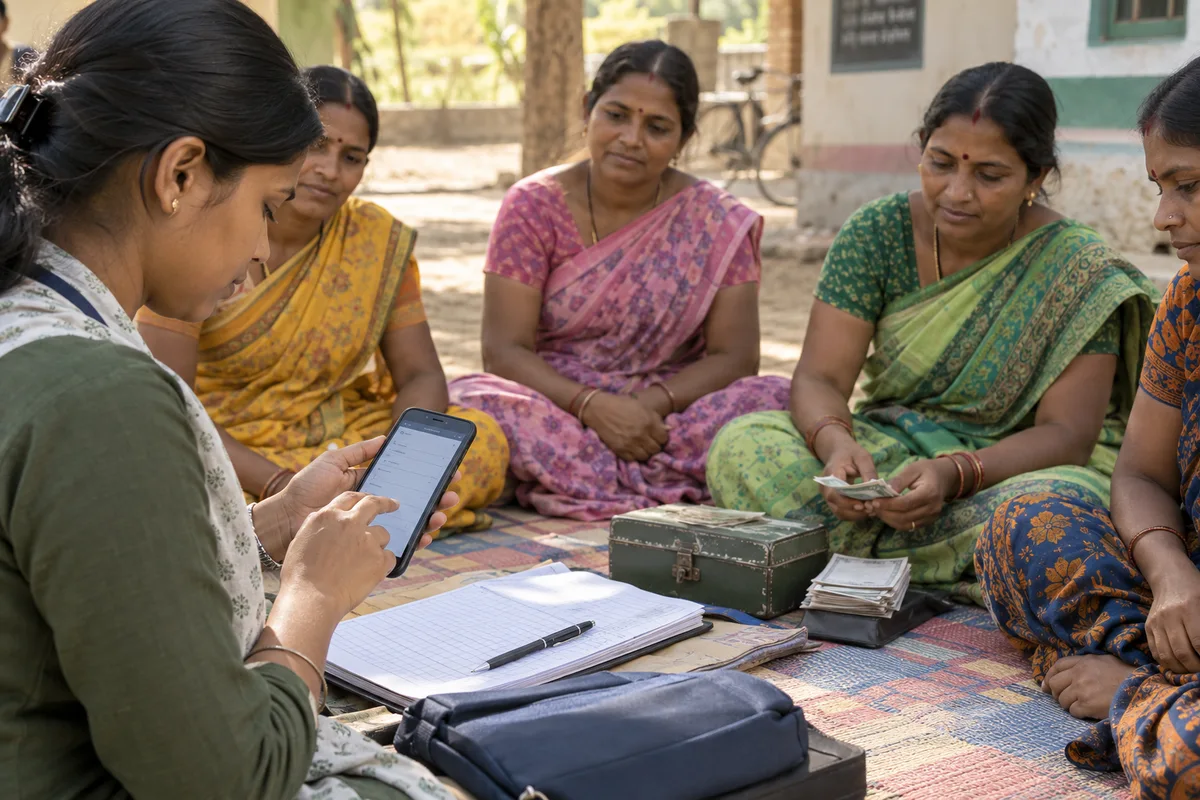
A woman borrower chooses on trust and simplicity. The questions go to the group leader, a neighbour, or the shop owner whose business is funded by the same company: the instalment, the meeting day, who comes to collect, and whether the company treats borrowers fairly if a month goes badly. Product names and rates matter less than who the officer is.
Group leaders and village influencers carry the decision. A leader who has had a good experience brings a new group. One who has had an unkind collection visit tells the whole village.
The sector is regulated in detail, including how loans are priced, disclosed and collected, and the rules change. Check each claim and each message with your compliance head, and use a borrower’s name, photograph or loan story only with written consent.
The decision before implementation
Define the process and access permissions before changing software settings or adding automation.
Existing industry priorities to review
- Group formation in new villages
- Repeat and enhanced loan campaigns to existing borrowers
- Plain-language loan terms in the local language
- Individual business loans for graduating borrowers
- Insurance and other optional add-ons explained clearly
These describe the industry's wider priorities. The written scope identifies which this service will address.
Why the scope is different
Use a service whose responsibilities match your operation.
The specialist programme has its own team, records, and approval requirements. Its name does not establish that the same engagement applies in another industry.
- Manufacturers and dealers handling enquiries with very different order quantities
- B2B sales teams receiving enquiries through IndiaMART, JustDial, website forms, and WhatsApp
- Sales heads whose representatives use different rules for calling priority
- Interior design firms or retailers separating serious project enquiries from early browsing
- Owners with recorded won and lost enquiries, but an unexplained or unused CRM score
FAQ
Questions owners ask before they call.
Not here? More answers, or ask on WhatsApp.
How is lead scoring scoped for microfinance companies?
What should we confirm before considering this service?
What if this programme does not fit our operation?
Continue your review
Compare the service scope and the related work.
The scope, responsibilities, fee, reporting frequency, and term are agreed in writing after the requirements brief and conversation. Tell us what you need.
Your brief
Tell us what you need, and we will read it before we call.
Eight short steps about your business, what you want and who decides. Most questions are a tap, and you can skip any you would rather answer on the call.