Microfinance companies · Follow up systems
Make sure a household that said maybe hears from the company again.
A follow-up system for a microfinance company is the routine that brings an officer back to every interested household, group and repeat borrower on the day agreed. GullySales builds the reminders and the record, and your staff make the visit and the call.
Scope, fee, reporting and term are agreed in writing after we have read your brief and spoken to you.
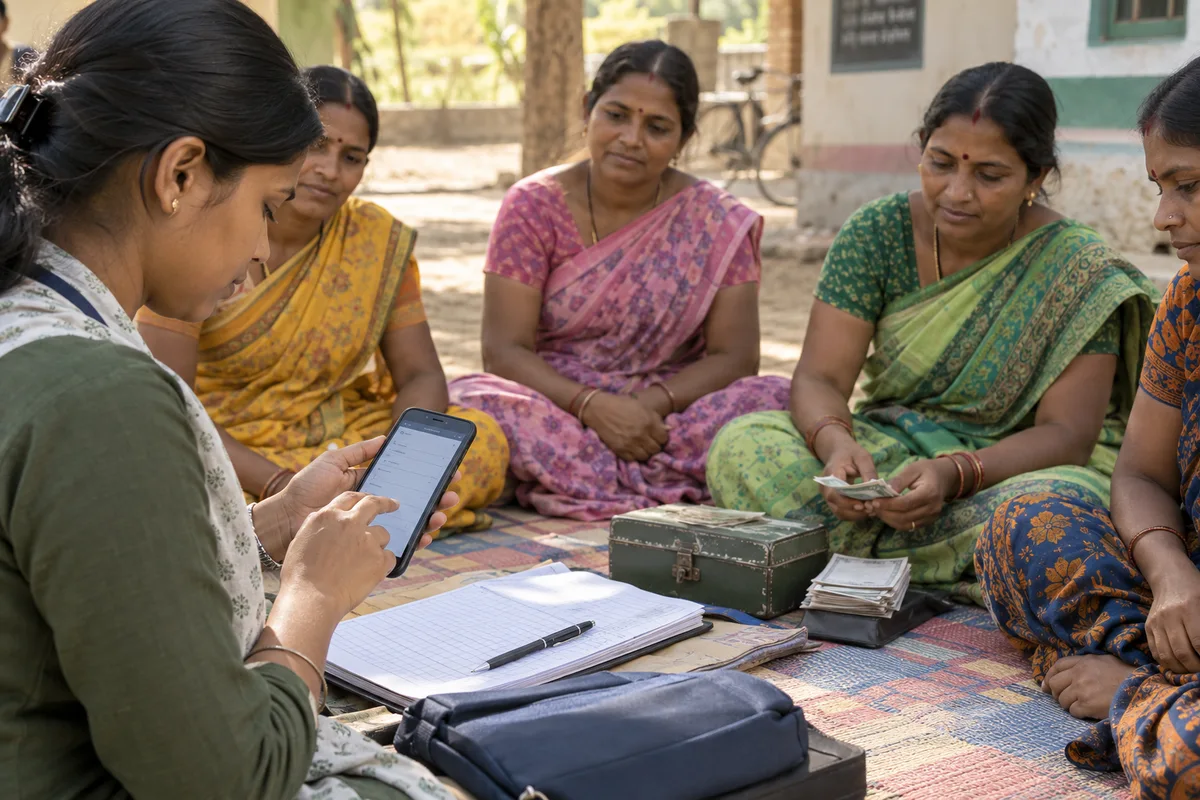
What follow up systems means
A follow-up system is the set routine for calling, messaging or emailing an enquiry more than once, since most buyers do not decide on the first conversation. GullySales sets the number and timing of follow-ups so an undecided buyer keeps hearing from you until they decide either way.
Also for microfinance companies
- Lead generation for microfinance companies
- CRM for microfinance companies
- SEO for microfinance companies
- Local SEO for microfinance companies
- Social media marketing for microfinance companies
- Content marketing for microfinance companies
- Buyer personas for microfinance companies
- WhatsApp marketing for microfinance companies
Sales and marketing for microfinance companies, the overview.
Last updated 14 Nov 2026. Rules for this trade differ by state and professional body, and they change. We describe restrictions in general terms, so check the current position with your own council or adviser before you publish anything.
For microfinance companies
Where it usually goes wrong, and what we would do.
“Maybe is an answer every officer knows”
A household says come after the harvest or after the festival. If no one records the date, the promise is gone and a rival lender's officer arrives first.
“Group formation needs several touches”
One meeting rarely forms a group. The leader needs a second visit, the members need the terms explained again and the family needs reassurance. Each step needs an owner and a date.
“Follow-up must never become pressure”
A borrower who is reminded too hard about a loan may take on debt the household cannot carry. The system sets who contacts whom and stops where your lending policy says it must.
What we do
What we deliver for microfinance companies.
The work available for this need. We agree the deliverables and responsibilities for your engagement in writing.
Follow-up dates in the field record
Every interested household or group gets a next-visit date and a named officer.
Result: The branch manager sees what is due and who owns it.
Visit-and-call routine
A simple order of visit, call and message for a lead from first interest to group formed.
Result: Each lead has a known next step.
Repeat-loan conversation list
A list of borrowers whose repayment is on track, prompting an officer conversation after the company's own checks.
Result: Returning borrowers hear about the next loan from the company.
Language message templates
Short reminder messages in the district language, cleared by compliance.
Result: Messages are polite, correct and consistent.
Overdue follow-up review
A review of follow-ups that passed their date, by branch.
Result: Missed promises are visible and discussed.
How the result is measured
- Follow-up completion rate
- Average number of follow-ups before close
- Enquiries closed after repeat follow-up
Recorded as a baseline before work starts, so every later report has an honest comparison.
What to capture or send
Moments that need a second visit or a message.
- A household that said they would ask the family
- Record who must agree and the date the officer will return. The reminder reaches the officer, not the household.
- A group short of members
- Record how many are in and who has promised to bring others. The officer returns to the leader, who is best placed to complete the group.
- A group formed but not yet through training
- Record the step outstanding and the person who owns it. A formed group left waiting may lose the women who joined.
- A repeat-loan conversation due
- A prompt to the officer to speak to the returning borrower on the borrower's schedule, noting any problem with the last loan.
- A lead that went quiet
- Record the last contact and one line on why. The branch manager decides whether to visit once more or close it with a reason.
Who it is for
This is written for these microfinance companies.
- NBFC-MFIs working through joint liability groups
- Self-help group linkage lenders
- Microfinance companies in rural Karnataka and neighbouring states
- Urban microfinance for small shopkeepers and home-based workers
- Small finance bank microfinance arms
- Microfinance companies adding individual business loans
- Women's livelihood and dairy-linked lenders
- Company branches opening in a new taluk
Before you decide
When this may not be the right fit.
- Officers are transferred between branches and the old notes are not handed over, so the reminders would reach someone who never met the household.
- You expect the system to chase repayments, when collections stay with your staff and your rules.
- No one reviews the overdue follow-ups at the branch, so the list would only grow.
Before you decide
Agree the work. Know how to judge it.
Follow-up systems for microfinance companies: use these checks to prepare, choose the scope, and review what changes.
Bring the right evidence
Trace recent enquiries from arrival to the last recorded action. Include a won enquiry, an unsuitable one, and one that went quiet, with personal details removed for the initial discussion.
Make the scope clear
Agree who accepts each enquiry, what makes it qualified, and how ownership changes. Include a rule for missed replies and a clear reason for closing an enquiry.
Check the work in use
Pick an enquiry at random and ask the team to find its owner, latest conversation, and next action. Check that the record agrees with what actually happened.
Know when to change course
If no one has capacity to respond, assign that responsibility before buying more leads. Automation can support the owner, but it cannot replace an unresolved handover.
These are discussion points, not a fixed package. GullySales confirms the deliverables, responsibilities, fee, and term in writing after reading your brief and speaking with you.
Before we start
What to have ready before the work starts.
The records, access and decisions this work needs from microfinance companies. Anything missing is noted in the written scope, with who will supply it.
- Enquiry sheets or diaries for recent cycles
- We need to see households that said maybe and what followed. Photographs with names covered are acceptable. Without them, the baseline is built from officers' memory and is less exact, which weakens the final comparison.
- The branch manager's time for the overdue list
- The routine only works if a manager looks at the overdue list and speaks to the officer. Decide who does it, and when it fits in the manager's day. If nobody does, the reminders become noise, and officers learn to ignore them.
- The rule on returning to a household
- Your compliance head must say how many returns to a household are acceptable and when to stop, since a household visited again and again after a clear no is being pressed and not followed up. We write the routine to that rule, and the record closes the household on the officer's tap. Without it, we set one visit and one call, then closure, and you may extend it.
- A feed of cycle-end dates from the loan system
- The repeat-loan list needs only group name, village and cycle-end date. Ask your IT person to export it. If an export is not possible, the branch clerk can type it, and the list is then only as fresh as the typing.
- Message wording in each branch language
- Give us the phrases officers already use for a second visit and for a no, including the polite ways a household says it will think. We start from them, because a script that sounds foreign gets dropped at the first doorstep. When we write them ourselves, the officer has to rewrite them, and we both lose the benefit of a ready routine.
How it works
How the follow up systems work runs
The work itself, in order. How an engagement starts, from your brief to a written scope, is set out on our method page.
- 1
Look at what happens after a maybe
We go through the enquiry sheets, the diary notes and the group register with the branch manager, and mark each household that said it would think. We then ask how many were visited again and who decided. This shows where the loop breaks: sometimes the officer forgets, sometimes the group is told to wait. You choose which break to mend first.
- 2
Sort the reasons households give for waiting
We sit with officers and list the real reasons: the husband is away, the festival is near, the neighbour had a bad experience, the amount is too small. Each reason gets a next step that is not pressure. You approve the list. The reasons become the choices the officer taps on the record, and no free-text note is needed.
- 3
Write the second visit and the call
We write a short script for the second visit and another for a phone call, in the district's language, with a plain opening, one question and a way out for the household. Officers try them on us. Your compliance head reads them, and a household that says no is thanked and the record is closed without a third visit.
- 4
Put the dates into the field record
Each time an officer marks a household as thinking, the record asks for the next visit date and sets a reminder on the officer's phone. We test that the reminder arrives with no signal and appears in the morning list. The branch manager sees the list of overdue visits, with an officer's name beside each and the reason the officer gave, so the first question at review is what stood in the way.
- 5
Add the repeat-loan list
We build a list of borrowers nearing the end of a cycle, from the loan system and without balances, so that the officer talks about the next loan before the group closes. You decide which cycle ends are shown. The list reaches the officer as names and villages only, and the officer carries it on the visit.
- 6
Read the follow-up against the baseline
We return to the maybe list from the first step and compare how many of those households now have a recorded second visit, a group formed or a recorded no. We read the overdue list with the manager. You decide which routine to keep. We report what the record shows and promise no extra groups.
Where this fits
Three pieces of sales work, in this order.
This work sits inside sales process design, at stage 2, qualification. The audit comes before it, and sales management keeps it running.
Step 1
Sales audit
Find where deals are being lost and what to fix first.
Start here if you cannot say where orders are lost.
Step 2 · you are here
Sales process design
One written way to sell, from first enquiry to repeat order.
Start here if every salesperson sells differently.
Step 3
Sales management
A target, a review routine and someone who owns the number.
Start here if the team has targets and no routine.
FAQ
Questions owners ask before they call.
Not here? More answers, or ask on WhatsApp.
Does this include collections reminders?
What if an officer leaves?
Can follow-up be automatic?
How many times should an officer go back to a household?
Should an unhappy former borrower be followed up?
How do we stop the reminders turning into targets for the officers?
How much does it cost?
How long is the contract?
How soon will we see results?
Who will actually do the work?
More for microfinance companies
Related work to consider.
Closest to this: leads and follow-up
Also for microfinance companies
Or start from the overview: sales and marketing for microfinance companies.
Your next practical step
Tell us what you are trying to grow, and we will read it before we call.
Eight short steps, mostly taps. Skip anything you would rather answer on the call.