Microfinance companies · WhatsApp marketing
Use WhatsApp for what a village family actually reads: short voice and picture notes.
WhatsApp marketing for a microfinance company means the messages the company sends to group leaders, enquirers, recruits and returning borrowers, with their agreement. GullySales sets up the business number, the approved templates and the rules on what is sent, and your staff reply.
Scope, fee, reporting and term are agreed in writing after we have read your brief and spoken to you.
What WhatsApp marketing means
WhatsApp marketing is sending updates, offers and reminders to customers on the app most Indian buyers already check daily. GullySales sets up business WhatsApp, writes the message templates and keeps the list consented and current.
Also for microfinance companies
- Lead generation for microfinance companies
- SEO for microfinance companies
- Local SEO for microfinance companies
- Social media marketing for microfinance companies
- Content marketing for microfinance companies
- Buyer personas for microfinance companies
- CRM for microfinance companies
- Follow-up systems for microfinance companies
Sales and marketing for microfinance companies, the overview.
Last updated 14 Nov 2026. Rules for this trade differ by state and professional body, and they change. We describe restrictions in general terms, so check the current position with your own council or adviser before you publish anything.
For microfinance companies
Where it usually goes wrong, and what we would do.
“Group leaders already run WhatsApp groups”
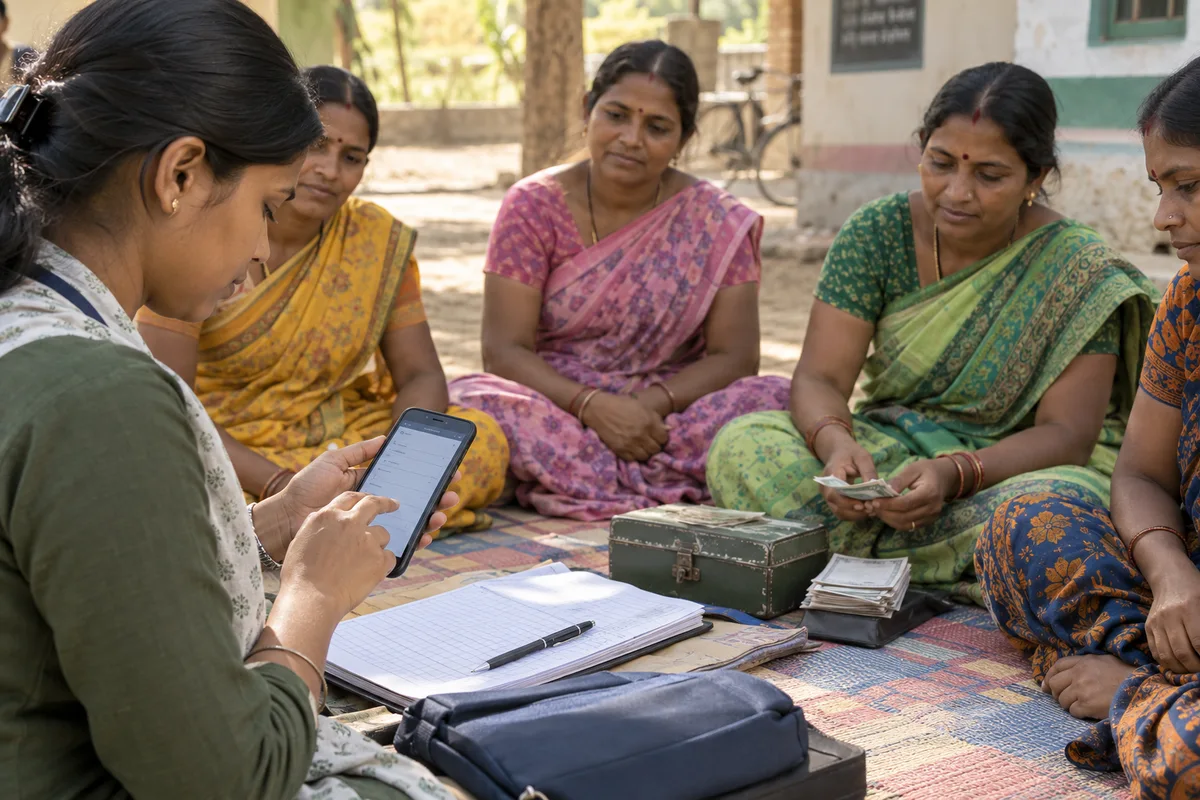
A leader coordinates members through a phone group. A company message that reaches the leader in the leader's language, with an officer's voice, travels further than a printed notice.
“A voice note is read where text is not”
Some members cannot read well. A short voice note from a known officer explaining a meeting date or a product works better than a paragraph. It must be checked and approved, like any other message.
“Unwanted messages cost trust”
A borrower who gets promotional messages nobody asked for will block the number and talk about it. Permission, a clear stop and a limit on how frequently anyone is messaged protect the relationship.
What we do
What we deliver for microfinance companies.
The work available for this need. We agree the deliverables and responsibilities for your engagement in writing.
Business number and profile
A WhatsApp Business number with the company name, address and description set correctly.
Result: A recipient sees a verifiable company, not an unknown number.
Approved message templates
Meeting reminders, product explanations and hiring replies in the district language, cleared by compliance.
Result: Staff send consistent, approved wording.
Permission and opt-out routine
A clear way to record who agreed to receive messages and who asked to stop.
Result: Nobody is messaged against their wish.
Officer reply guide
A short guide on replying to enquiries and what never goes on chat, such as loan decisions or personal financial details.
Result: Sensitive matters move to a visit or a call.
Enquiry-to-record link
Chat enquiries entered into the field record with the source noted.
Result: A WhatsApp enquiry becomes a followed-up lead.
How the result is measured
- Messages delivered
- Reply rate
- Enquiries from WhatsApp
Recorded as a baseline before work starts, so every later report has an honest comparison.
What to capture or send
Messages that suit a leader's group and a recruit's phone.
- Meeting reminder to a group leader
- A short voice note in the district language giving the place and time. The leader passes it on, and the officer need not phone each member.
- Documents needed for the next visit
- A picture-led list of what to keep ready. The officer sends it after agreeing a visit, and the household has something to show the family.
- Reply to an enquiry from a missed call
- A polite message from the company number asking the village and language, then naming the officer who will call back.
- Job openings for field officers
- A poster with the district, the role and the way to apply, posted to groups of recruits who asked to hear about vacancies.
- Opt-out confirmation
- A one-line reply when someone asks to stop. It records the request in the sheet so no officer sends that number a further message.
Who it is for
This is written for these microfinance companies.
- NBFC-MFIs working through joint liability groups
- Self-help group linkage lenders
- Microfinance companies in rural Karnataka and neighbouring states
- Urban microfinance for small shopkeepers and home-based workers
- Small finance bank microfinance arms
- Microfinance companies adding individual business loans
- Women's livelihood and dairy-linked lenders
- Company branches opening in a new taluk
Before you decide
When this may not be the right fit.
- Your officers share their own mobile numbers with borrowers, so the history would leave with the officer on transfer.
- You plan to send loan balances or repayment dues on chat, which are personal financial details and do not belong there.
- No household has agreed to receive messages, so the first broadcast would reach people who never asked for it.
Before you decide
Agree the work. Know how to judge it.
WhatsApp marketing for microfinance companies: use these checks to prepare, choose the scope, and review what changes.
Bring the right evidence
Describe how the contact list was collected, what people asked to receive, and which messages are currently sent. Include opt-outs and replies when reviewing campaign performance.
Make the scope clear
Agree the audience, message purpose, sending system, and response owner. Separate promotional communication from order or service updates, and check current platform requirements before launch.
Check the work in use
Test the message with a small appropriate audience before wider use. Check links, reply handling, opt-outs, and whether the response leads to a relevant conversation or order.
Know when to change course
Do not use an unexplained contact list as a shortcut to demand. If recipients do not expect the message, resolve the permission and relevance questions before sending.
These are discussion points, not a fixed package. GullySales confirms the deliverables, responsibilities, fee, and term in writing after reading your brief and speaking with you.
Before we start
What to have ready before the work starts.
The records, access and decisions this work needs from microfinance companies. Anything missing is noted in the written scope, with who will supply it.
- A SIM and device owned by the company
- The business number must belong to the company and sit on a device that stays with the branch or head office. If an officer's personal number is used, it leaves with that officer. We set up only on a company number.
- Screenshots of current groups with details covered
- We need to see how the groups look today: size, who posts, what is sent. Cover every name and number. Without screenshots, we ask officers to describe them, and the plan is a little less firmly based on practice.
- Your compliance head's list of what may be sent
- Tell us what may and may not appear in a message to a borrower or enquirer. We use it to write and test every template. If the list is not ready, we limit messages to meeting times and welcomes.
- Consent records for existing contacts
- Show us how consent to be messaged was taken, if at all. Where it was not, we do not message those contacts, and the first list is small. We then build the consent habit so that the list grows honestly.
- One leader who will read the draft messages
- A group leader should read the drafts and say whether a village woman would understand and trust them. Choose someone respected who reads the language. Without a leader's read, wording is checked only by staff, and staff hear the words as the company says them rather than as a village hears them. Tell us whom you would trust to give an honest answer.
How it works
How the whatsapp marketing work runs
The work itself, in order. How an engagement starts, from your brief to a written scope, is set out on our method page.
- 1
Read how staff already use WhatsApp
We ask officers and managers to show us the groups and chats they already use with leaders and enquirers, with borrower details covered. We see what gets read, what is ignored and where personal numbers carry company business. You decide which of those habits the company will keep. Everything we build later starts from that picture.
- 2
Choose the number and the tool
We discuss with you whether the company uses the plain business app or the business platform with approved templates. For a handful of branches the app is enough, and for broader reach the platform is needed. You choose, and we explain what each allows. The number is registered to the company and not to an officer.
- 3
Write the permission and opt-out routine
We write the line an officer speaks or the box a household ticks to agree to messages, and the way to stop them, in the local language. Your compliance head approves the wording. Each agreement is recorded with the date and the source. A contact without a record is not messaged, whoever supplied the number.
- 4
Draft the templates with the leaders in mind
We write short messages: a meeting reminder, a welcome to a new group, a note that the officer is coming. A group leader reads each draft and tells us how it lands. Voice-note scripts are recorded by an officer. Nothing about a balance, an offer or a due date goes in a template until compliance has cleared it.
- 5
Route replies to the right officer
We decide which replies reach which person, using the village and the officer on the record. A reply asking about a balance is handed to the branch, and a complaint goes to the grievance route. We test with five real messages, including one that arrives in a voice note and one in a language the branch does not use. You name who answers when the officer is on leave, so no reply waits unseen, and the branch manager sees any reply that stays unanswered.
- 6
Read the replies against the old habit
We compare the messages sent, the replies, the opt-outs and the visits arranged with the picture from the first step. We ask the leaders if the messages were useful. You decide which templates to keep or drop. We report what the record shows and promise no extra enquiries.
Where this fits
Three pieces of sales work, in this order.
This work sits inside sales process design, at stage 0, foundation. The audit comes before it, and sales management keeps it running.
Step 1
Sales audit
Find where deals are being lost and what to fix first.
Start here if you cannot say where orders are lost.
Step 2 · you are here
Sales process design
One written way to sell, from first enquiry to repeat order.
Start here if every salesperson sells differently.
Step 3
Sales management
A target, a review routine and someone who owns the number.
Start here if the team has targets and no routine.
FAQ
Questions owners ask before they call.
Not here? More answers, or ask on WhatsApp.
Can we send loan offers by WhatsApp?
Should officers use their own numbers?
Can we share loan balances on chat?
Should we make WhatsApp groups for each borrower group?
Can group leaders keep running their own WhatsApp groups?
What if an enquirer sends photos of identity documents on chat?
How much does it cost?
How long is the contract?
How soon will we see results?
Who will actually do the work?
More for microfinance companies
Related work to consider.
Or start from the overview: sales and marketing for microfinance companies.
Your next practical step
Tell us what you are trying to grow, and we will read it before we call.
Eight short steps, mostly taps. Skip anything you would rather answer on the call.