Microfinance companies · Social media
Use social media to show who the company is, in the languages the borrowers speak.
Social media for a microfinance company is a place where families, recruits and partners check that the company is real and respectable. GullySales plans a modest set of posts around field life, hiring and plain explanations, cleared by your compliance head.
Scope, fee, reporting and term are agreed in writing after we have read your brief and spoken to you.
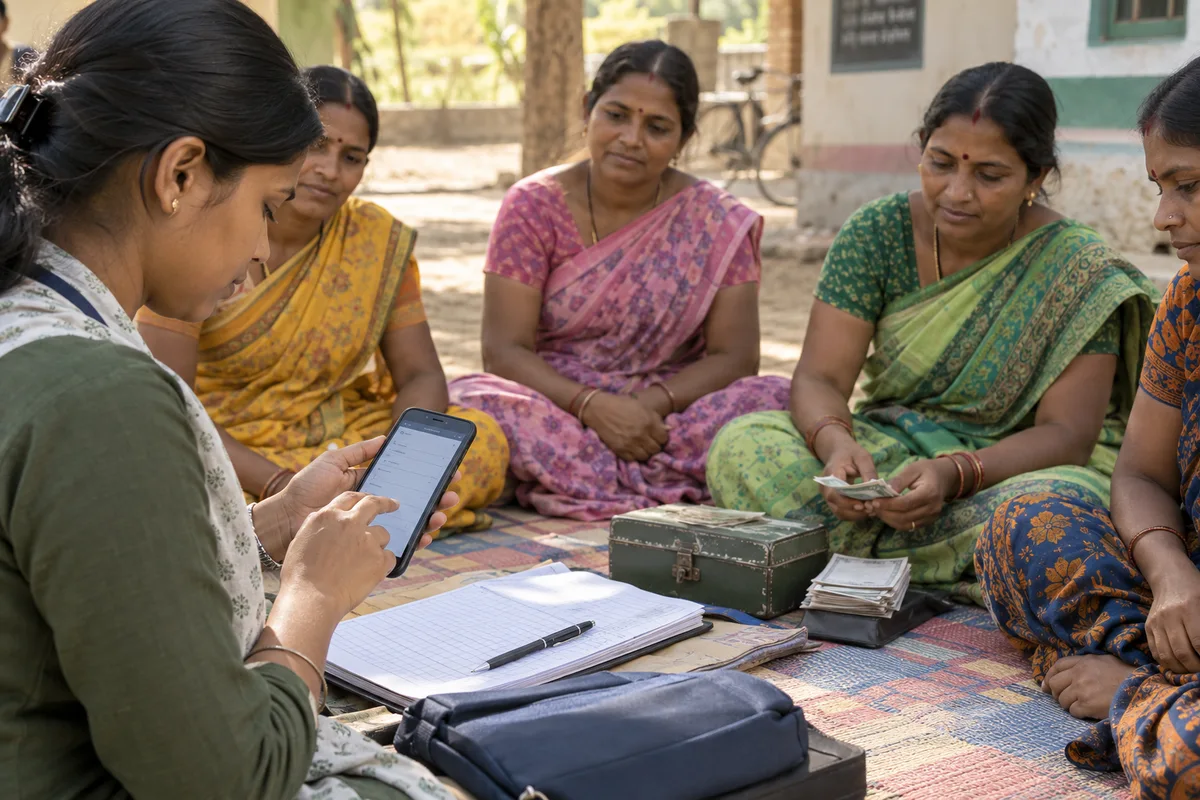
What social media means
Social media is the ongoing posting your business does on platforms such as Instagram, Facebook and LinkedIn to stay visible to customers and prospects between purchases. GullySales plans a posting calendar, writes captions and designs the images so the page looks active and answers what a visitor would ask.
Also for microfinance companies
- Content marketing for microfinance companies
- Lead generation for microfinance companies
- SEO for microfinance companies
- Local SEO for microfinance companies
- Buyer personas for microfinance companies
- CRM for microfinance companies
- Follow-up systems for microfinance companies
- WhatsApp marketing for microfinance companies
Sales and marketing for microfinance companies, the overview.
Last updated 14 Nov 2026. Rules for this trade differ by state and professional body, and they change. We describe restrictions in general terms, so check the current position with your own council or adviser before you publish anything.
For microfinance companies
Where it usually goes wrong, and what we would do.
“The audience includes the borrower's children”
A daughter or son with a smartphone looks up the company their parent is joining. A calm, correct page reassures the family more than any pamphlet.
“Hiring posts do more than loan posts”
Field officer vacancies reach graduates on social platforms far better than village households. A post showing a real day on the field, with consent from staff, attracts the right kind of applicant.
“A joyful repayment photo is a risk”
Pictures of borrowers with loan amounts or cheques can embarrass them or invite pressure. Posts need written consent and nothing that identifies a household's debt or business to neighbours.
What we do
What we deliver for microfinance companies.
The work available for this need. We agree the deliverables and responsibilities for your engagement in writing.
Page set-up and profile check
Profiles on the platforms you use with correct name, branches, contact and grievance route.
Result: A family checking the company finds consistent details.
Plain-language explainer posts
Short posts in the district language explaining a product's instalment, fee and insurance as your policy states.
Result: Terms are stated once, clearly, outside the meeting.
Field-life and staff posts
Posts about officers and branch teams with their consent, never showing borrowers' loan details.
Result: The company looks like real people, not a logo.
Hiring post series
Posts for officer vacancies by district, with the real work described.
Result: Applicants arrive knowing what the job involves.
Approval route
Each post goes through your compliance head before it is published.
Result: Nothing is posted that your team has not cleared.
How the result is measured
- Posts published
- Engagement rate
- Enquiries from social profiles
Recorded as a baseline before work starts, so every later report has an honest comparison.
Posts and pieces to plan
Posts a family and a recruit would both be glad to see.
- How a joint liability group works
- A short illustrated post in the district language, showing the meeting, the shared responsibility and the leader's role. It needs your compliance head's sign-off before it goes up.
- A branch opening in a new taluk
- A photograph of the office and the officers, with the address and the languages spoken. No borrower appears unless the household has agreed in writing.
- A day with a field officer
- A video or photo series of the walk to the village and the meeting. It proves the staff are real, and it draws applicants for the officer role.
- Where to take a complaint
- A pinned post stating the grievance route in plain words, so a family that finds the page after a problem knows where to go before they post publicly.
- Savings and account-keeping habits
- A simple picture guide a borrower can screenshot. It teaches a habit and makes no promise about income or repayment.
Who it is for
This is written for these microfinance companies.
- NBFC-MFIs working through joint liability groups
- Self-help group linkage lenders
- Microfinance companies in rural Karnataka and neighbouring states
- Urban microfinance for small shopkeepers and home-based workers
- Small finance bank microfinance arms
- Microfinance companies adding individual business loans
- Women's livelihood and dairy-linked lenders
- Company branches opening in a new taluk
Before you decide
When this may not be the right fit.
- No one at head office can approve a post before it goes live, so a careless line about a loan could reach a borrower's family.
- You want social media to form village groups, when those households are reached by the officer's visit and the leader's word.
- Your only content idea is a repayment celebration photograph, which exposes borrowers who have not agreed to be shown.
Before you decide
Agree the work. Know how to judge it.
Social media marketing for microfinance companies: use these checks to prepare, choose the scope, and review what changes.
Bring the right evidence
Review the posts that produced useful conversations, not only the ones with the most views. Gather buyer questions and decide which team member can contribute credible material.
Make the scope clear
Choose the audience and channel before setting a posting volume. Agree who supplies material, approves posts, and handles messages, including complaints or questions the agency cannot answer.
Check the work in use
Follow a post through to the profile, website, and response. A useful report explains the quality of conversations and enquiries, alongside reach and engagement.
Know when to change course
If publishing takes time away from unanswered buyer messages, fix the response routine first. Do not expand to another channel without a clear reason for being there.
These are discussion points, not a fixed package. GullySales confirms the deliverables, responsibilities, fee, and term in writing after reading your brief and speaking with you.
Before we start
What to have ready before the work starts.
The records, access and decisions this work needs from microfinance companies. Anything missing is noted in the written scope, with who will supply it.
- Admin access to every company page
- We need the admin role, not a password, on each page. Ask the person who created the page to add us. Pages with no known admin cannot be edited, and we list them so you can ask the platform to help or start new ones.
- Signed consent for any borrower image
- If a borrower, a leader or a family member is to appear in a photograph or video, a signed consent in the language they read must be on file. Without it, no such image is used, and the posts feature officers, bicycles, forms and places instead.
- A shortlist of officers who will appear
- Pick officers who are comfortable being photographed and whose families agree. Their role, not their home, is shown. If nobody volunteers, the posts use objects and places, and the feel of the page is more formal.
- The compliance head's list of never-post items
- Tell us what must never appear: rates, offers, repayment photographs, collection scenes, political content. We keep it beside the approval route. When this list is missing, we apply the strictest reading and post fewer items.
- A person to answer comments and messages
- Someone from the branch or head office must read the comments and messages and reply, or hand them to the grievance route. We do not reply for the company on matters of a loan. With nobody assigned, we switch off comments where the platform allows.
How it works
How the social media work runs
The work itself, in order. How an engagement starts, from your brief to a written scope, is set out on our method page.
- 1
Look at what each page already shows
We open the company's pages on Facebook, YouTube and Instagram on an ordinary phone and read them as a recruit's parent would. We note old posts that mention rates or offers, borrower photographs posted without clear consent, and pages created by past staff. You tell us which belong to the company. The tidy-up list that follows is yours to approve before anything is deleted.
- 2
Agree who may post and who clears
With your compliance head we write the approval route: who drafts, who clears each post, and who may reply to a comment. The head of operations names the officers who may appear in photographs. We agree a rule that no borrower appears without a signed consent held on file. The route is one page, and every post follows it.
- 3
Spend a day in the field for material
We go on a field visit with an officer and the leader's permission, and take photographs of the officer, the bag of forms, the bicycle or bike and the meeting place, but not the borrowers. We listen to how the officer explains the loan. These visits give the posts their subject, and you decide what is fit to show.
- 4
Draft the explainers in the borrower's language
We write each explainer post in the district's language and in short sentences, such as what a meeting day is and who the officer is. A field officer reads each draft aloud and corrects the words. Your compliance head clears them. We do not post a rate, an offer or a repayment story, because each needs separate clearing.
- 5
Plan the hiring posts around the branches
The branch manager tells us which branches are short of officers. We write hiring posts that describe the day of a field officer in plain terms, the travel, the training and the documents needed. Sharing is aimed at the district around that branch. You decide which branches get a post and who answers the applicants.
- 6
Compare the page with its starting point
We read the page's followers, the shares of the hiring posts and the messages received against the note we made in the first step. We add the enquiries and applicants your branches record that mention the page. You see the figures beside the old ones, and we advise on what to repeat. We promise no reach, because the platform decides who sees a post.
Where this fits
Three pieces of sales work, in this order.
This work sits inside sales process design, at stage 0, foundation. The audit comes before it, and sales management keeps it running.
Step 1
Sales audit
Find where deals are being lost and what to fix first.
Start here if you cannot say where orders are lost.
Step 2 · you are here
Sales process design
One written way to sell, from first enquiry to repeat order.
Start here if every salesperson sells differently.
Step 3
Sales management
A target, a review routine and someone who owns the number.
Start here if the team has targets and no routine.
FAQ
Questions owners ask before they call.
Not here? More answers, or ask on WhatsApp.
Which platform matters for a microfinance company?
Can we advertise loans on social media?
Should officers post from personal accounts?
Should we reply to comments from unhappy borrowers?
Can the officers share the company's posts from their own accounts?
What do we do about a bad comment from an unhappy borrower?
How much does it cost?
How long is the contract?
How soon will we see results?
Who will actually do the work?
More for microfinance companies
Related work to consider.
Closest to this: content and social
Also for microfinance companies
Or start from the overview: sales and marketing for microfinance companies.
Your next practical step
Tell us what you are trying to grow, and we will read it before we call.
Eight short steps, mostly taps. Skip anything you would rather answer on the call.