Microfinance companies · Content marketing
Publish the explanations a borrower's family reads before signing anything.
Content marketing for a microfinance company means writing and recording the plain answers a household, a group leader or a recruit looks for. GullySales produces them in the district's language, with your field staff checking the words and your compliance head clearing the content.
Scope, fee, reporting and term are agreed in writing after we have read your brief and spoken to you.
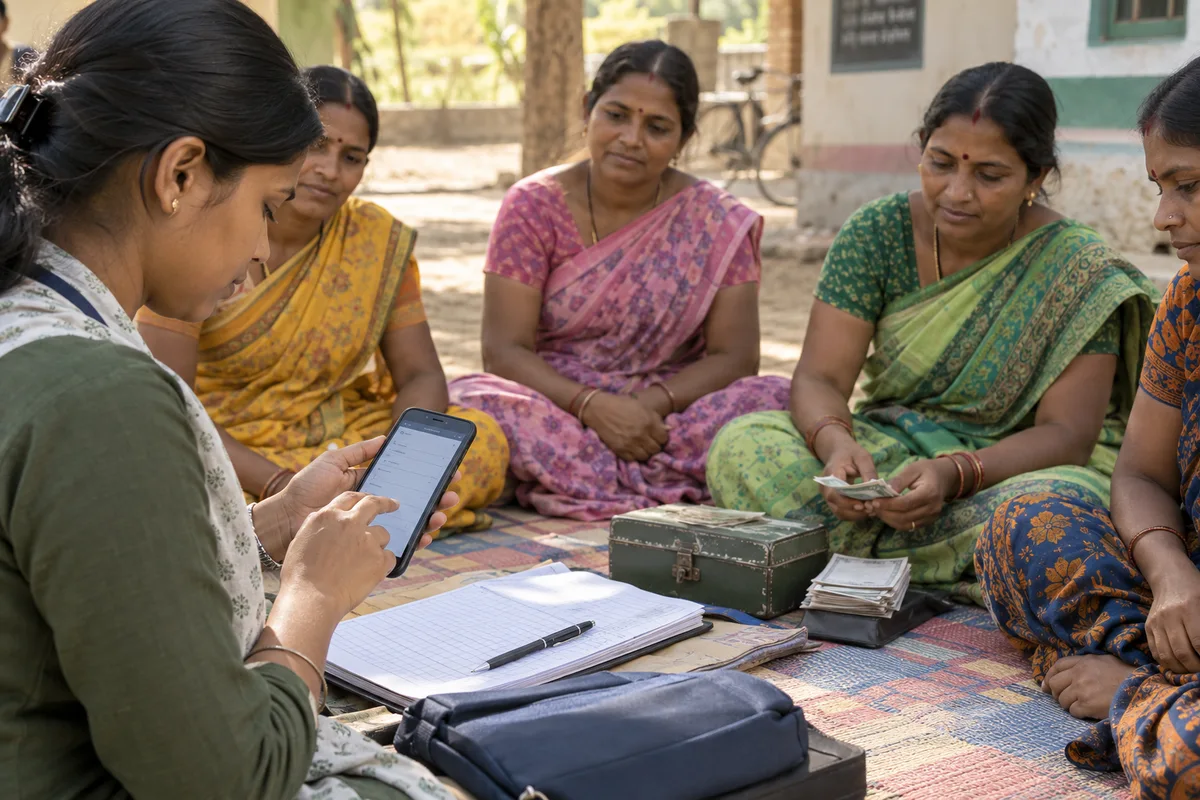
What content marketing means
Content marketing is writing articles, guides and pages that answer the questions buyers search before they are ready to enquire. This makes your business visible and trusted before the first call. GullySales plans this content from the first conversation onward, choosing topics that match real search demand rather than guesses.
Also for microfinance companies
- Social media marketing for microfinance companies
- Lead generation for microfinance companies
- SEO for microfinance companies
- Local SEO for microfinance companies
- Buyer personas for microfinance companies
- CRM for microfinance companies
- Follow-up systems for microfinance companies
- WhatsApp marketing for microfinance companies
Sales and marketing for microfinance companies, the overview.
Last updated 14 Nov 2026. Rules for this trade differ by state and professional body, and they change. We describe restrictions in general terms, so check the current position with your own council or adviser before you publish anything.
For microfinance companies
Where it usually goes wrong, and what we would do.
“Terms explained once are forgotten”
The instalment, fee and insurance are spoken at the meeting and fade by the next meeting. A printed sheet or a short voice note in the home language gives the household something to check against.
“Money habits are the content borrowers use”
Guides on keeping a simple daily account for a tiny shop or dairy are read. A guide that avoids pushing a loan builds more goodwill than another product leaflet.
“Video must suit shared phones”
A short clip played at a group meeting or sent on WhatsApp works where a long article does not. It needs captions and a voice in the local dialect, and a person known to the group.
What we do
What we deliver for microfinance companies.
The work available for this need. We agree the deliverables and responsibilities for your engagement in writing.
Product explainer sheets
One sheet per loan in the district language covering instalment, fee, insurance and the grievance route.
Result: Households keep a clear record of what was explained.
Simple account-keeping guide
A one-page guide to recording daily income and expenses for a small business.
Result: A borrower has a tool that is useful without a loan.
Short voice or video explainers
Brief clips for group meetings, voiced by staff known in the district.
Result: The meeting shows the same explanation to every group.
Hiring and day-in-the-field stories
Articles and clips about the officer's role, with consent from staff.
Result: Applicants understand the job before applying.
Content calendar and review path
A list of topics with a clear route through your field staff and compliance head.
Result: Everything published has been read by the right people.
How the result is measured
- Pages published
- Organic traffic
- Enquiries from content pages
Recorded as a baseline before work starts, so every later report has an honest comparison.
Posts and pieces to plan
Pieces that answer what a household asks before signing.
- What the group is responsible for
- A one-page sheet and a voice note in the district language, explaining joint responsibility plainly. The leader reads it aloud at the meeting.
- What the borrower pays and when
- A fee and instalment explainer built from the terms your policy publishes. The compliance head approves the numbers, and GullySales invents none.
- Keeping a small shop's accounts
- A picture-led guide for a vegetable seller or tailor: one notebook, money in and out. It sells nothing and carries the company name in small print.
- The repeat loan, step by step
- A short piece for returning borrowers describing what the officer will ask and what the group must have done. It makes no promise of a higher amount.
- Why women join as officers
- A staff story told in the person's own voice, recorded with consent. It is aimed at recruits and the families who decide whether a daughter can take the job.
Who it is for
This is written for these microfinance companies.
- NBFC-MFIs working through joint liability groups
- Self-help group linkage lenders
- Microfinance companies in rural Karnataka and neighbouring states
- Urban microfinance for small shopkeepers and home-based workers
- Small finance bank microfinance arms
- Microfinance companies adding individual business loans
- Women's livelihood and dairy-linked lenders
- Company branches opening in a new taluk
Before you decide
When this may not be the right fit.
- Your field staff have no time to check the local-language words, so the pieces would use phrases that no borrower in the district speaks.
- The only content planned is a set of income success stories, which carries a claim your compliance head will not clear.
- Borrowers have no phone to play a video on, and no one has yet planned the printed sheet that the leader would read out.
Before you decide
Agree the work. Know how to judge it.
Content marketing for microfinance companies: use these checks to prepare, choose the scope, and review what changes.
Bring the right evidence
Bring questions from sales calls and examples of objections that delay a decision. Choose a subject expert who can check the substance, and identify evidence that can be published.
Make the scope clear
Agree the reader, buying question, format, and distribution route for each piece. Set the approval process and distinguish new research from rewriting material you already have.
Check the work in use
Ask a colleague to use the draft in a real buyer conversation. It should answer the question, support its claims, and make the next step clear without requiring a sales pitch to explain it.
Know when to change course
If the same unanswered question appears in several articles, improve the strongest page before commissioning another. More words are not a substitute for missing evidence.
These are discussion points, not a fixed package. GullySales confirms the deliverables, responsibilities, fee, and term in writing after reading your brief and speaking with you.
Before we start
What to have ready before the work starts.
The records, access and decisions this work needs from microfinance companies. Anything missing is noted in the written scope, with who will supply it.
- The loan agreement and repayment schedule
- Give us the sample documents a borrower signs and the schedule the borrower is handed. Every explainer takes its facts from them. Where the documents differ across products, tell us which governs, or the explainer covers one product only.
- A branch room and a quiet hour for recording
- Recording needs a room with no fan or traffic noise and an officer free to read the script. Choose a room with a door that closes. If none exists, the notes are recorded as written text with a printed sheet instead.
- Field officers who speak the local language well
- Two or three officers who explain the loan clearly in the district's language must check our drafts. They should be people borrowers trust. Without them, the writing may be correct but not natural, and the borrower will notice.
- A written view on borrower stories
- Decide whether any borrower story may be used, and under what consent. We write none unless you give the consent form and your compliance head approves the text. In its absence the content explains and teaches without stories.
- A list of the languages for each branch
- Tell us which language each branch and each centre needs. Every piece is made in the first language of the district before others. If the list is unknown, we begin with the language the larger share of your borrowers speak at the largest branch.
How it works
How the content marketing work runs
The work itself, in order. How an engagement starts, from your brief to a written scope, is set out on our method page.
- 1
Collect the questions households really ask
We sit with field officers and ask which questions come up at the doorstep and at the centre meeting: the instalment, the meeting day, what happens if one member cannot pay, who keeps the passbook. We write each question as the borrower says it, in the district language. These become the list of topics, and you cross out any you would rather not answer in public.
- 2
Pick the form for each answer
For each question we decide with you whether it is a printed sheet, a voice note, a short film or a poster for the centre wall. A borrower who cannot read needs the voice note, and the family that shares one phone needs a small file. You choose the first three to make, and we hold the rest on the list.
- 3
Take the facts from the loan documents
We read the loan agreement, the repayment schedule and the borrower's passbook, and list each fact that an answer will state. Your product head confirms each one. We do not write a figure, a charge or a term that is not in those documents. If a document is unclear, the question goes back to you before any text is written.
- 4
Draft in the language and read it aloud
We write the sheets and scripts in short sentences, then read them aloud to a field officer and, with permission, to a group leader. Anything that sounds like head office is rewritten in the words they use. Your compliance head clears the final version, and no piece is released that has not been cleared.
- 5
Record voice and film at the centre
For the voice notes and short films we use your own staff and a quiet room at the branch, with a phone and a clip-on microphone. Borrowers do not appear. We check each file plays on a low-end phone and sends over WhatsApp. You listen to every file before it leaves the branch.
- 6
Return to the questions and read the response
After the content has reached the officers and centres, we go back to the list of questions and ask the officers which still come up at the doorstep. We add the enquiries and applicants the branches record. You see these against the list we made in the first step, and decide which answers to extend. We promise no response, since that depends on the village and the season.
Where this fits
Three pieces of sales work, in this order.
This work sits inside sales process design, at stage 0, foundation. The audit comes before it, and sales management keeps it running.
Step 1
Sales audit
Find where deals are being lost and what to fix first.
Start here if you cannot say where orders are lost.
Step 2 · you are here
Sales process design
One written way to sell, from first enquiry to repeat order.
Start here if every salesperson sells differently.
Step 3
Sales management
A target, a review routine and someone who owns the number.
Start here if the team has targets and no routine.
FAQ
Questions owners ask before they call.
Not here? More answers, or ask on WhatsApp.
Can we publish borrower success stories?
Who writes in the local language?
Does content help if borrowers cannot read?
Which language do we write in first?
Who checks that the explainers are correct before they go out?
Can the same content be used in the next state, in another language?
How much does it cost?
How long is the contract?
How soon will we see results?
Who will actually do the work?
More for microfinance companies
Related work to consider.
Closest to this: content and social
Also for microfinance companies
Or start from the overview: sales and marketing for microfinance companies.
Your next practical step
Tell us what you are trying to grow, and we will read it before we call.
Eight short steps, mostly taps. Skip anything you would rather answer on the call.