Payment and fintech companies · Lead generation
Count the merchant who took a first live payment, not the one who filled the form.
Lead generation for a payment or fintech company is bringing in sellers and finance teams worth a sales conversation and following them from signup to the first live transaction. GullySales sorts enquiries by true source, chases applications stuck in KYC, and measures merchants live instead of forms filled.
Scope, fee, reporting and term are agreed in writing after we have read your brief and spoken to you.

What lead generation means
Lead generation is the combined work of every channel that brings in a new enquiry, whether from search, adverts, referrals or a stall at an exhibition. GullySales runs these channels together and reports the number of enquiries each one produced, not the activity behind it.
Also for payment and fintech companies
- CRM for payment and fintech companies
- Follow-up systems for payment and fintech companies
- SEO for payment and fintech companies
- Content marketing for payment and fintech companies
- PPC ads for payment and fintech companies
- Email marketing for payment and fintech companies
- Buyer personas for payment and fintech companies
- Sales process for payment and fintech companies
Sales and marketing for payment and fintech companies, the overview.
Plan the next part of the work
Last updated 21 Nov 2026. Rules for this trade differ by state and professional body, and they change. We describe restrictions in general terms, so check the current position with your own council or adviser before you publish anything.
For payment and fintech companies
Where it usually goes wrong, and what we would do.
“A signup is not a lead until the documents arrive”
Most self-serve signups stall at PAN, GST or bank proof. Counting them as leads hides the real queue, which is applications nobody is chasing.
“Students, shoppers and job seekers fill your forms too”
A contact form attracts people wanting a refund, a job or a free API key for a college project, and they crowd out the merchant who wrote in the same hour.
“Partner and reseller leads have no owner”
A bank officer, an ERP vendor or a web agency passes a merchant to you, nobody records who sent whom, and the partner never hears what happened.
What we do
What we deliver for payment and fintech companies.
The work available for this need. We agree the deliverables and responsibilities for your engagement in writing.
Lead sources defined and recorded
Website signup, sales call, partner referral, plugin listing, event and inbound WhatsApp each logged in the CRM with where the merchant came from.
Result: You know which door brings live merchants.
A qualified lead written down
Business type, platform in use, payment methods wanted and papers ready, agreed with sales before any lead is counted.
Result: Nobody argues about the number at the end of the quarter.
A tracker for applications stuck in onboarding
A named person contacts every application stopped at a missing document, with a short list of what is needed and a note in the record.
Result: A merchant who stalled gets help instead of silence.
A filter for the wrong enquiries
Refund complaints, job applications and support questions routed to the right inbox with an automatic reply linking to help pages.
Result: Sales sees merchants only.
A partner referral register
Each partner, the merchants they sent, the status of each, and a note back to the partner, kept in the CRM.
Result: Partners keep sending merchants because they hear what happened.
Report against the baseline
Signups, KYC completed, merchants live and first payments by source, set against the baseline recorded before work began.
Result: You can see which source brings merchants who actually trade.
How the result is measured
- Relevant enquiries by source
- Duplicate and unsuitable enquiries
- Time to the first response
- Accepted enquiries reaching an agreed next step
Recorded as a baseline before work starts, so every later report has an honest comparison.
Where enquiries come from
The ways a merchant or finance head reaches a payment company, and what to record when each arrives.
- Self-serve signup on the website
- Record the time, the page they came from and the stage reached. Send a message listing the papers needed, and mark the application stuck if none arrive.
- A call to the sales line
- Note the caller's business, platform and what prompted the call, and ask what they use now. Send the document list on WhatsApp straight after, and log the call.
- A message on the business WhatsApp number
- Treat it as a lead only if it is about accepting payments. Reply as a person, record the number, and move refund and support questions to the support inbox.
- A plugin or app-store listing
- Tag every signup with the platform it came from. A developer who installs a plugin and stalls needs a setup guide, not a sales call.
- A referral from a bank officer, accountant or web agency
- Log the referrer and the merchant together, and tell the referrer how the application ended, so they keep sending merchants your way.
- An enterprise request from a procurement form
- Record the company, who asked and which review is pending: security, legal or finance. Reply with the response folder, and note who owns each answer.
Who it is for
This is written for these payment and fintech companies.
- Payment gateways and aggregators for online sellers
- UPI and QR providers with soundboxes and card machines for shops
- Prepaid wallet and card issuers working with a partner bank
- Digital lenders and buy-now-pay-later apps working with a bank or NBFC
- B2B payment, vendor payout and payables platforms
- Payroll, expense and corporate card tools for companies
- Cross-border payment and remittance platforms
- Neobanks and current account apps for startups and small businesses
Before you decide
When this may not be the right fit.
- Your onboarding team already holds a queue of merchants waiting for review, so more signups would only lengthen it.
- You cannot tell which signups took a first live payment, so a new source could not be judged.
- Your product is not yet approved by the partner bank for the merchants you would target.
Before you decide
Agree the work. Know how to judge it.
Lead generation for payment and fintech companies: use these checks to prepare, choose the scope, and review what changes.
Bring the right evidence
Define the organisations or buyers you can serve and the reasons they would consider a conversation. Bring examples of accepted and rejected prospects so the selection rule is visible.
Make the scope clear
Agree the research sources, contact approach, qualification rules, and handover. Clarify which meetings count as accepted and what happens to replies that are not ready to buy.
Check the work in use
Review why a prospect was selected and what was learned from the response. Count held, relevant conversations separately from contacts found, messages sent, or meetings booked.
Know when to change course
If the same objection appears repeatedly, adjust the offer or buyer group before increasing outreach. Respect a request to stop contact and keep the exclusion in the record.
These are discussion points, not a fixed package. GullySales confirms the deliverables, responsibilities, fee, and term in writing after reading your brief and speaking with you.
Before we start
What to have ready before the work starts.
The records, access and decisions this work needs from payment and fintech companies. Anything missing is noted in the written scope, with who will supply it.
- The signup export with dates and statuses
- A sheet of everyone who signed up, with the date, status and the stage they reached. A CRM export is best, though a spreadsheet is acceptable. Without it, the baseline has to be rebuilt from emails, and the first report undercounts.
- A sales and onboarding owner for each stage
- A person named for each stage from first call to first payment, with a backup. If a stage has no owner, applications stalled there stay stalled and our report would only describe the stall.
- The partner and reseller list
- The names of banks, agents, accountants and platform partners who bring merchants, with whoever manages each. A rough list is acceptable. Missing partners mean their merchants appear as unknown, and the partner effort cannot be judged.
- Your qualification rule for regulated products
- For lending or buy-now-pay-later, the criteria set by your lending partner for who may be offered the product. We never write these. If the rule changes, tell us before any message or form is updated.
How it works
How the lead generation work runs
The work itself, in order. How an engagement starts, from your brief to a written scope, is set out on our method page.
- 1
Define source and qualified lead on one page
We begin with two definitions written with sales and onboarding: where a lead came from, and what makes it a lead worth a call. You decide whether a lead needs documents, a business type or a volume estimate. The page is signed by your head of sales, and we use it to count everything that follows.
- 2
Trace last quarter's signups back to their origin
We take the merchants who signed up and went live, and trace each to the route that brought them: search, a bank officer, a field visit, a partner, a referral. You supply the records. Some records will have no source, and we mark them as unknown rather than guess, so the baseline you see is the one your records can truly support.
- 3
Lay out onboarding stages and drop points
With your operations team we list the stages from signup to first live payment, such as business details, KYC documents, bank verification, integration and test payment, and record where applications stop. The reasons for stopping come from the people who chase them. This shows where effort is lost.
- 4
Agree the filter for wrong enquiries
We list the kinds of enquiry that are not merchants: students, shoppers with a payment query, job seekers and sellers in a business you cannot serve. You and sales decide what each gets, whether a reply, a redirect to support or no reply. The filter is written down so every person handles them alike.
- 5
Test each route, then launch with the partner register
We send test enquiries through each route and watch where they land, who replies and how the source is recorded. Then we start the routes, with a register for partner and reseller leads that names an owner for each. You choose which routes begin first and which wait.
Where this fits
Three pieces of sales work, in this order.
This work sits inside sales process design, at stage 1, prospecting and lead generation. The audit comes before it, and sales management keeps it running.
Step 1
Sales audit
Find where deals are being lost and what to fix first.
Start here if you cannot say where orders are lost.
Step 2 · you are here
Sales process design
One written way to sell, from first enquiry to repeat order.
Start here if every salesperson sells differently.
Step 3
Sales management
A target, a review routine and someone who owns the number.
Start here if the team has targets and no routine.
FAQ
Questions owners ask before they call.
Not here? More answers, or ask on WhatsApp.
Should we buy lists of merchants?
The same merchant signs up three times. Which counts?
How do we count a merchant who came through a field visit or a bank officer?
What counts as qualified for a lending or buy-now-pay-later product?
What should we do with a lead that comes from a bank officer or a field visit?
A merchant asks for a call back but has not filled the form. Where does that go?
How much does it cost?
How long is the contract?
How soon will we see results?
Who will actually do the work?
From the blog
Further reading for payment and fintech companies.
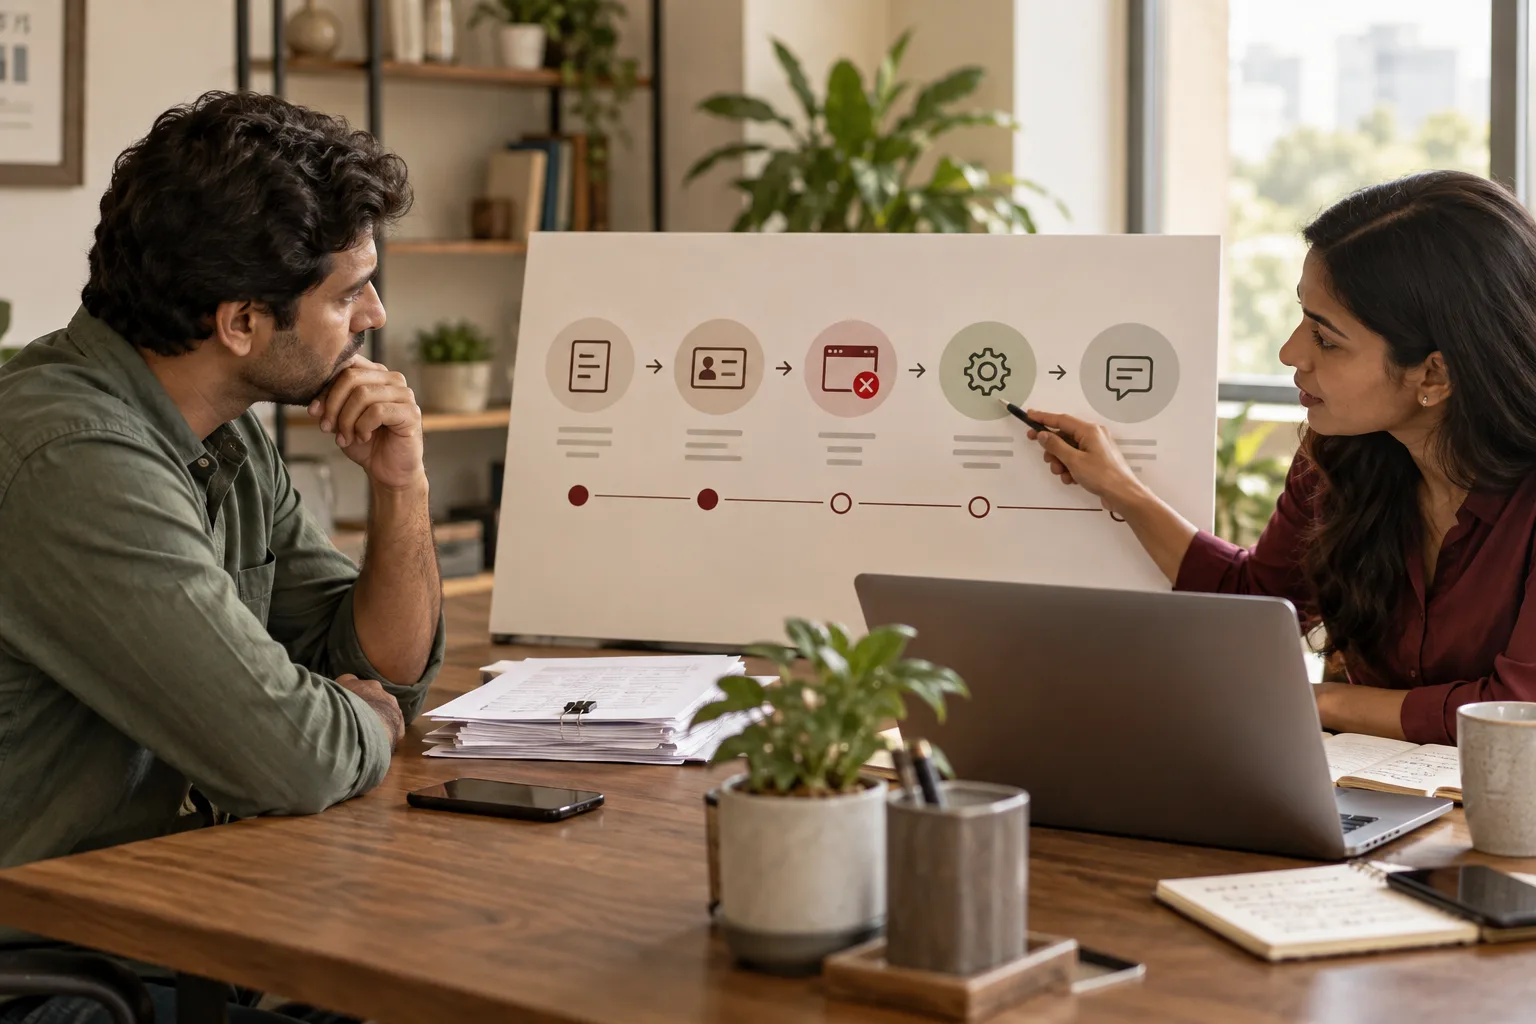 5 min read · 6 Oct 2026Why signed-up merchants never take a live paymentMerchants stall between signup and a first live payment at four points: KYC paperwork, site review, integration and silence. Find yours and clear it.
 6 min read · 6 Oct 2026How buyers decide which lender or adviser to trustPeople choosing a bank, lender, adviser or insurer start with a name someone gave them, then check you before calling. See what they look for.
More for payment and fintech companies
Related work to consider.
Closest to this: leads and follow-up
Also for payment and fintech companies
Or start from the overview: sales and marketing for payment and fintech companies.
Your next practical step
Tell us what you are trying to grow, and we will read it before we call.
Eight short steps, mostly taps. Skip anything you would rather answer on the call.