Chemical manufacturers · Dealer and distributor audits
Find out which stockists hold your drums, whose stock is ageing and who owes you money.
A dealer and distributor audit for a chemical manufacturer is a point-in-time review of the stock your partners hold, the batches they sell, what they owe and how well they cover their areas. GullySales compares your dispatch and receipt records with partner stock evidence, then reports which partners need support and which need a decision.
Scope, fee, reporting and term are agreed in writing after we have read your brief and spoken to you.
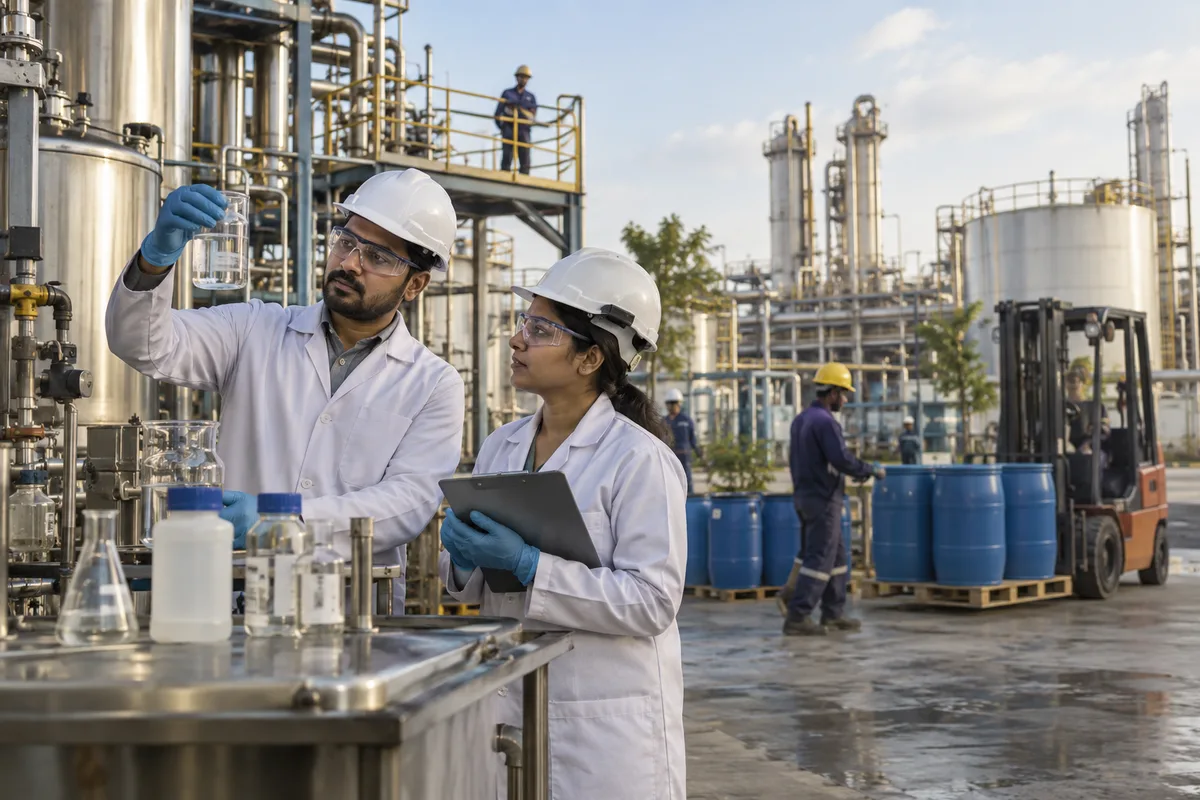
What dealer and distributor audits means
Dealer and distributor audits are point-in-time reviews of how your sales partners hold stock, pay invoices, and cover their territories. GullySales compares your order and payment records with available secondary sales evidence and agreed partner checks, then delivers a ranked report for decisions about existing partners and network expansion.
Also for chemical manufacturers
- Channel partner recruitment for chemical manufacturers
- Channel sales strategy and route to market execution for chemical manufacturers
- Channel territory planning for chemical manufacturers
- Distributor development for chemical manufacturers
- Distributor sales force effectiveness for chemical manufacturers
- Event and trade show marketing for chemical manufacturers
- Export and international market development for chemical manufacturers
- Partner compensation and incentive design for chemical manufacturers
Sales and marketing for chemical manufacturers, the overview.
Last updated 14 Nov 2026.
For chemical manufacturers
Where it usually goes wrong, and what we would do.
“Billed stock is not sold stock”
A dispatch of drums counts towards your sales target the day it leaves the plant, but the stockist may be holding it for months. Where a scheme rewarded the push, the godown can be full of slow grades while a faster grade runs short. Comparing what you billed with what the partner sold onwards shows whether the order book reflects demand or only the stocking habits of your partners.
“Batch age and storage condition matter for chemicals”
Some grades lose strength, absorb moisture or separate if stored badly or kept past their shelf life. A drum that has sat in a hot godown with a damaged seal can reach a buyer under your label and fail in their process. An audit that records batch numbers, manufacturing dates and the state of storage tells you where old stock sits and where a quality complaint is waiting to happen.
“Repacking and decanting put your name on someone else's work”
Distributors sometimes split a drum into smaller cans or carboys to serve small buyers. Done carelessly, this mixes batches, uses unlabelled containers or drops the safety information the buyer needs. A partner who repacks without your knowledge is selling under your name with your brand carrying the risk. The audit checks whether repacking happens, how it is labelled and whether the paperwork travels with the product.
“Credit sits behind fresh orders”
A distributor who keeps ordering looks healthy, while earlier invoices stay unpaid. In a trade where a single tanker is a large invoice, a few late payers can hold a serious part of your working capital. The ledger needs reading against the credit terms you agreed and the receipts you recorded, partner by partner, so that decisions on further supply rest on what is owed and not on what was ordered.
What we do
What we deliver for chemical manufacturers.
The work available for this need. We agree the deliverables and responsibilities for your engagement in writing.
Stock and sales-out comparison
For each partner, a comparison of what you dispatched, the stock they hold by grade and pack, and what they say they sold onwards. Each figure is marked as taken from a record, stated by the partner or counted on a visit. Your sales head sees at once which numbers rest on evidence and which rest on a conversation.
Result: Each partner's stock figures carry a mark showing how they were obtained.
Batch and shelf-life register
A list of batch numbers, manufacturing dates and quantities seen at partner premises, with the oldest stock and any grade near the end of its stated shelf life flagged. Your quality lead reviews the list and decides what is recalled, moved or sold first. The register is only as complete as the checks permitted at each site.
Result: Your quality lead can name the oldest batch at each audited partner.
Storage and handling notes
Notes on how each audited partner stores your products: ventilation, segregation of incompatible grades, container condition and labelling. They are observations for your quality and safety officers, not a statutory inspection. Where a partner's premises look unsuited to a grade, the note records it so you can decide whether that grade should ship direct instead.
Result: Each audited site has a written note your safety officer has reviewed.
Credit and ageing review
Balances grouped by invoice age and set against the credit terms you agreed, with ledger entries and receipts listed so your accounts team can check any exception. Disputed invoices, unadjusted credit notes and unmatched receipts are set apart. The review separates a late payer from a partner whose records simply do not agree with yours.
Result: Your accounts team can trace every flagged balance to an invoice and a receipt.
Coverage and scheme claims check
A check of whether assigned areas are served, using invoices and partner statements, and whether scheme claims have the invoices and conditions they depend on. Claims that do not meet the written terms are listed with the missing evidence. Your owner decides what to pay, hold or query. The check reports what the records show and offers no judgement on intent.
Result: Each scheme claim in the sample is marked as supported or missing named evidence.
Ranked partner report
A written report ranking audited partners by what the evidence shows, with a proposed action for each: support, reduce supply, tighten credit, add a partner nearby or leave unchanged. Gaps in the evidence are stated plainly. The report gives your management a basis for decisions before the next scheme, credit limit or new appointment is agreed.
Result: Your management can see the proposed action for each partner and the evidence behind it.
How the result is measured
- Stock ageing and excess stock against agreed norms
- Secondary sales supported by available records, separate from primary billing
- Outstanding credit and overdue balances against terms
Recorded as a baseline before work starts, so every later report has an honest comparison.
Who it is for
This is written for these chemical manufacturers.
- Specialty chemical manufacturers
- Industrial solvent producers
- Adhesives and sealants manufacturers
- Water treatment chemical manufacturers
- Agrochemical and pesticide formulators
- Paints and coatings raw material suppliers
- Construction chemical manufacturers
- Textile processing and dye chemical manufacturers
- Food-grade and pharmaceutical excipient manufacturers
Before you decide
Agree the work. Know how to judge it.
Dealer and distributor audits for chemical manufacturers: use these checks to prepare, choose the scope, and review what changes.
Bring the right evidence
Map existing partners, their territories, and the customers they serve. Review active selling and repeat orders separately from the number of partners signed up.
Make the scope clear
Agree partner fit, territory rules, onboarding, and support responsibilities. Clarify how direct enquiries and partner enquiries are assigned before starting recruitment.
Check the work in use
Follow a partner enquiry through to an order and the next purchase. Check whether the partner has the product knowledge and material needed to sell without repeated intervention.
Know when to change course
If current partners cannot sell because supply or support is weak, resolve that before recruiting more. A bigger network can spread the same problem further.
These are discussion points, not a fixed package. GullySales confirms the deliverables, responsibilities, fee, and term in writing after reading your brief and speaking with you.
Before we start
What to have ready before the work starts.
The records, access and decisions this work needs from chemical manufacturers. Anything missing is noted in the written scope, with who will supply it.
- Partner ledgers and receipts
- Export the ledger for each partner to be audited, with receipts, credit notes and the credit terms agreed. Ageing cannot be read without them, and an unmatched receipt looks like an unpaid invoice. If your ledger and the partner's disagree, send both, because the difference itself is part of what the audit reports.
- Dispatch records with batch numbers
- Provide dispatch notes showing grade, pack size, quantity and batch number for each partner. Without batch numbers we cannot tell how old the stock at a godown is, only how much was sent. If batches were not recorded, tell us, and we will report batch age as unknown, not guess it from the invoice date.
- Scheme terms and claim files
- Send the written terms of every scheme running with the partners and the claim files paid or pending. A claim can only be tested against its conditions. When terms exist only in a message or a phone call, we list the claim as unsupported by a written term and leave your owner to decide how to treat it.
- A safety and quality contact
- Name the person who decides who may enter a partner's storage and how hazardous grades are handled. The audit involves counting and photographing stock that can be corrosive or flammable. Without this person, we limit the work to records and statements, and the report says that no physical check was possible.
- Your sales head on the first call
- Ask your sales head to introduce the audit to each partner and stay available for the first conversations. A partner who hears about an audit from a stranger may withhold records. With a familiar voice explaining the purpose, partners are likelier to share statements, and the figures in the report are more complete.
How it works
How the dealer and distributor audits work runs
The work itself, in order. How an engagement starts, from your brief to a written scope, is set out on our method page.
- 1
Agree the partners and the checks
With your sales head and finance lead we choose which partners to audit and which checks apply: stock, batch age, storage, credit, coverage and claims. We write the scope down. Partners are told by your own people, in your words, that a review is under way, so nobody meets an unexplained visitor at their godown.
- 2
Pull your own records first
We collect dispatches, invoices, credit notes, receipts, scheme terms and the partner ledgers held in your accounting software. We build the primary sales figure per partner and the balance they owe. These figures are recorded before any visit, so the later reading compares like with like and not memory with memory.
- 3
Request partner statements
Each partner is asked, through your team, for a stock statement by grade and batch and a sales-out summary. We compare the statement against dispatches and note differences. A partner who cannot produce a statement is recorded as such, and the report says whether the record is missing or was declined, without drawing a conclusion about the reason.
- 4
Visit and count where agreed
Where a partner agrees, we or your staff count stock, note batch numbers and dates, and photograph storage and labels. Hazardous grades are handled only by people trained to do so, and your safety officer decides who attends. If a visit is refused, the report marks the figures as unverified and does not fill the gap with an estimate.
- 5
Test credit and claims against documents
We age the balances, set them against agreed terms and check each claim in the sample against invoices and conditions. Your accounts team confirms the matches. Items that do not match are listed with what is missing. We do not decide whether a claim is valid; we show what the documents say and leave the decision to your owner.
- 6
Write the report and read it with you
We deliver the ranked report and go through it with your management, partner by partner. Decisions on credit, supply and appointment stay with you. After any action is taken, we compare the same figures against the baseline recorded at the start, so you can see which gaps closed and which remain.
Where this fits
Three pieces of sales work, in this order.
This work sits inside sales audit. Find where deals are being lost and what to fix first.
Step 1 · you are here
Sales audit
Find where deals are being lost and what to fix first.
Start here if you cannot say where orders are lost.
Step 2
Sales process design
One written way to sell, from first enquiry to repeat order.
Start here if every salesperson sells differently.
Step 3
Sales management
A target, a review routine and someone who owns the number.
Start here if the team has targets and no routine.
FAQ
Questions owners ask before they call.
Not here? More answers, or ask on WhatsApp.
Is an audit a way to catch a dishonest distributor?
Do you count the drums yourselves?
Can you tell us if a distributor is repacking?
Does this replace our statutory or bank stock audit?
What if a distributor will not cooperate?
How will we know the audit was worth doing?
How much does it cost?
How long is the contract?
How soon will we see results?
Who will actually do the work?
From the blog
Further reading for chemical manufacturers.
 6 min read · 6 Oct 2026How industrial buyers decide which unit gets the RFQWhat industrial buyers check before sending an RFQ, across nine manufacturing trades, and where a unit drops off the shortlist.
 6 min read · 13 Jun 2026Trade fair or targeted outreach: where a manufacturer's money goes furtherCompare a trade fair and targeted outreach on cost per qualified conversation, with a worksheet where you enter your own figures.
 5 min read · 3 Nov 2025Sample approved, no order: how to follow up when quality says yes and purchase says nothingYour sample is approved but no purchase order follows. What purchase is waiting for, who to ask, and the next step that turns approval into an order.
More for chemical manufacturers
Related work to consider.
Closest to this: channels and partners
- Channel partner recruitment for chemical manufacturers
- Channel sales strategy and route to market execution for chemical manufacturers
- Channel territory planning for chemical manufacturers
- Distributor development for chemical manufacturers
- Distributor sales force effectiveness for chemical manufacturers
- Event and trade show marketing for chemical manufacturers
- Export and international market development for chemical manufacturers
- Partner compensation and incentive design for chemical manufacturers
Also for chemical manufacturers
Or start from the overview: sales and marketing for chemical manufacturers.
Your next practical step
Tell us what you are trying to grow, and we will read it before we call.
Eight short steps, mostly taps. Skip anything you would rather answer on the call.