MSME and business finance providers · Reputation management
An owner who was declined with no reason writes the review that stays on the page.
Reputation management for an MSME and business finance provider means replying to the owner who was declined, the one who was surprised by a charge and the one who was delighted, and fixing inside the office what the reviews point to. GullySales writes the reply wording with your compliance officer and sets up where reviews are read.
Scope, fee, reporting and term are agreed in writing after we have read your brief and spoken to you.
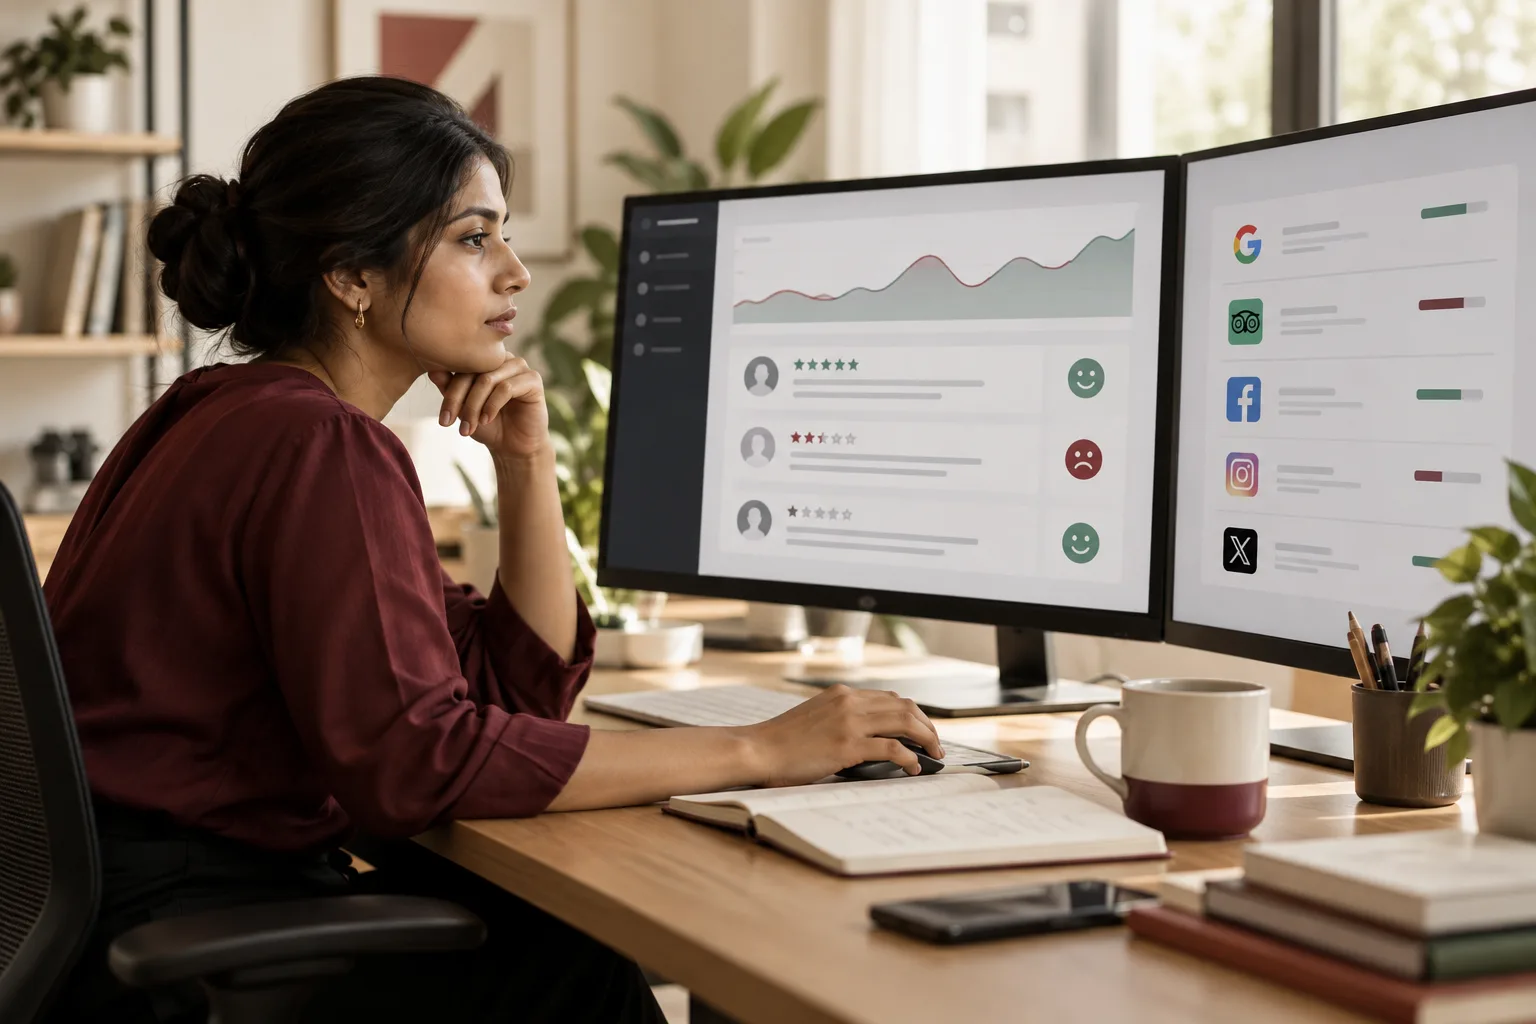
What reputation management means
Reputation management is watching what is said about your business across Google, social media and review sites, and responding to it before it changes a buyer's mind. GullySales monitors mentions, drafts responses to negative reviews and flags recurring complaints back to your team.
Also for MSME and business finance providers
- SEO for MSME and business finance providers
- Local SEO for MSME and business finance providers
- PPC for MSME and business finance providers
- Lead generation for MSME and business finance providers
- WhatsApp marketing for MSME and business finance providers
- Referral marketing for MSME and business finance providers
- Follow-up systems for MSME and business finance providers
- CRM for MSME and business finance providers
Sales and marketing for MSME and business finance providers, the overview.
Last updated 6 Oct 2026. Rules for this trade differ by state and professional body, and they change. We describe restrictions in general terms, so check the current position with your own council or adviser before you publish anything.
For MSME and business finance providers
Where it usually goes wrong, and what we would do.
“Declined owners write more reviews than happy ones”
A rejection with no reason is a reviewer waiting to happen. The owner who got a loan seldom writes, so the page shows the angry minority.
“A partner's conduct is posted under your name”
A DSA who asked for cash as a fee, or sent the owner a different company's paper, leaves a review for you. The owner does not know the difference.
“Charges that appear at sanction read as hidden charges”
Processing fee, insurance or stamp duty first seen in the sanction letter feel like a trick. Even when disclosed, the review calls it hidden.
What we do
What we deliver for MSME and business finance providers.
Every deliverable, what it covers for you, and the result it is there to produce. Nothing here is an extra.
Reply wording that compliance has approved
Short replies for praise, a declined file, a charge complaint and a partner complaint, with no account detail and no argument.
Result: A reply goes out without waiting for a legal read each time.
A review inbox per office
All reviews from Maps and JustDial in one place, with an owner for each office who reads and replies.
Result: No review sits unseen for a season.
A reason given with every decline
A plain-words reason written into every declined file and read to the owner, and a date to look again when it can change.
Result: The owner who was declined knows why and can come back.
A conduct check on partners
A call to a sample of owners each partner has sent, asking what they were told and what they paid, plus a clause in the agreement on fees and name use.
Result: A partner's misconduct is found by you and not by a reviewer.
A way to ask happy borrowers within the rules
A link and a message sent after disbursal or the first repayment, to every borrower alike, with no reward and no selection of the happy ones.
Result: Reviews reflect the borrowers you have and not only the angry ones.
Review themes taken to credit and operations
Reviews grouped by cause, such as delays, charges and communication, and brought to the credit head and the branch manager.
Result: Reviews change a routine, not only a reply.
How the result is measured
- Average rating
- Response time to reviews
- Negative mentions resolved
Recorded as a baseline before work starts, so every later report has an honest comparison.
What to do with each review
How an MSME lender replies to praise, declines, charge complaints and partner complaints.
- Praise after a loan was drawn
- Thank the owner without naming the amount or the product. Pass it to the officer by name, and note what made the file go smoothly so another officer can copy it.
- Declined, and angry about it
- Reply that you would like to explain how the file was read, and give the office number. Do not discuss the decision in public. Inside, check that the reason was given to him in plain words.
- Charges that appeared late
- Say that fees are set out in the sanction letter, and invite a call. Never argue in public. Inside, check whether the charges were mentioned at the first call and written on the product page.
- Review about a DSA or partner
- Reply that you are looking into it and invite a call. Never blame the partner in public. Inside, find who the partner is, check the agreement and speak to the owner.
- Slow file and many calls for the same paper
- Apologise for the wait and give a name to ask for. Inside, find where the file stood and whether two officers asked for the same paper. Fix the handover, not the wording.
- Review that looks fake or from a rival
- Check the name against your enquiries. If nothing matches, report it through the platform's process and reply once, plainly. Do not post replies from fake accounts or ask others to counter it.
Who it is for
This is written for these MSME and business finance providers.
- NBFCs lending to small businesses
- Fintech lenders working with partner NBFCs
- Invoice discounting and factoring platforms
- Machinery and equipment finance companies
- Loan against property lenders for business owners
- Supply chain finance for dealers and vendors
- Business loan consultants and DSAs
- MSME desks of small finance banks and cooperative banks
How it works
From your first message to the first report.
No open-ended retainer. Every step gives you something in writing.
First
Your brief
You tell us what you need in a few short steps: your business, what you want, where enquiries come from and how they are handled.
After the brief
A conversation and a written scope
We read it, then talk with whoever handles your enquiries. If you want our help, the scope, the fee and the reporting come in writing, and nothing starts before you have read them.
Before work starts
Baseline recorded
The numbers this work is meant to move, such as enquiries, quotations, orders, visits or renewals, written down so every later report has an honest comparison.
After the baseline
The first fix goes live
The fix we agreed to start with is put in place and measured against the baseline, whether that is a reply, a follow-up, a page, a listing or the handover between marketing and sales.
As agreed
Report against the baseline
What moved, what did not, and what changes next, in plain words. How often you get it is set in writing before work starts.
At renewal
Renew on the numbers
The term ends and you decide whether to continue from the results. The length is agreed in writing before anything starts.
How the reputation management work runs
- 1
Understand current perception
We start by actually searching your business name and reviewing what a stranger would currently see.
- 2
Audit existing mentions
We catalogue reviews, mentions and search results, flagging anything negative or inaccurate.
- 3
Plan responses
A calm, factual response is prepared for anything that needs one, agreed with you before posting.
- 4
Implement monitoring
Ongoing checks are set up so new mentions are caught promptly rather than discovered by accident.
- 5
Measure and report
Sentiment and response times are reported, with your business name searched again to see what has moved.
Why us
Why owners pick GullySales over an agency.
Marketing and sales, as one job
Most agencies stop at the enquiry. We also fix what happens after it: the reply, the follow-up, the quote and the CRM.
The person on the first call does the work
No account managers in between. You are never handed to someone you have not met.
A baseline before anything starts
Your numbers are written down on day one, so every later report compares against something honest.
The fee in writing, split three ways
Our time, your media spend and production on separate lines. You always see what goes to us.
No guarantees we cannot keep
The term is agreed in writing and never a default twelve months. We never promise a ranking or a lead count, because nobody controls those.
One office, and we say so
Nagarbhavi, Bengaluru. We work across India by call and WhatsApp and travel when a session needs to be in person.
#257, 3rd floor, Sri Nanjundeshwara Complex, Nagarbhavi 8th Block, Outer Ring Road. How we work.
Your brief
Tell us what you need, and we will read it before we call.
Eight short steps about your business, what you want and who decides. Most questions are a tap, and you can skip any you would rather answer on the call.
FAQ
Questions owners ask before they call.
Not here? More answers, or ask on WhatsApp.
Can we ask every borrower for a review?
Should we reply in the owner's language?
A review says our officer asked for cash outside the fee. What do we do?
Can a review name the officer who helped?
How long is the contract?
How soon will we see results?
Who will actually do the work?
What do you need from us?
What if we are not happy with the work?
From the blog
Further reading for MSME and business finance providers.
 6 min read · 6 Oct 2026How buyers decide which lender or adviser to trustPeople choosing a bank, lender, insurance agent, adviser or payment company start from a name someone gave them, then check you before they call. This post sets out what they look for and where firms lose them.
 6 min read · 6 Oct 2026How MSME lenders stop loan files dying at the papers stageA small business owner stops answering when the paper list keeps growing. How a lender can write the checklist down once, keep one person on the file and call back the owner who went quiet.
More for MSME and business finance providers
Everything else we would do for you.
- SEO for MSME and business finance providers
- Local SEO for MSME and business finance providers
- PPC for MSME and business finance providers
- Lead generation for MSME and business finance providers
- WhatsApp marketing for MSME and business finance providers
- Referral marketing for MSME and business finance providers
Or start from the overview: sales and marketing for MSME and business finance providers.
Your next practical step
Tell us what you are trying to grow, and we will read it before we call.
Eight short steps, mostly taps. Skip anything you would rather answer on the call.