Finance and insurance advisers · Follow up systems
Chase the missing document and the lapsing policy with a routine, not a memory.
A follow-up system for a finance or insurance adviser is the set of agreed nudges that bring back a quote that went quiet, a document not yet sent and a policy about to lapse. GullySales writes the messages, the triggers and the owner for each, and sets them up in the tools you already use.
Scope, fee, reporting and term are agreed in writing after we have read your brief and spoken to you.
What follow up systems means
A follow-up system is the set routine for calling, messaging or emailing an enquiry more than once, since most buyers do not decide on the first conversation. GullySales sets the number and timing of follow-ups so an undecided buyer keeps hearing from you until they decide either way.
Also for finance and insurance advisers
- Lead generation for finance and insurance advisers
- CRM for finance and insurance advisers
- SEO for finance and insurance advisers
- PPC ads for finance and insurance advisers
- Digital marketing for finance and insurance advisers
- Reputation management for finance and insurance advisers
- Local SEO for finance and insurance advisers
- Branding and identity for finance and insurance advisers
Sales and marketing for finance and insurance advisers, the overview.
Last updated 14 Nov 2026. Rules for this trade differ by state and professional body, and they change. We describe restrictions in general terms, so check the current position with your own council or adviser before you publish anything.
For finance and insurance advisers
Where it usually goes wrong, and what we would do.
“The silence after the quote is where the file dies”
The adviser sends a premium or an EMI figure and waits. The customer is comparing, asking a relative and getting busy. Without a planned second message that adds something useful, the quote sits unanswered and the customer signs with whoever called again.
“A missing document is a polite problem, not a refusal”
A borrower who agreed on the call but has not sent the income papers is rarely saying no. They cannot find a statement, or feel awkward about the figures. A short message listing exactly what is still needed and offering help gets further than a general reminder.
“A lapsed policy is the cheapest customer to win back”
A motor or health policy that lapsed because nobody reminded the holder is a customer who already trusts you with a product. The call should come before the date, and again straight after if the date passes.
“A follow-up that repeats the pitch gets muted”
Sending the same rate and the same line three times teaches the customer to ignore the number. Each nudge should carry one new thing: a question answered, a document list, or a change in the quote.
What we do
What we deliver for finance and insurance advisers.
The work available for this need. We agree the deliverables and responsibilities for your engagement in writing.
Quote follow-up sequence
A set of short messages for the days after a quote, each adding one new piece of help, with a clear point at which to stop.
Result: Every quote has a planned next message and a planned end.
Document chase messages
A checklist-style message per product that names the papers still missing and says how to send them.
Result: The customer knows exactly what is outstanding without calling.
Renewal reminder routine
Reminders ahead of the due date and a second call after it, driven by the renewal field in your record.
Result: No policy falls due without someone being assigned to call.
Owner and trigger for each nudge
A one-page table naming who sends each message and what event starts it, so nothing depends on who remembers.
Result: A new team member can run the routine from the page.
Stop rules and consent
Written rules on when to stop messaging and how a customer opts out, with the platform's current rules checked.
Result: A customer who says stop stops receiving messages.
Review of stalled files
A regular look at files that did not move, to find which message and which stage lost them.
Result: Your messages are corrected by what actually happened to files.
How the result is measured
- Follow-up completion rate
- Average number of follow-ups before close
- Enquiries closed after repeat follow-up
Recorded as a baseline before work starts, so every later report has an honest comparison.
What to capture or send
These are the moments in a loan or policy file that need a named owner and a message.
- Quote sent, no reply
- A message that adds something, such as a change in the premium or a document that would improve the offer, and a note of the date the customer said they would decide.
- Document still missing
- A courteous message naming the one paper needed and the reason, with a photo route. Record which paper it was, since the same one stalls several files.
- Loan sanctioned or policy issued
- A message confirming what happens next and who to ask, followed by a note on the date the first EMI or premium is due.
- Policy a few days from lapse
- A reminder with the policy number and the payment route. The due date comes from the record, and the message goes only to customers who agreed to reminders.
- Claim settled or closed
- A short check-in from the adviser, which is the right moment to ask whether the family would like a policy review.
Who it is for
This is written for these finance and insurance advisers.
- Loan DSAs and connectors
- Health and life insurance advisers
- General insurance agents
- NBFC and co-operative bank branches
- Mutual fund and investment distributors
- Chit fund companies
- Insurance broking firms
- Business loan and loan against property specialists
Before you decide
When this may not be the right fit.
- You cannot yet see which files are stalled, so a follow-up routine would have nothing to read from.
- You have not asked customers whether they agree to reminders, and unwanted messages cost more trust than a lost file.
- You would use the same message for a missing document and a lapsing policy, when the customer's reason for acting differs.
Before you decide
Agree the work. Know how to judge it.
Follow-up systems for finance and insurance advisers: use these checks to prepare, choose the scope, and review what changes.
Bring the right evidence
Trace recent enquiries from arrival to the last recorded action. Include a won enquiry, an unsuitable one, and one that went quiet, with personal details removed for the initial discussion.
Make the scope clear
Agree who accepts each enquiry, what makes it qualified, and how ownership changes. Include a rule for missed replies and a clear reason for closing an enquiry.
Check the work in use
Pick an enquiry at random and ask the team to find its owner, latest conversation, and next action. Check that the record agrees with what actually happened.
Know when to change course
If no one has capacity to respond, assign that responsibility before buying more leads. Automation can support the owner, but it cannot replace an unresolved handover.
These are discussion points, not a fixed package. GullySales confirms the deliverables, responsibilities, fee, and term in writing after reading your brief and speaking with you.
Before we start
What to have ready before the work starts.
The records, access and decisions this work needs from finance and insurance advisers. Anything missing is noted in the written scope, with who will supply it.
- A list of quotes sent and their dates
- The sequence needs a start date for each file. A sheet is enough. Without dates, the nudges would be guesses, and a customer who already decided might receive a reminder weeks late. Include which stage each file reached and what the customer last said, so the nudge refers to something real.
- The tool where your reminders will live
- Tell us whether tasks sit in a CRM, a sheet or WhatsApp. We build within it. Without a choice, we suggest the simplest option you already use, so the habit starts without a new login for the team. Say also who has access to it.
- Your principal's rules on contacting customers
- Some principals limit when and how reminders go, and some insist on their own channel for premium reminders. Bring the note. Without it, we use only plain reminders about documents and leave premium nudges to the principal.
- A named owner for each nudge
- A message without an owner is not sent. Name one person per stage, with a stand-in for leave. Without names, tasks sit unassigned in the list and the whole sequence quietly stops after the first week of use.
How it works
How the follow up systems work runs
The work itself, in order. How an engagement starts, from your brief to a written scope, is set out on our method page.
- 1
Read the stalled quotes and pending files
We open the list of quotes that went quiet and loans waiting on papers, with the date of the last contact. You tell us what each customer said. The pattern shows where a nudge is missing and what the customer was waiting for before moving on.
- 2
Decide what closes a file
With you we fix the points at which a file is closed as lost, paused or won, and the reply that ends the sequence. A customer who says stop is removed at once. These rules are written before a single message exists, so no one is chased against their wish.
- 3
Write the nudges in your own voice
We draft the quote follow-up, the document chase and the renewal reminder so each reads as if a person wrote it and offers something new. You edit the wording. Messages that only repeat the pitch are removed, because a customer who has heard it once will mute a second copy. The document chase names the exact paper that is missing, the lender it is for and the easiest way to send it, so the customer replies once instead of asking what is needed.
- 4
Test each nudge on a real file
We run a message on a live file with a customer you know, check the trigger fires and the owner is told. Staff try the tasks themselves. Faults are fixed and the sequence is handed to the team with a note on who does what.
- 5
Review the stalled files against the earlier list
We compare files revived and policies renewed with the stalled list recorded before the work started. You decide which nudges to keep, reword or drop, and which files should now be closed as lost.
Where this fits
Three pieces of sales work, in this order.
This work sits inside sales process design, at stage 2, qualification. The audit comes before it, and sales management keeps it running.
Step 1
Sales audit
Find where deals are being lost and what to fix first.
Start here if you cannot say where orders are lost.
Step 2 · you are here
Sales process design
One written way to sell, from first enquiry to repeat order.
Start here if every salesperson sells differently.
Step 3
Sales management
A target, a review routine and someone who owns the number.
Start here if the team has targets and no routine.
FAQ
Questions owners ask before they call.
Not here? More answers, or ask on WhatsApp.
How many follow-ups are too many?
Can follow-ups be automated?
Are there rules on messaging customers?
Are there rules on reminding customers to pay a premium?
Is it all right to send a premium reminder on WhatsApp?
How do we avoid sounding like a machine?
How much does it cost?
How long is the contract?
How soon will we see results?
Who will actually do the work?
From the blog
Further reading for finance and insurance advisers.
 7 min read · 12 Aug 2026Loan lead generation: how DSAs and loan advisers get home loan leads that closeLoan lead generation works when you reach people at the moment they need a loan, check eligibility early and follow the rules.
 6 min read · 9 Jun 2026How to get more insurance clients as an agent or advisorNew insurance clients come from policyholders and referrals first. Answer enquiries the same day and keep ads within IRDAI and insurer rules.
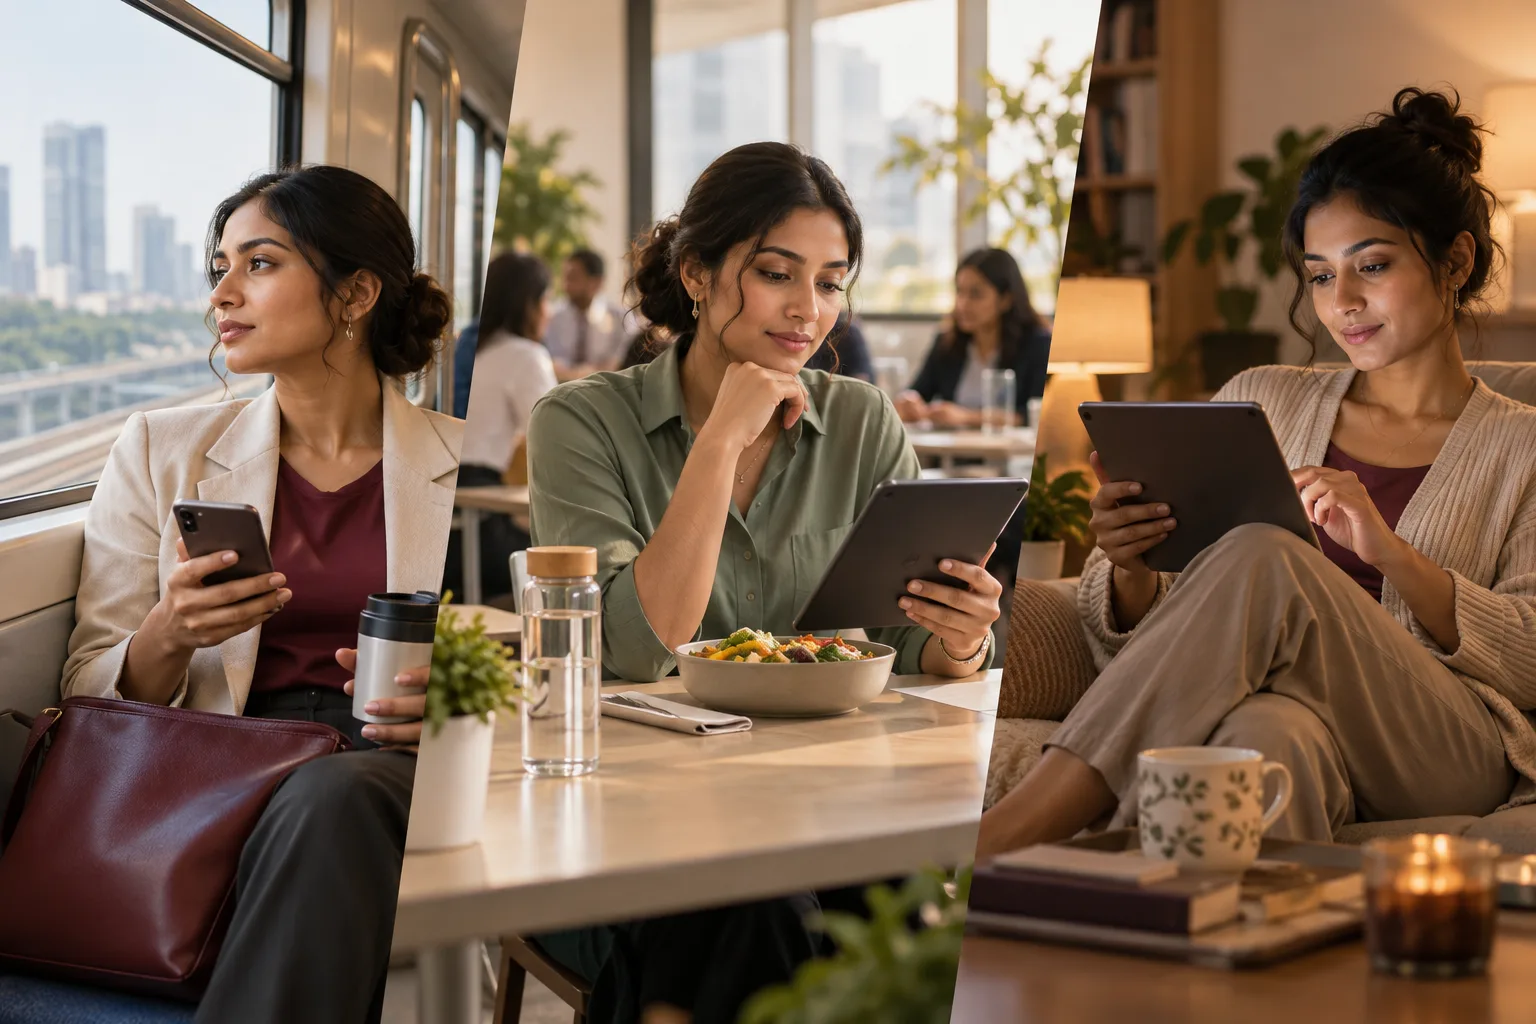 7 min read · 21 Sept 2026How to advertise to working womenThe constraint is time, not interest. Buy the commute, the lunch hour and the window after nine at night, and let people respond without a call.
More for finance and insurance advisers
Related work to consider.
Closest to this: leads and follow-up
Also for finance and insurance advisers
Or start from the overview: sales and marketing for finance and insurance advisers.
Your next practical step
Tell us what you are trying to grow, and we will read it before we call.
Eight short steps, mostly taps. Skip anything you would rather answer on the call.