Banks · Proposal management
Send the corporate proposal before the client's finance team moves to the next bank.
Proposal management for a bank means preparing and sending a clear, complete proposal for a corporate banking relationship, a cash management facility or a trade finance arrangement. It moves quickly, with all the detail a corporate finance team needs to evaluate it. GullySales helps build a proposal template and process that speeds this up.
Scope, fee, reporting and term are agreed in writing after we have read your brief and spoken to you.
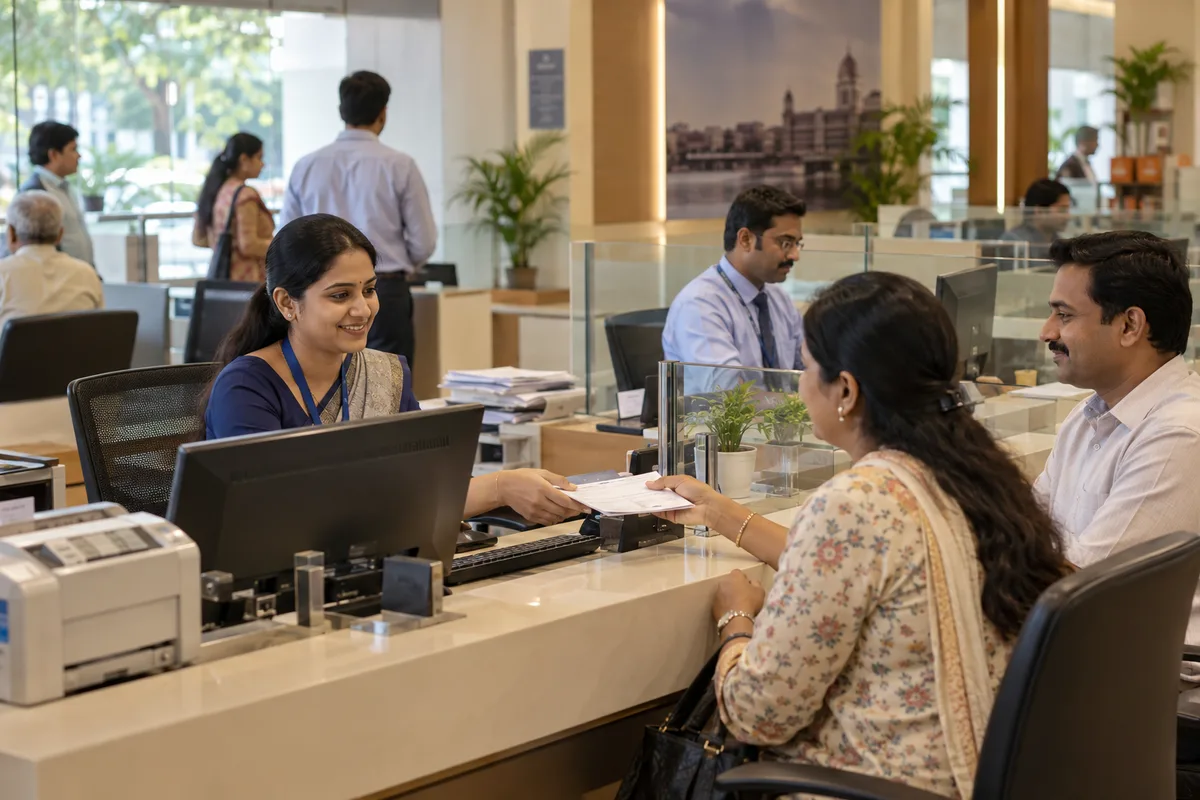
What proposal management means
Proposal management is preparing the formal document a business sends after a discussion, stating scope, price and terms for the customer to approve. GullySales builds a proposal template once, and when the work is GullySales' own, the fee is put in writing and split three ways between time, media spend and production cost.
Last updated 5 Oct 2026. Rules for this trade differ by state and professional body, and they change. We describe restrictions in general terms, so check the current position with your own council or adviser before you publish anything.
For banks
Where it usually goes wrong, and what we would do.
“A complete first proposal avoids a slow back-and-forth”
A corporate finance team comparing banks moves faster past a proposal that answers their likely questions upfront, such as fee structure and service levels. Several rounds of clarification slow the whole process down.
“How quickly a proposal arrives is itself a signal”
A bank that sends a thorough proposal promptly shows the same responsiveness a corporate client will expect during the banking relationship, which a slow proposal quietly undermines.
“A template speeds up preparation without sacrificing customisation”
A well-built base template that a relationship manager can adapt to a specific client's needs saves significant time compared to preparing every proposal entirely from scratch.
What we do
What we deliver for banks.
Every deliverable, what it covers for you, and the result it is there to produce. Nothing here is an extra.
Base proposal template for corporate banking
A well-built template covering fee structure and service levels, adaptable to a specific corporate client's needs.
Result: A relationship manager starts from a strong base, not a blank page.
Anticipated client question checklist
A checklist of likely finance team questions built into every proposal, to avoid a slow round of clarifications.
Result: A corporate client moves faster because the first proposal already answers them.
A proposal routine the branch can repeat
A defined internal routine for preparing and sending a proposal once a request comes in: who drafts it, who checks the figures and who signs it off.
Result: A corporate client sees an organised bank before the relationship starts.
Proposal tracking by stage
A record of which proposals are out, awaiting response, or converted, reviewed alongside other enquiry tracking.
Result: No corporate proposal sits forgotten without a follow-up.
How the result is measured
- Proposal turnaround time
- Proposal to close rate
- Proposals pending a decision
Recorded as a baseline before work starts, so every later report has an honest comparison.
Sections every proposal needs
A corporate proposal answers the finance team's questions in this order.
Rates and fees for corporate facilities are usually set centrally. Fill in what the branch can actually decide, and mark the rest as subject to approval.
- Cover note and one named contact
- Open with who the proposal is for, what they asked, and the name of the relationship manager and the operations contact. A finance head should know who to call about any line.
- Facility summary
- State the product plainly: cash credit, overdraft, letter of credit, bank guarantee or a collection account. Give the limit asked for and the limit the branch can take forward for approval.
- Fees and charges schedule
- List each charge head as per the bank's current schedule. Rates and fees are usually set or approved centrally, so mark anything indicative as subject to approval and check it with the pricing desk first.
- Service arrangements
- Say who handles daily cash pickup, statements, MIS files and queries, and where the client escalates a problem. Corporate buyers compare service as closely as they compare price.
- Documents the client has to provide
- Give a list in one place: KYC of the company and directors, board resolution, financial statements, GST returns and bank statements. A complete list stops the second round of requests.
- Validity and next steps
- Write the date until which the proposal stands, the credit steps still pending and who at the bank does each one. The client's own decision date should sit beside it.
Who it is for
This is written for these banks.
- Private sector bank branches
- Public sector bank branches
- Regional rural banks
- Cooperative banks
- Small finance banks
- Business correspondent networks
- NRI-focused branches
- MSME-focused branches
How it works
From your first message to the first report.
No open-ended retainer. Every step gives you something in writing.
First
Your brief
You tell us what you need in a few short steps: your business, what you want, where enquiries come from and how they are handled.
After the brief
A conversation and a written scope
We read it, then talk with whoever handles your enquiries. If you want our help, the scope, the fee and the reporting come in writing, and nothing starts before you have read them.
Before work starts
Baseline recorded
The numbers this work is meant to move, such as enquiries, quotations, orders, visits or renewals, written down so every later report has an honest comparison.
After the baseline
The first fix goes live
The fix we agreed to start with is put in place and measured against the baseline, whether that is a reply, a follow-up, a page, a listing or the handover between marketing and sales.
As agreed
Report against the baseline
What moved, what did not, and what changes next, in plain words. How often you get it is set in writing before work starts.
At renewal
Renew on the numbers
The term ends and you decide whether to continue from the results. The length is agreed in writing before anything starts.
How the proposal management work runs
- 1
Collect existing proposals
We look at what has gone out before and where it slowed down or went wrong.
- 2
Build the template and calculator
One structure that covers most jobs, with room for the exceptions.
- 3
Set the terms
Payment, validity and exclusions agreed once, in writing, so they do not need to be reargued each time.
- 4
Train the team
Reps learn to fill the template quickly and know when to ask for help on an unusual job.
- 5
Run and refine
We track how long proposals take to go out and adjust the template where it is still slowing people down.
Why us
Why owners pick GullySales over an agency.
Marketing and sales, as one job
Most agencies stop at the enquiry. We also fix what happens after it: the reply, the follow-up, the quote and the CRM.
The person on the first call does the work
No account managers in between. You are never handed to someone you have not met.
A baseline before anything starts
Your numbers are written down on day one, so every later report compares against something honest.
The fee in writing, split three ways
Our time, your media spend and production on separate lines. You always see what goes to us.
No guarantees we cannot keep
The term is agreed in writing and never a default twelve months. We never promise a ranking or a lead count, because nobody controls those.
One office, and we say so
Nagarbhavi, Bengaluru. We work across India by call and WhatsApp and travel when a session needs to be in person.
#257, 3rd floor, Sri Nanjundeshwara Complex, Nagarbhavi 8th Block, Outer Ring Road. How we work.
Your brief
Tell us what you need, and we will read it before we call.
Eight short steps about your business, what you want and who decides. Most questions are a tap, and you can skip any you would rather answer on the call.
FAQ
Questions owners ask before they call.
Not here? More answers, or ask on WhatsApp.
Who should own proposal preparation?
How fast should a proposal go out?
Can the relationship manager put a rate or fee in the proposal?
Should cash management and trade finance go in one proposal or two?
How long is the contract?
How soon will we see results?
Who will actually do the work?
What do you need from us?
What if we are not happy with the work?
From the blog
Further reading for banks.
 6 min read · 6 Oct 2026How buyers decide which lender or adviser to trustPeople choosing a bank, lender, insurance agent, adviser or payment company start from a name someone gave them, then check you before they call. This post sets out what they look for and where firms lose them.
 7 min read · 21 Sept 2026How to advertise to airport travellersA terminal is a small number of regular flyers counted many times, and the crowd changes completely between the six o'clock bank and the summer holidays.
More for banks
Everything else we would do for you.
Closest to this: sales craft
Also for banks
Or start from the overview: sales and marketing for banks.
Your next practical step
Tell us what you are trying to grow, and we will read it before we call.
Eight short steps, mostly taps. Skip anything you would rather answer on the call.