Microfinance companies · Website
Build a website that a borrower's family, a regulator and a recruit can all trust.
A website for a microfinance company is the page where a family checks the lender is real, where a recruit reads about the job and where a complaint can start. GullySales designs it for low-end phones, local languages and the disclosures your policy requires.
Scope, fee, reporting and term are agreed in writing after we have read your brief and spoken to you.
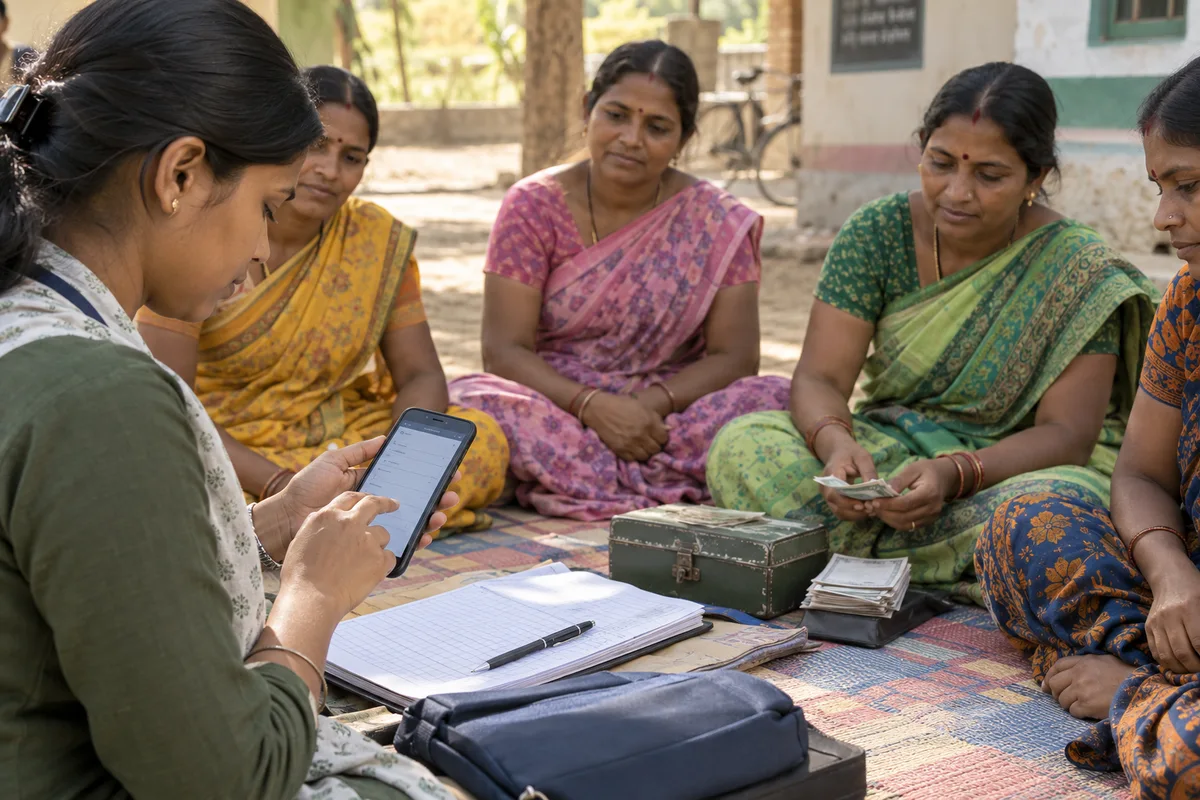
What website means
A website is the page a customer lands on after searching, clicking an advert or scanning a code, and it decides whether they call or leave. GullySales builds and maintains sites that load quickly, explain the offer plainly and make the enquiry form or phone number easy to find.
Also for microfinance companies
- SEO for microfinance companies
- Local SEO for microfinance companies
- Lead generation for microfinance companies
- Social media marketing for microfinance companies
- Content marketing for microfinance companies
- Buyer personas for microfinance companies
- CRM for microfinance companies
- Follow-up systems for microfinance companies
Sales and marketing for microfinance companies, the overview.
Last updated 14 Nov 2026. Rules for this trade differ by state and professional body, and they change. We describe restrictions in general terms, so check the current position with your own council or adviser before you publish anything.
For microfinance companies
Where it usually goes wrong, and what we would do.
“It is the first place to verify the company”
A family hearing the name at a meeting looks for the registered name, the head office, the branches and the grievance route. Missing details look like a lender with something to hide.
“The visitor may read slowly and in another language”
A site written in dense English fails the borrower's daughter and the group leader. Simple sentences and a language switch matter more than animation.
“Disclosures belong where they are seen”
Regulatory information, fair-practice statements and the complaint route must be easy to find. Burying them in a footer is a poor habit that your compliance head will want corrected.
What we do
What we deliver for microfinance companies.
The work available for this need. We agree the deliverables and responsibilities for your engagement in writing.
Page plan and structure
A short plan covering who we are, products, branches, careers, grievance and contact.
Result: Every visitor type finds their page.
Mobile and low-bandwidth build
A light site that loads on a basic phone and a weak connection.
Result: The page opens where borrowers actually use it.
Local-language pages
Core pages in the districts' languages, with the words checked by your field staff.
Result: Households read the company's terms in their own language.
Disclosure and grievance placement
The statements and complaint route your policy requires, placed prominently as your compliance head directs.
Result: A visitor finds how to complain without searching.
Careers section
A section with district vacancies and the real description of field work.
Result: Applicants understand the job and know how to apply.
How the result is measured
- Page load time
- Bounce rate
- Enquiries from the website
Recorded as a baseline before work starts, so every later report has an honest comparison.
Searches your buyers type
Questions a visitor expects the site to answer on a phone.
- [company name] registered microfinance
- A company page with the registration details your compliance head confirms, placed near the top and not buried in a footer.
- [company name] loan interest rate
- A page with the rates and charges your policy publishes, in the form compliance approves, and no comparison with any other lender.
- [company name] branch contact
- A branch directory by district with address, officer language and a phone line, readable on a low-end phone over weak signal.
- [company name] grievance redressal
- A page stating the steps a borrower can follow and the escalation contact, linked from every page.
- [company name] careers field officer
- A careers section listing vacancies by district, the role, the language needed and the way to apply.
Who it is for
This is written for these microfinance companies.
- NBFC-MFIs working through joint liability groups
- Self-help group linkage lenders
- Microfinance companies in rural Karnataka and neighbouring states
- Urban microfinance for small shopkeepers and home-based workers
- Small finance bank microfinance arms
- Microfinance companies adding individual business loans
- Women's livelihood and dairy-linked lenders
- Company branches opening in a new taluk
Before you decide
When this may not be the right fit.
- No one has been named to update branch addresses and vacancies, so the site would be wrong within a short time and trust would fall.
- You want the website to approve loans online, when your process starts with a visit and an application on paper or in the field.
- Your compliance head has not decided what the site may say about rates, so the page would be left empty or filled with a guess.
Before you decide
Agree the work. Know how to judge it.
Website for microfinance companies: use these checks to prepare, choose the scope, and review what changes.
Bring the right evidence
List the pages that support a buying decision and the actions visitors must complete. Keep examples of failed forms, unclear product information, and questions your team answers repeatedly.
Make the scope clear
Agree the page list, content ownership, integrations, and who controls the domain and hosting. Include redirects and existing search traffic in a redesign brief, before changing addresses.
Check the work in use
Complete a real enquiry journey on a phone and a laptop. Check that the confirmation appears, the enquiry reaches the right person, and tracking records the action once.
Know when to change course
If visitors can enquire but the team does not follow up, start with the sales handover. A larger website will not resolve that delay.
These are discussion points, not a fixed package. GullySales confirms the deliverables, responsibilities, fee, and term in writing after reading your brief and speaking with you.
Before we start
What to have ready before the work starts.
The records, access and decisions this work needs from microfinance companies. Anything missing is noted in the written scope, with who will supply it.
- The licence and registration details to publish
- Your compliance head provides the details that must show on the site, in the exact form. We copy them without change. If a detail is in doubt, we leave the line out and flag it, because a wrong registration number is worse than a missing one.
- Photographs of branches and officers at work
- We need photographs of real branches and officers, taken with consent and without borrowers in them. Phone photographs in daylight are acceptable, if the signboard and the entrance are in the frame. Without them, we use plain graphics, and the site feels less personal.
- Access to the domain and current hosting
- The login for the domain name and the host belongs to the company. Ask whoever bought them. If nobody can say, we record that and help you recover control before launch, since a launch without it risks the old address going dark.
- The job descriptions for field officers
- Give us the roles, the places, the requirements and the application route as HR states them. The careers section is written from these. Where roles change, tell us who updates the page, since an out-of-date vacancy hurts trust.
- A reviewer who reads the local language
- Somebody who reads each district language must check the text on the test site. A field officer or a clerk can do it. If no reader is available, we publish the pages in the languages we have verified and hold the rest. A machine translation is never published for a loan product, because one wrong word about a charge or a guarantor can mislead a family.
How it works
How the website work runs
The work itself, in order. How an engagement starts, from your brief to a written scope, is set out on our method page.
- 1
Gather the documents the site must show
We begin by collecting the licence details, the grievance route, the fair practice wording, the product notes and the officer job descriptions that your compliance head says may be shown. You tell us which are current. The site is built around these, and where a document is missing we name it on a list for you instead of writing around it.
- 2
Sketch the pages for four visitors
We draw the pages for the borrower's family, the group leader, the recruit and the regulator, each with a single clear route from the home page. Nothing is designed until you have approved the sketch. The page for the borrower is short and in the local language, and the page for the regulator is plain and complete.
- 3
Test the design on a basic phone
We build the first pages and open them on the cheapest phone a field officer would carry, on a weak connection. Text size, button size and loading are judged there. We cut anything that does not load. You see the same pages on your own phone, and we change what you find hard to read.
- 4
Write and translate the page text
We write each page in plain English and in the district languages with field officers reading each one aloud. Your compliance head clears the text, and the grievance and disclosure wording is placed exactly as the policy states. You approve the careers text with the HR lead. The test site holds all the text before any of it goes live.
- 5
Check every disclosure and the complaint path
On the test site we click through as a borrower would, find the grievance page from every other page, and confirm the contact reaches a real person. Your compliance head signs off the disclosure placement. We note anything the policy requires that the site does not yet show, and fix it before launch.
- 6
Launch and compare with the old site
On the day you approve, we point the address to the new site and check each page, form and redirect on live phones. Over the following visits we compare the visits to the grievance, careers and branch pages with the figures noted before launch. You receive the logins and the page-by-page list of who approved what. We report what the figures show and promise no applications.
Where this fits
Three pieces of sales work, in this order.
This work sits inside sales process design, at stage 1, prospecting and lead generation. The audit comes before it, and sales management keeps it running.
Step 1
Sales audit
Find where deals are being lost and what to fix first.
Start here if you cannot say where orders are lost.
Step 2 · you are here
Sales process design
One written way to sell, from first enquiry to repeat order.
Start here if every salesperson sells differently.
Step 3
Sales management
A target, a review routine and someone who owns the number.
Start here if the team has targets and no routine.
FAQ
Questions owners ask before they call.
Not here? More answers, or ask on WhatsApp.
What must the website state?
Can borrowers apply for a loan on the site?
Who updates the site?
Does the website need to work offline?
Can the site show where a borrower stands on a loan?
How do we keep the site correct when rules and branches change?
How much does it cost?
How long is the contract?
How soon will we see results?
Who will actually do the work?
More for microfinance companies
Related work to consider.
Closest to this: search and visibility
Also for microfinance companies
Or start from the overview: sales and marketing for microfinance companies.
Your next practical step
Tell us what you are trying to grow, and we will read it before we call.
Eight short steps, mostly taps. Skip anything you would rather answer on the call.