Home loan consultants · Real estate and construction
Be the person a buyer calls when the bank says no, and the one they call first next time.
A self-employed contractor in Bengaluru has found a flat in Kengeri and been refused by the bank that holds the account. The ITR shows modest income, and the lender wants a stable, salary-like pattern.
Scope, fee, reporting and term are agreed in writing after we have read your brief and spoken to you.
In one paragraph
A home loan consultant helps a property buyer choose a lender, assemble the papers and follow the application to sanction. Marketing places you with the builders, brokers and salaried buyers who need loans, and with self-employed borrowers whose income is hard to show. Sales is the document chase and the follow-up. GullySales builds that route and the records behind it, within the rules of the lenders you represent.
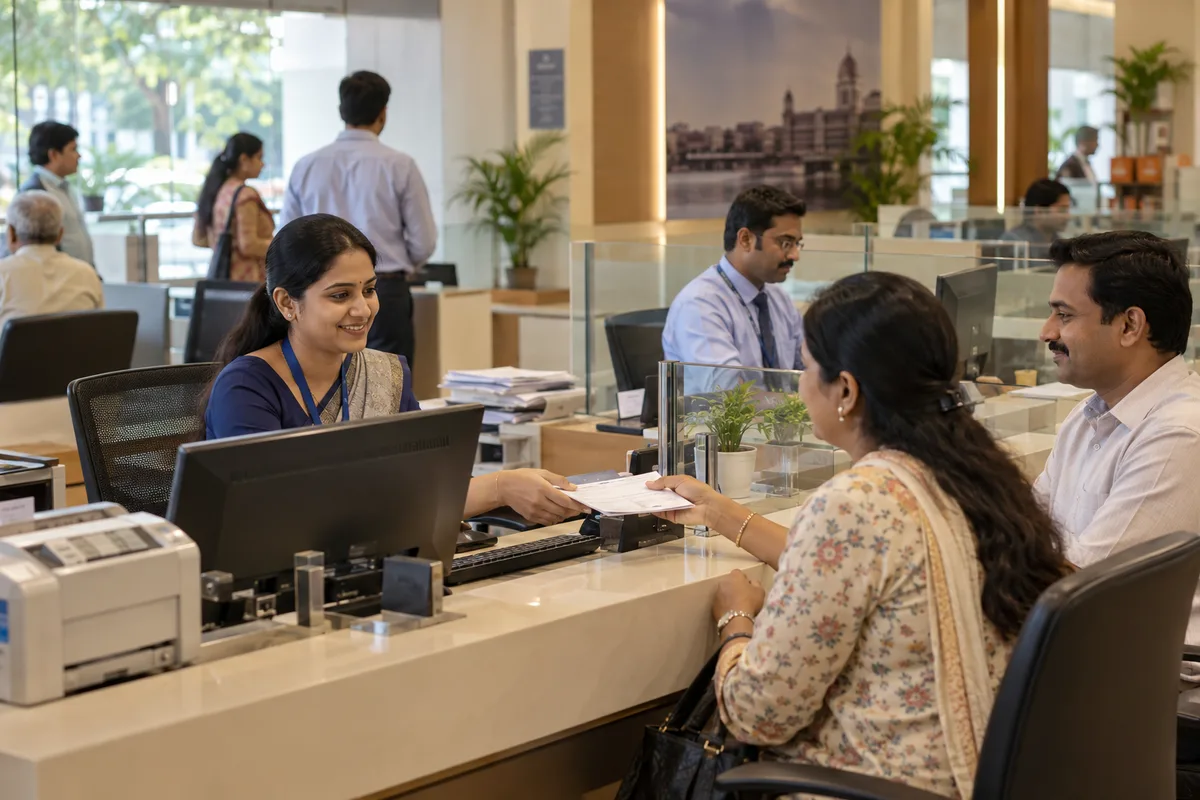
A cousin passes on a consultant's number. The consultant takes the documents, reads them through and names the lender that looks at such a profile differently.
That conversation is the product. Everything before it is a question of whether the borrower finds the consultant, and everything after it is whether the consultant keeps the file alive until the bank decides. The second is work you already do well; the first runs on whoever happens to call.
Last updated 18 Oct 2026.
How buyers decide
How home loan consultants are chosen.
A salaried buyer does not go looking for a consultant. The buyer is sent one: by the builder's sales executive, by a broker who needs the loan to close the booking, or by a friend who was refused elsewhere. The builder or broker tie-up decides which consultant gets the file, so the relationship is where the work lies.
Borrowers with an unusual profile, such as a business owner, a freelancer, an NRI or someone with a low credit score, search online. They type the problem: home loan for self-employed with low income, balance transfer, top-up, loan against property, plot loan, construction loan. They are anxious, they want someone to explain how a lender will read their papers, and they call two or three people before deciding.
Whether a loan is sanctioned, at what rate and for what amount is the lender's decision, based on its own policy and the borrower's papers. A consultant who promises approval, a rate or a sanction date is the one a careful borrower avoids. The consultants who are trusted say what they can do, which is match the profile to the right lender and tidy the file, and say nothing about the rest.
The problem
What usually goes wrong for home loan consultants.
What owners tell us on the first call, in their words.
“Builders send us files but only when the buyer is already in trouble”
The sales executive calls us after the first lender has refused. We could have prepared the file before the booking.
“Borrowers disappear after sending half the documents”
A buyer sends the Aadhaar and PAN, then nothing for ten days. The file sits and the booking date comes nearer.
“We cannot be found by self-employed borrowers”
Our site says "all loans, all banks". The contractor searching for home loan with low ITR never sees a page that speaks to that situation.
“We do not know which lender suits which profile, and nor does the new person we hired”
The knowledge sits in one senior's head. When that senior is on leave, files go to the wrong bank.
“Our name is mixed up with agents who promise approvals”
Borrowers have been burnt by someone who took a fee and delivered nothing. They ask for proof before they trust us.
“Repeat business goes nowhere”
A borrower we helped three years ago is now thinking of a balance transfer, and we never contacted them.
What we do
What we do for home loan consultants.
Everything included for home loan consultants.
A page for each borrower profile
Pages for salaried buyers, self-employed owners, NRIs, balance transfer and plot loans, each describing the papers a lender reads and the points where files stall.
A builder and broker tie-up pack
A short document for builders' sales heads and brokers on what you handle, how you keep them informed on a buyer's file and how the buyer is protected from pressure.
A document collection routine
A WhatsApp list of the papers the borrower must send, with reminders to those who have sent only some.
A lender and profile guide for your team
A shared sheet that shows which of your lenders look at which type of borrower and the points to check before submitting.
A plain statement on fees and commission
A page that says whether the borrower pays you, whether the lender does, and that sanction, rate and amount belong to the lender.
A past borrower record
A record of every borrower you helped, with the loan type, the lender and the year, so a balance transfer, top-up or second-property conversation has a starting point.
How the result is measured
- Enquiries by source: builder, broker, search, referral
- Complete document sets against files started
- Submissions against sanctions by the lender
- Share of files from self-employed, salaried and NRI borrowers
- Reply time to a new borrower
- Past borrowers contacted and responding
Recorded as a baseline before work starts, so every later report has an honest comparison.
Every service, written for home loan consultants
Each has its own page: what it involves for home loan consultants, what you get, and what it is measured on.
- Lead generationFind borrowers while the file is still open, before another consultant has it.
- SEOWrite the page that answers the borrower a bank has just turned away.
- Local SEOShow up when a borrower near the project searches for someone to sit across from.
- Social media marketingPost what a first-time buyer needs to know and keep the sales pitch out of it.
- Content marketingTurn the questions you answer every day into guides a borrower can read before calling.
- Buyer personaDescribe the borrower by the file they bring, not by the loan they want.
- CRMGive every file a stage and an owner, so none sits waiting for someone to remember.
- Follow-up systemsChase the missing salary slip politely until the file is complete or closed.
- WhatsApp marketingMake the WhatsApp chat the place where the paper list lives and the file moves.
- Digital marketingJoin search, partners and WhatsApp so each borrower arrives by a route you count.
- WebsiteBuild a website that tells a wary borrower who you are, what you do and who pays you.
Worth a page and a campaign of their own
Home loans for salaried buyers · Home loans for self-employed and business owners · NRI home loans · Balance transfer and top-up loans · Plot purchase and construction loans · Loan against property · Loan assistance for under-construction projects · Documentation and sanction follow-up
Priority campaigns
Campaigns for what home loan consultants most want to sell.
Each one planned around when your buyers decide, and measured against the baseline.
Self-employed borrower search campaign
Search ads and a landing page for business owners and freelancers asking about home loans with irregular income, with a plain list of papers.
Builder booking-day campaign
A routine with builders' sales teams to introduce you at the booking stage, with an indicative pre-check, not a sanction, of the buyer's loan eligibility.
NRI home loan guide
A written guide and a WhatsApp route for Indians abroad who plan to buy, covering papers, time zones and power of attorney.
Balance transfer reminder round
A message to past borrowers who agreed to be contacted and took a loan a year or two ago, asking whether they have checked their current terms.
Salaried employee drives
Talks and WhatsApp material for HR teams of companies in nearby IT parks, for employees thinking about a first home.
Beyond search
Where we reach buyers of home loan consultants, beyond Google.
Search matters, but it is rarely the only way this industry's buyers find a supplier.
Builders' sales heads
Each builder in your area is listed against the person who decides on loan tie-ups, and receives the tie-up pack addressed to that person.
Brokers and channel partners
A broker with a buyer ready to book needs the loan side settled, so the introduction shows how you read a profile and which papers you ask for first.
HR teams and company clubs
Young staff in IT parks and factory townships are first-home buyers. An HR desk gets a talk outline and a one-page paper list written for them.
CAs and tax advisers
Self-employed clients need help showing income for a loan, and their CAs are the first to be asked. The note to them says what papers you will ask for.
Society and apartment WhatsApp groups
Residents of apartments a few years old are the ones weighing balance transfer or a top-up for renovation. Posts go only into groups whose admins allow them.
Who it is for
This is written for these home loan consultants.
- Direct selling agents attached to several banks and housing finance companies
- Home loan consultants tied to a builder or a large broker
- Specialists in self-employed and low-ITR borrower profiles
- NRI home loan consultants working across time zones
- Balance transfer and top-up loan specialists
- Plot loan and construction loan consultants
- Loan against property consultants who also handle home loans
- Fintech-style loan marketplaces and small online loan advisers
Not for
It is not the right fit if.
- You want a guaranteed Google ranking or a guaranteed number of leads. Nobody honest can promise either.
- You need enquiries by next week and have nobody to answer them.
- You want posts and reach reported, not enquiries and orders.
How it works
How the work runs for home loan consultants
The work itself, in order. How an engagement starts, from your brief to a written scope, is set out on our method page.
- 1
Read what you place
Which lenders you hold codes with, which borrower profiles you place best, and which builders and brokers already send files: all of it is written down first.
- 2
Record the file flow
A simple sheet gives each enquiry a source, then a row for papers received, file submitted and lender decision, so a stalled borrower shows up as a gap.
- 3
Write profile pages and the tie-up pack
The pages and the builder pack are drafted, then every statement is confirmed against your lender agreements before it goes up.
- 4
Open the builder and broker routes
Outreach to sales heads and brokers begins, and so does search work aimed at self-employed and NRI borrowers.
- 5
Chase the files that stall
The sheet shows whether borrowers drop off before sending the salary slips, the bank statements or the property papers, and the reminder wording is rewritten for that gap.
Where this fits
Three pieces of sales work, in this order.
GullySales builds every engagement from three pieces of sales work. This page is not one of them, but the same three steps apply to the business behind it.
Step 1
Sales audit
Find where deals are being lost and what to fix first.
Start here if you cannot say where orders are lost.
Step 2
Sales process design
One written way to sell, from first enquiry to repeat order.
Start here if every salesperson sells differently.
Step 3
Sales management
A target, a review routine and someone who owns the number.
Start here if the team has targets and no routine.
FAQ
Questions home loan consultants ask before they call.
Not here? More answers, or ask on WhatsApp.
Should we name our lender partners on the site?
How do you treat borrower documents on the site?
Is it worth advertising for home loans?
Do you arrange loans yourselves?
How much does it cost?
How long is the contract?
How soon will we see results?
Who will actually do the work?
What do you need from us?
What if we are not happy with the work?
Part of Real estate and construction. See the other industries in the sector.
Your next practical step
Tell us what you are trying to grow, and we will read it before we call.
Eight short steps, mostly taps. Skip anything you would rather answer on the call.