Microfinance companies · Digital marketing
Use digital where it works for a lender: trust, hiring and the urban borrower.
Digital marketing for a microfinance company is the set of online tasks that support the field: the website, Maps listings, messages, hiring and some paid search. GullySales chooses the few that matter for your districts and leaves group formation to the officer.
Scope, fee, reporting and term are agreed in writing after we have read your brief and spoken to you.
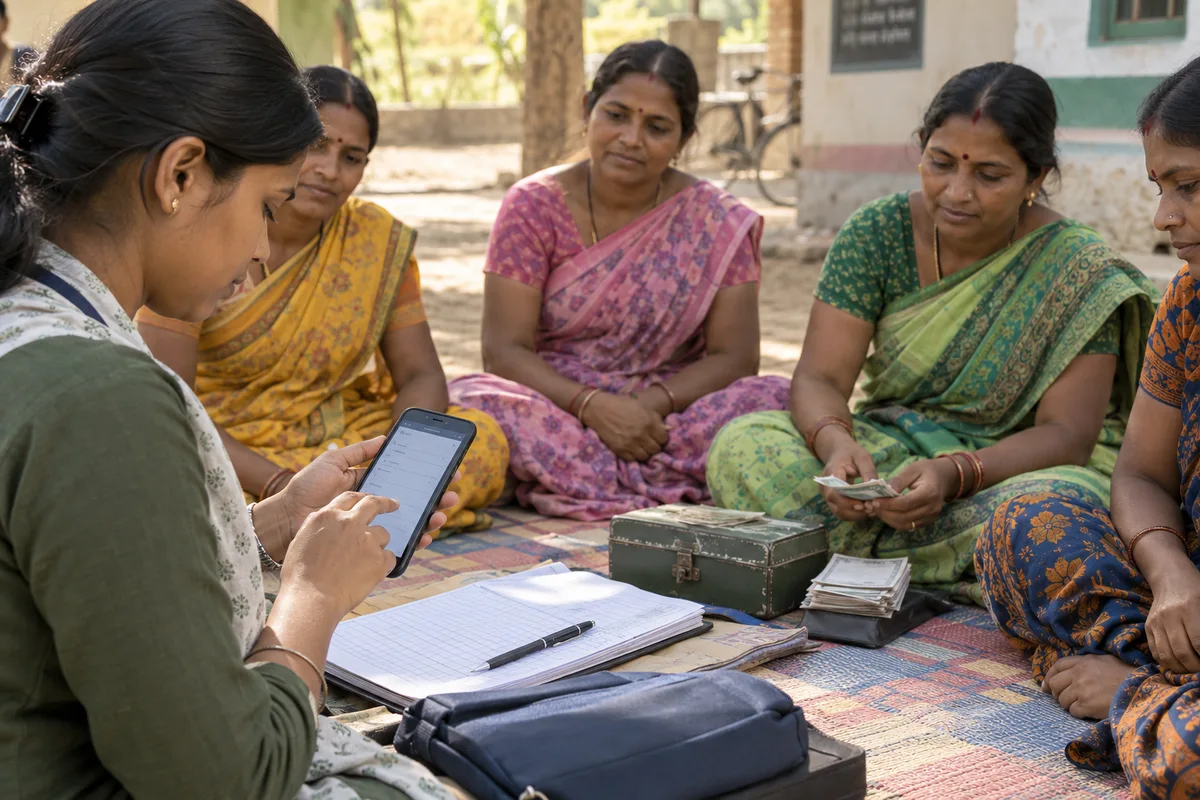
What digital marketing means
Digital marketing is the combined work of search, social media, advertising and website channels running together rather than as separate projects with separate people. GullySales runs these as one connected system so a change in one channel, such as a new offer, is reflected everywhere at once.
Also for microfinance companies
- Buyer personas for microfinance companies
- Lead generation for microfinance companies
- SEO for microfinance companies
- Local SEO for microfinance companies
- Social media marketing for microfinance companies
- Content marketing for microfinance companies
- CRM for microfinance companies
- Follow-up systems for microfinance companies
Sales and marketing for microfinance companies, the overview.
Last updated 18 Oct 2026. Rules for this trade differ by state and professional body, and they change. We describe restrictions in general terms, so check the current position with your own council or adviser before you publish anything.
For microfinance companies
Where it usually goes wrong, and what we would do.
“Digital supports the visit, it does not replace it”
A group still forms when a person walks to the village. Online work earns its place by making the company easy to verify and by reaching recruits and urban borrowers the officer never meets.
“Hiring is the clearest digital win”
Field officer vacancies hold back branch growth. Job searches, social posts and a good careers page reach candidates directly, and the cost is easier to compare than the cost of a village campaign.
“Paid advertising for credit is tightly watched”
Platforms and regulators apply rules to financial advertising, and over-borrowing is a public concern. Spend belongs only where your compliance head has cleared the wording and the audience.
What we do
What we deliver for microfinance companies.
Every deliverable, what it covers for you, and the result it is there to produce. Nothing here is an extra.
Digital audit
A review of your site, listings, social profiles and search appearance, with a short list of fixes.
Result: You see where the company is correct or missing online.
Channel choice by district
A decision on which online channels suit each district, based on your officers' knowledge of phone use.
Result: Effort goes where borrowers and recruits actually are.
Hiring campaign set-up
Careers pages, job posts and a record of applicants by source.
Result: The cost of filling a vacancy can be compared by channel.
Urban individual-loan pages
Search and landing pages for shopkeepers and home-based workers, if you offer individual loans.
Result: An urban buyer finds a clear, honest page.
Field and online reading
A simple report combining the field record with online numbers.
Result: One page shows groups formed beside online activity.
How the result is measured
- Enquiries across channels
- Cost per enquiry overall
- Channel mix by contribution
Recorded as a baseline before work starts, so every later report has an honest comparison.
Who it is for
This is written for these microfinance companies.
- NBFC-MFIs working through joint liability groups
- Self-help group linkage lenders
- Microfinance companies in rural Karnataka and neighbouring states
- Urban microfinance for small shopkeepers and home-based workers
- Small finance bank microfinance arms
- Microfinance companies adding individual business loans
- Women's livelihood and dairy-linked lenders
- Company branches opening in a new taluk
How it works
How the digital marketing work runs
The work itself, in order. How an engagement starts, from your brief to a written scope, is set out on our method page.
- 1
Understand the objective
We agree the one thing this campaign needs to achieve before choosing any channel.
- 2
Audit available channels
We assess which channels are realistic to run well within the budget and timeline.
- 3
Strategise the central idea
One message and offer is developed that will work across every planned channel.
- 4
Implement across channels
Each channel receives its own adapted version, launched on a shared timeline.
- 5
Measure as one campaign
Results from every channel are combined into a single report against the original objective.
Where this fits
Three pieces of sales work, in this order.
This work sits inside sales process design, at stage 0, foundation. The audit comes before it, and sales management keeps it running.
Step 1
Sales audit
Find where deals are being lost and what to fix first.
Start here if you cannot say where orders are lost.
Step 2 · you are here
Sales process design
One written way to sell, from first enquiry to repeat order.
Start here if every salesperson sells differently.
Step 3
Sales management
A target, a review routine and someone who owns the number.
Start here if the team has targets and no routine.
FAQ
Questions owners ask before they call.
Not here? More answers, or ask on WhatsApp.
What budget does a microfinance company need?
Can we measure online results for villages?
Is digital marketing allowed for lenders?
How long is the contract?
Who will actually do the work?
What do you need from us?
What if we are not happy with the work?
More for microfinance companies
Everything else we would do for you.
Closest to this: strategy and research
Also for microfinance companies
Or start from the overview: sales and marketing for microfinance companies.
Your next practical step
Tell us what you are trying to grow, and we will read it before we call.
Eight short steps, mostly taps. Skip anything you would rather answer on the call.