Microfinance companies · Financial services
Reach the women's groups in your villages before the next lender's officer does.
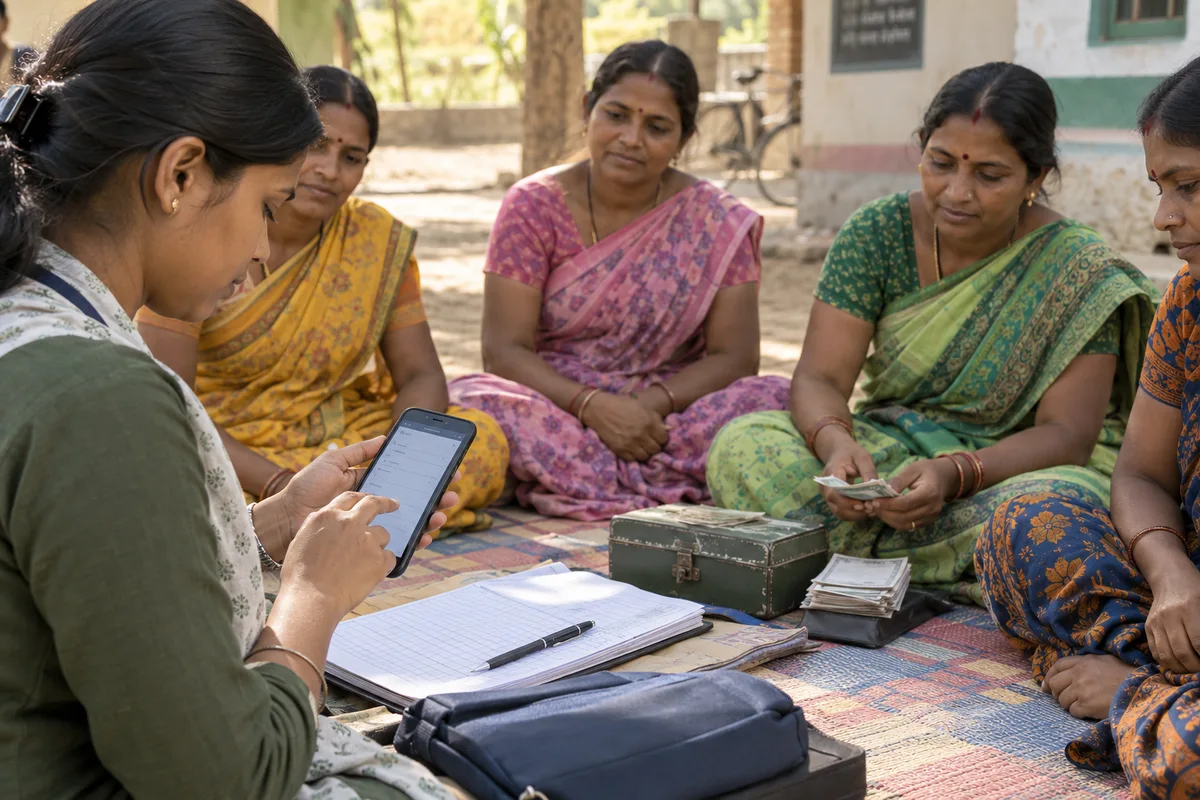
A field officer walks to a village on market day, meets a self-help group of twelve women, and explains the loan. Two ask good questions. One says another company came last week with a lower instalment. The officer notes this in a diary that the head office does not read.
Scope, fee, reporting and term are agreed in writing after we have read your brief and spoken to you.
In one paragraph
A microfinance company lends small amounts, mainly to women running tiny businesses, through groups and field officers. Its marketing is mostly presence: being known in a village and trusted by its leaders. Its sales work is the field officer's visit, the group meeting and the repeat loan. GullySales organises both and records the field.
Growth in a village is local and slow, made of group leaders, village heads and word of mouth. Digital work cannot replace it. What it can do is make the officer's visit easier, show the company at the places people already look, and keep a record that does not sit in a diary.
Last updated 18 Oct 2026. Rules for this trade differ by state and professional body, and they change. We describe restrictions in general terms, so check the current position with your own council or adviser before you publish anything.
How buyers decide
How microfinance companies are chosen.
A woman borrower chooses on trust and simplicity. The questions go to the group leader, a neighbour, or the shop owner whose business is funded by the same company: the instalment, the meeting day, who comes to collect, and whether the company treats borrowers fairly if a month goes badly. Product names and rates matter less than who the officer is.
Group leaders and village influencers carry the decision. A leader who has had a good experience brings a new group. One who has had an unkind collection visit tells the whole village.
The sector is regulated in detail, including how loans are priced, disclosed and collected, and the rules change. Check each claim and each message with your compliance head, and use a borrower’s name, photograph or loan story only with written consent.
The problem
What usually goes wrong for microfinance companies.
What owners tell us on the first call, in their words.
“Officers carry the brand alone”
In a village, the company is the officer who visits. If the officer leaves, the group goes with them, and nothing else says who the company is.
“Field data sits in diaries”
Groups that said they would join next month, villages that asked twice and loans that were declined are written by hand and never counted.
“Over-lending worries and a bad name”
Stories of borrowers stretched by many lenders spread quickly. A company that cannot show how it checks and treats borrowers carries the whole sector's reputation.
“Borrowers do not know the terms in their language”
The instalment, the fee and the insurance are explained verbally once. A printed or voice explanation in the local language is missing.
“Repeat loans depend on memory”
A borrower who has repaid well may qualify for a larger loan, after the company's own check of household income and existing debt. Whether anyone tells the borrower depends on the officer remembering.
“New districts start from zero”
Opening a branch in a new taluk means no group leaders know the company, and the first months are slow.
What we do
What we do for microfinance companies.
Everything included for microfinance companies.
Loan terms in the borrower's language
A one-page sheet and a short voice note in Kannada, Hindi, Tamil or Telugu, as the district needs, that states the interest rate, the instalment, the fee and the insurance in the words a borrower uses.
A field enquiry record
A simple form on the officer's phone or a paper-to-sheet routine for villages visited, groups met, leaders spoken to and the reason a group did not join.
Group leader programme
A routine for thanking and informing the leaders of good groups, within your rules on incentives.
Repeat borrower calling
A list of borrowers close to completing a loan cycle, with a message or call about the next loan, within the consent they gave.
Officer recruitment page and posters
A careers page, WhatsApp job message and college notice for field officer vacancies in each district.
Grievance information in plain view
Posters, a WhatsApp number and a page that say how a borrower can complain, as your regulator requires.
How the result is measured
- Villages visited and groups formed
- Reasons a group did not join
- Repeat loans from completed cycles
- Individual business loans from graduating borrowers
- Officer vacancies filled and time to fill
- Grievances logged and how they were closed
Recorded as a baseline before work starts, so every later report has an honest comparison.
Every service, written for microfinance companies
Each has its own page: what it involves for microfinance companies, what you get, and what it is measured on.
- Lead generationFind the women's groups and village leaders who are ready to borrow.
- SEOBe the page a borrower, a regulator or a recruit finds when they search your name.
- Local SEOMake every branch easy to find for the borrower who searches near the village.
- Social media marketingUse social media to show who the company is, in the languages the borrowers speak.
- Content marketingPublish the explanations a borrower's family reads before signing anything.
- Buyer personasWrite down who decides: the borrower, the household, the leader or the group.
- CRMMove groups, villages and officer promises out of diaries and into one shared record.
- Follow-up systemsMake sure a household that said maybe hears from the company again.
- WhatsApp marketingUse WhatsApp for what a village family actually reads: short voice and picture notes.
- Digital marketingUse digital where it works for a lender: trust, hiring and the urban borrower.
- WebsiteBuild a website that a borrower's family, a regulator and a recruit can all trust.
Worth a page and a campaign of their own
Group formation in new villages · Repeat and enhanced loan campaigns to existing borrowers · Plain-language loan terms in the local language · Individual business loans for graduating borrowers · Insurance and other optional add-ons explained clearly · Field officer recruitment and employer branding · Branch visibility in a new taluk · Complaint handling and grievance information · Digital repayment adoption
Priority campaigns
Campaigns for what microfinance companies most want to sell.
Each one planned around when your buyers decide, and measured against the baseline.
New taluk entry
Meetings with village heads and local SHG federations, a poster and WhatsApp introduction in the local language, and a branch listing on Maps.
Next loan campaign
Calls and messages to borrowers within the final instalments, explaining how eligibility for the next cycle is decided, without pressing a larger loan.
Business loan for graduating borrowers
A short campaign for women who have run a shop or a tailoring unit well, explaining the individual loan.
Field officer hiring drive
A job notice in local colleges and WhatsApp groups, a clear description of the role and travel, and a quick reply to applicants.
Beyond search
Where we reach buyers of microfinance companies, beyond Google.
Search matters, but it is rarely the only way this industry's buyers find a supplier.
Group leaders and village heads
The leader of a successful group can bring a neighbouring street's women to the next meeting, and a short note to read out is easier to repeat correctly than a pitch.
Existing borrowers
A borrower who has finished two cycles can tell a new group what the weekly meeting is really like. Speaking is optional, and no name is used without written consent.
Local colleges and employment exchanges
Final-year graduates who live in the district and can travel to villages on a two-wheeler are the officers a branch needs, and the placement cell is where they are reached.
SHG federations and panchayat offices
A new lender does well to call on the panchayat office and the federation office before holding a meeting in the village, and to leave a letter of introduction there.
WhatsApp and voice messages
Used by the borrower's family in the evening, they carry the explanation when the officer cannot be there.
Who it is for
This is written for these microfinance companies.
- NBFC-MFIs working through joint liability groups
- Self-help group linkage lenders
- Microfinance companies in rural Karnataka and neighbouring states
- Urban microfinance for small shopkeepers and home-based workers
- Small finance bank microfinance arms
- Microfinance companies adding individual business loans
- Women's livelihood and dairy-linked lenders
- Company branches opening in a new taluk
Not for
It is not the right fit if.
- You want a guaranteed Google ranking or a guaranteed number of leads. Nobody honest can promise either.
- You need enquiries by next week and have nobody to answer them.
- You want posts and reach reported, not enquiries and orders.
How it works
How the work runs for microfinance companies
The work itself, in order. How an engagement starts, from your brief to a written scope, is set out on our method page.
- 1
Listen in the field
The requirements brief, then time alongside a field officer and a branch manager in one district.
- 2
Count what the diary holds
Visits, groups formed and groups lost, with the reasons given, become the baseline.
- 3
Choose the first districts and clear the words
A few districts and a few messages are chosen, and nothing is written that your compliance head has not cleared.
- 4
Build the simple tools
Language sheets, the field record, the repeat loan list and the hiring page are the first things set up.
- 5
Measure groups and repeat loans
Groups formed, repeat loans and officer vacancies filled are read against the field record taken at the start.
Where this fits
Three pieces of sales work, in this order.
GullySales builds every engagement from three pieces of sales work. This page is not one of them, but the same three steps apply to the business behind it.
Step 1
Sales audit
Find where deals are being lost and what to fix first.
Start here if you cannot say where orders are lost.
Step 2
Sales process design
One written way to sell, from first enquiry to repeat order.
Start here if every salesperson sells differently.
Step 3
Sales management
A target, a review routine and someone who owns the number.
Start here if the team has targets and no routine.
FAQ
Questions microfinance companies ask before they call.
Not here? More answers, or ask on WhatsApp.
Can digital marketing work for microfinance in villages?
Do you create content in local languages?
Can you put borrower stories on our website?
Do you deal with recovery or collections?
How do you measure results without internet use in villages?
How much does it cost?
How long is the contract?
Who will actually do the work?
What do you need from us?
What if we are not happy with the work?
Part of Financial services. See the other industries in the sector.
Your next practical step
Tell us what you are trying to grow, and we will read it before we call.
Eight short steps, mostly taps. Skip anything you would rather answer on the call.