Banks · Sales funnel
See exactly how many loan enquiries reach disbursal, and where the rest disappear.
A sales funnel for a bank tracks how many enquiries move from initial interest through documentation, approval and disbursal, revealing exactly where enquiries are lost along the way. GullySales builds this funnel from your actual data so the specific leak, not a general assumption, gets fixed.
Scope, fee, reporting and term are agreed in writing after we have read your brief and spoken to you.
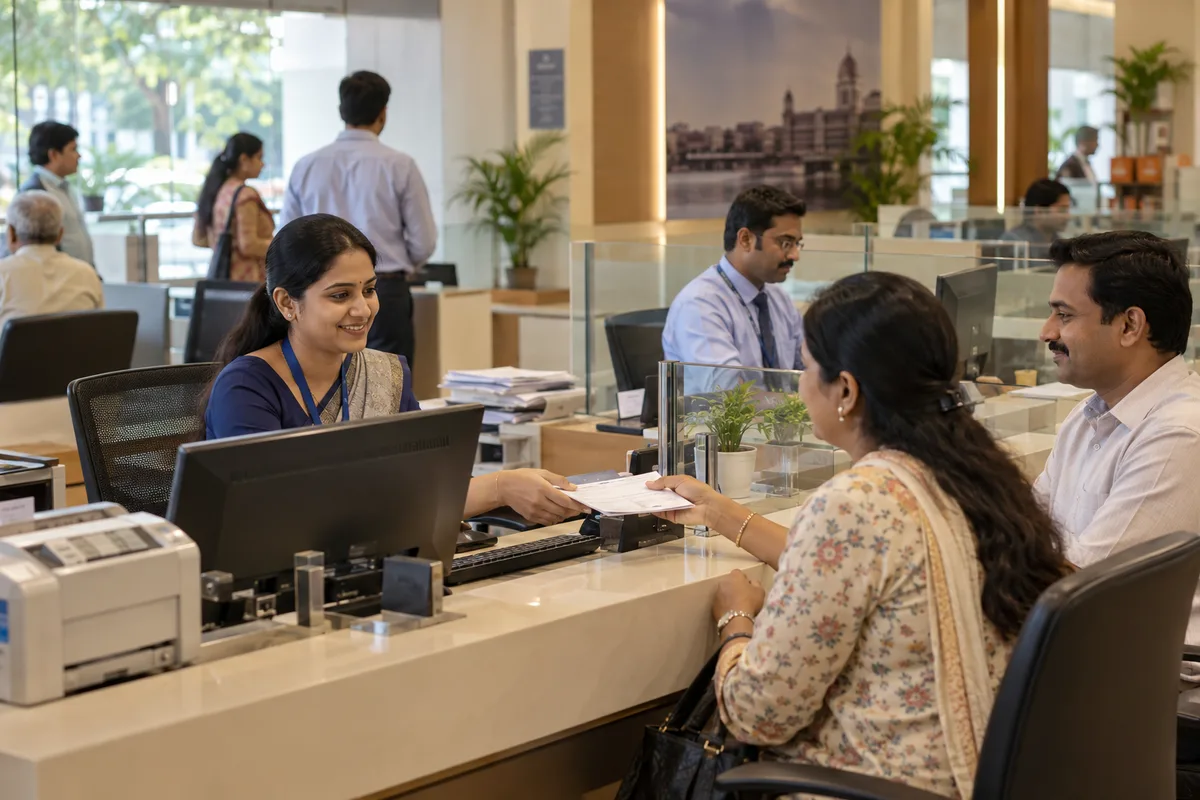
What sales funnel means
A sales funnel is the count of enquiries at each stage, from first contact through to a signed order, showing where deals are actually being lost. GullySales builds this view from your CRM data so a fall in orders can be traced to a specific stage instead of guessed at.
Last updated 5 Oct 2026. Rules for this trade differ by state and professional body, and they change. We describe restrictions in general terms, so check the current position with your own council or adviser before you publish anything.
For banks
Where it usually goes wrong, and what we would do.
“Check whether documentation is where the loan funnel leaks”
In many lending funnels, enquiries wait on incomplete documentation rather than being turned down on eligibility. Your own stage data will show whether that is true for your branch, and where follow-up effort should go.
“Different products need their own separate funnel”
A savings account funnel is short and simple, while a home loan funnel has many more stages. Combining them into one generic funnel view hides where each specific product actually struggles.
“A funnel view changes what gets fixed first”
Seeing that most loss happens between enquiry and document submission, rather than between submission and approval, changes where a branch should focus its limited follow-up effort.
What we do
What we deliver for banks.
Every deliverable, what it covers for you, and the result it is there to produce. Nothing here is an extra.
Stage-by-stage funnel from real data
A funnel showing how enquiries move through documentation, approval and disbursal, built from your actual enquiry data.
Result: You see exactly where enquiries are lost, not where you assume.
Separate funnels per product
A distinct funnel for a savings account against a home loan, since the number and nature of stages genuinely differ.
Result: Each product's real struggle shows up, instead of hiding inside a combined view.
Focus on the documentation stage
A specific look at the documentation stage, since more enquiries are typically lost there than to outright eligibility rejection.
Result: Follow-up effort concentrates where the leak is actually largest.
Ongoing funnel review
A regular check of each stage's conversion, catching a declining stage while the problem is still small.
Result: A weakening stage gets addressed before it becomes a bigger loss.
How the result is measured
- Conversion rate by stage
- Deals stuck per stage
- Overall enquiry to order rate
Recorded as a baseline before work starts, so every later report has an honest comparison.
Stages for a loan funnel
Define each loan funnel stage by what has happened and who records it.
- Enquiry logged
- A name, a number, the product and the source are written in the shared record. Whoever received the enquiry logs it, even a counter conversation that went nowhere.
- Customer contacted
- Someone has spoken to the customer, noted the purpose and amount, and agreed the next step. The relationship manager who made the call records it, with the date.
- Documents requested and documents complete
- Treat these as two stages. The first is the checklist given to the customer, the second is the point where the person checking the file confirms nothing is missing.
- Sent for credit decision
- Mark the day the file leaves the branch for the credit team or regional hub. The branch loses control of timing here, so note which desk holds it.
- Sanctioned, then disbursed
- Record the sanction and the disbursal as separate stages. A customer can walk away between them, and that loss needs its own line.
- Closed, with a reason
- Choose from a short list: not eligible, rate, withdrawn, went elsewhere, no contact. A file closed without a reason hides the very thing you are trying to learn.
Who it is for
This is written for these banks.
- Private sector bank branches
- Public sector bank branches
- Regional rural banks
- Cooperative banks
- Small finance banks
- Business correspondent networks
- NRI-focused branches
- MSME-focused branches
How it works
From your first message to the first report.
No open-ended retainer. Every step gives you something in writing.
First
Your brief
You tell us what you need in a few short steps: your business, what you want, where enquiries come from and how they are handled.
After the brief
A conversation and a written scope
We read it, then talk with whoever handles your enquiries. If you want our help, the scope, the fee and the reporting come in writing, and nothing starts before you have read them.
Before work starts
Baseline recorded
The numbers this work is meant to move, such as enquiries, quotations, orders, visits or renewals, written down so every later report has an honest comparison.
After the baseline
The first fix goes live
The fix we agreed to start with is put in place and measured against the baseline, whether that is a reply, a follow-up, a page, a listing or the handover between marketing and sales.
As agreed
Report against the baseline
What moved, what did not, and what changes next, in plain words. How often you get it is set in writing before work starts.
At renewal
Renew on the numbers
The term ends and you decide whether to continue from the results. The length is agreed in writing before anything starts.
How the sales funnel work runs
- 1
Understand the offer and buyer
We agree what the funnel needs to achieve and how considered the purchase decision typically is.
- 2
Audit the current path
We check what currently happens between a visitor arriving and either converting or leaving.
- 3
Design the funnel steps
A specific sequence of pages and offers is planned, matched to the entry source and buyer intent.
- 4
Build and implement
Each step is built, connected and tested before traffic is sent through it.
- 5
Measure and optimise
Drop-off at each step is tracked and the weakest step is improved first.
Why us
Why owners pick GullySales over an agency.
Marketing and sales, as one job
Most agencies stop at the enquiry. We also fix what happens after it: the reply, the follow-up, the quote and the CRM.
The person on the first call does the work
No account managers in between. You are never handed to someone you have not met.
A baseline before anything starts
Your numbers are written down on day one, so every later report compares against something honest.
The fee in writing, split three ways
Our time, your media spend and production on separate lines. You always see what goes to us.
No guarantees we cannot keep
The term is agreed in writing and never a default twelve months. We never promise a ranking or a lead count, because nobody controls those.
One office, and we say so
Nagarbhavi, Bengaluru. We work across India by call and WhatsApp and travel when a session needs to be in person.
#257, 3rd floor, Sri Nanjundeshwara Complex, Nagarbhavi 8th Block, Outer Ring Road. How we work.
Your brief
Tell us what you need, and we will read it before we call.
Eight short steps about your business, what you want and who decides. Most questions are a tap, and you can skip any you would rather answer on the call.
FAQ
Questions owners ask before they call.
Not here? More answers, or ask on WhatsApp.
What data do we need to build this?
How often should we review the funnel?
Who should be allowed to move a file to the next stage?
How do we count a customer who withdraws after sanction?
How much does it cost?
How long is the contract?
How soon will we see results?
Who will actually do the work?
What do you need from us?
What if we are not happy with the work?
From the blog
Further reading for banks.
 6 min read · 6 Oct 2026How buyers decide which lender or adviser to trustPeople choosing a bank, lender, insurance agent, adviser or payment company start from a name someone gave them, then check you before they call. This post sets out what they look for and where firms lose them.
 7 min read · 21 Sept 2026How to advertise to airport travellersA terminal is a small number of regular flyers counted many times, and the crowd changes completely between the six o'clock bank and the summer holidays.
More for banks
Everything else we would do for you.
Closest to this: sales craft
Also for banks
Or start from the overview: sales and marketing for banks.
Your next practical step
Tell us what you are trying to grow, and we will read it before we call.
Eight short steps, mostly taps. Skip anything you would rather answer on the call.