Microfinance companies · Digital marketing
Use digital where it works for a lender: trust, hiring and the urban borrower.
Digital marketing for a microfinance company is the set of online tasks that support the field: the website, Maps listings, messages, hiring and some paid search. GullySales chooses the few that matter for your districts and leaves group formation to the officer.
Scope, fee, reporting and term are agreed in writing after we have read your brief and spoken to you.
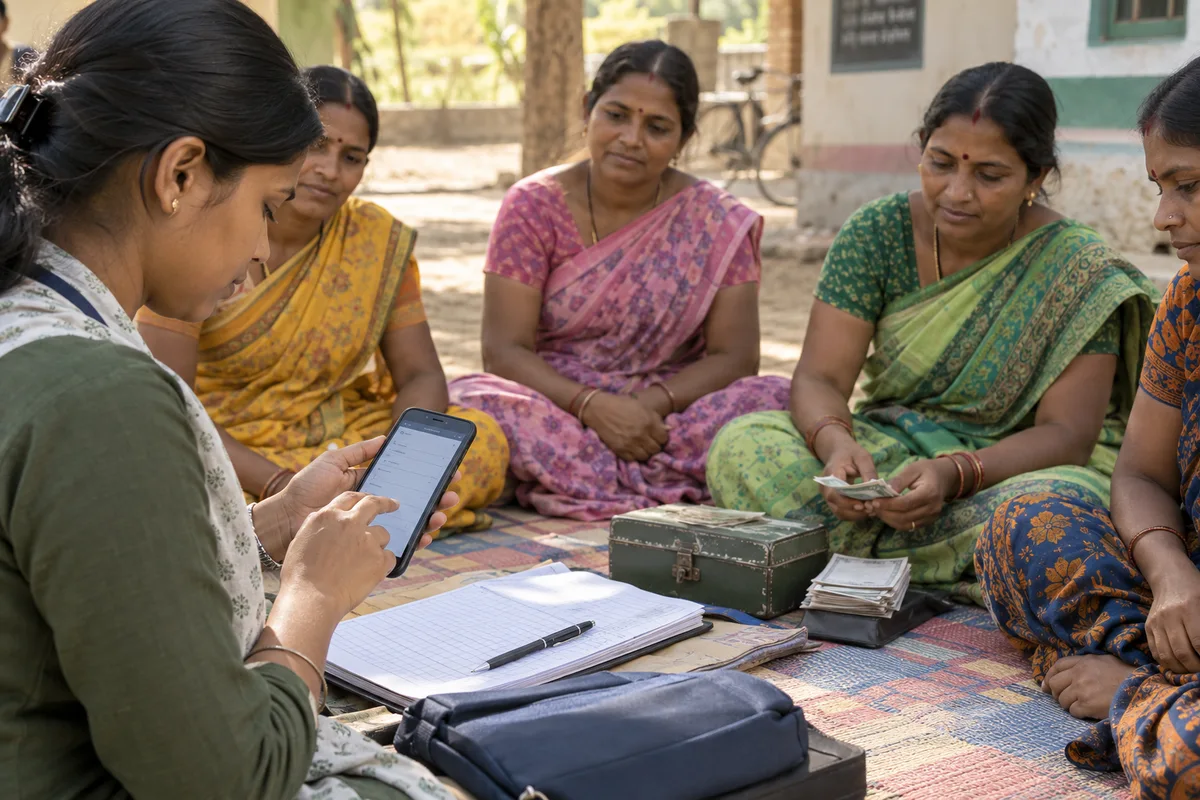
What digital marketing means
Digital marketing is the combined work of search, social media, advertising and website channels running together rather than as separate projects with separate people. GullySales runs these as one connected system so a change in one channel, such as a new offer, is reflected everywhere at once.
Also for microfinance companies
- Buyer personas for microfinance companies
- Lead generation for microfinance companies
- SEO for microfinance companies
- Local SEO for microfinance companies
- Social media marketing for microfinance companies
- Content marketing for microfinance companies
- CRM for microfinance companies
- Follow-up systems for microfinance companies
Sales and marketing for microfinance companies, the overview.
Last updated 14 Nov 2026. Rules for this trade differ by state and professional body, and they change. We describe restrictions in general terms, so check the current position with your own council or adviser before you publish anything.
For microfinance companies
Where it usually goes wrong, and what we would do.
“Online work backs up the village visit and does not stand in for it”
A group still forms when a person walks to the village. Online work earns its place by making the company easy to verify and by reaching recruits and urban borrowers the officer never meets.
“Hiring is the clearest digital win”
Field officer vacancies hold back branch growth. Job searches, social posts and a good careers page reach candidates directly, and the cost is easier to compare than the cost of a village campaign.
“Paid advertising for credit is tightly watched”
Platforms and regulators apply rules to financial advertising, and over-borrowing is a public concern. Spend belongs only where your compliance head has cleared the wording and the audience.
What we do
What we deliver for microfinance companies.
The work available for this need. We agree the deliverables and responsibilities for your engagement in writing.
Digital audit
A review of your site, listings, social profiles and search appearance, with a short list of fixes.
Result: You see where the company is correct or missing online.
Channel choice by district
A decision on which online channels suit each district, based on your officers' knowledge of phone use.
Result: Effort goes where borrowers and recruits actually are.
Hiring campaign set-up
Careers pages, job posts and a record of applicants by source.
Result: The cost of filling a vacancy can be compared by channel.
Urban individual-loan pages
Search and landing pages for shopkeepers and home-based workers, if you offer individual loans.
Result: An urban buyer finds a clear, honest page.
Field and online reading
A simple report combining the field record with online numbers.
Result: One page shows groups formed beside online activity.
How the result is measured
- Enquiries across channels
- Cost per enquiry overall
- Channel mix by contribution
Recorded as a baseline before work starts, so every later report has an honest comparison.
Searches your buyers type
Online searches that lead to a visit, a hire or a branch.
- microfinance job for women in Hassan
- The hiring campaign page. It names the district, the role and the languages, and links to a simple application the branch manager reads.
- [company name] loan for small shop
- An urban individual-loan page with the documents the shopkeeper brings and the branch to visit, in place of any approval claim.
- [company name] branch near me
- The listing and branch page, which are what a paid or free search lands on when a family is verifying the lender.
- [company name] complaint
- The grievance page, found in a few clicks from the home page. It shows that the company has a route for problems.
- how do group loans work
- An explainer in plain words and the district language. It is read by a leader or a daughter on a phone before the officer arrives.
Who it is for
This is written for these microfinance companies.
- NBFC-MFIs working through joint liability groups
- Self-help group linkage lenders
- Microfinance companies in rural Karnataka and neighbouring states
- Urban microfinance for small shopkeepers and home-based workers
- Small finance bank microfinance arms
- Microfinance companies adding individual business loans
- Women's livelihood and dairy-linked lenders
- Company branches opening in a new taluk
Before you decide
When this may not be the right fit.
- Your officers have not yet agreed a way to record where each enquiry came from, so online effort could not be told apart from the field's.
- You are opening in a district where the borrowers have no smartphone, and the officer's visit is the only way the group will hear of you.
- Compliance has not cleared any wording for financial advertising, so a paid campaign would have nothing it may say.
Before you decide
Agree the work. Know how to judge it.
Digital marketing for microfinance companies: use these checks to prepare, choose the scope, and review what changes.
Bring the right evidence
Bring a recent won order and an enquiry that went nowhere. Trace how each buyer found you, what they asked, and who handled the next step. A channel list alone will not explain the difference.
Make the scope clear
Choose one offer and one buyer group first. Agree which part needs attention: being found, getting a useful enquiry, or turning an enquiry into an order. Separate recommendations from the work required to carry them out.
Check the work in use
A useful plan names the first change, its owner, the evidence behind it, and the number that will show whether it worked. Ask what has deliberately been left out and why.
Know when to change course
If your team cannot answer the enquiries it already receives, improve that handover before buying more traffic. If the offer itself is unclear, test it with buyers before adding channels.
These are discussion points, not a fixed package. GullySales confirms the deliverables, responsibilities, fee, and term in writing after reading your brief and speaking with you.
Before we start
What to have ready before the work starts.
The records, access and decisions this work needs from microfinance companies. Anything missing is noted in the written scope, with who will supply it.
- The list of branches that need officers
- Hiring is the clearest online task. Tell us which branches are short, which roles and which languages. Without it, the hiring work waits, and we begin with the audit and the Maps listings.
- Access to every online account you hold
- List the website, the Maps profiles, the social pages and any advertising account, with the administrator for each. If an agency or an ex-employee holds one, tell us who. Unknown accounts are recorded and handled last.
- Your compliance head's view on paid advertising
- Whether the company will advertise credit at all, and under whose clearance, is your decision. We plan around it. If the answer is no, the digital plan covers hiring, search and the website only.
- The urban loan product note, if offered
- If the company has an individual loan for shopkeepers or home workers, give us the product note and the branches that offer it. The plan for the urban borrower depends on it. Without it, that part of the plan is left out.
- A single contact in the branches for results
- Each branch needs someone who will tell us how many applicants and urban enquiries came, and from where. A named person matters more than any figure. Without one, we cannot read the online work against the field, and every channel would be judged by clicks alone, which tell a lender little about groups formed or officers hired.
How it works
How the digital marketing work runs
The work itself, in order. How an engagement starts, from your brief to a written scope, is set out on our method page.
- 1
Walk the districts with the area managers
We start with a map of the districts and a conversation with each area manager about where growth is wanted: new groups, new officers or the urban individual loan. You say which districts are field-led and which have borrowers who search online. The plan is built district by district, and no district is given a channel just because it is fashionable.
- 2
Audit what the company already has online
We look at the website, the Maps listings, the social pages, the job posts and any paid search, and we note what is wrong, missing or out of date. You receive the audit as a plain list with an owner beside each line. Items outside our brief, such as the core system, are named and left to your team.
- 3
Choose three channels for each district
From the audit we pick the few channels that matter for each district: perhaps Maps and hiring posts in one, search for the urban loan in another. You approve the choice. A channel is dropped if no one in the branch can answer what it brings. Paid advertising for credit is considered last and only with your compliance head's written view.
- 4
Agree the messages with compliance first
We draft the wording for hiring, for the urban individual loan and for the explanation of the group loan, in the languages needed. Your compliance head clears each one before any production begins. The platform rules for financial advertising change, so we ask you to check the platform's current rules with your adviser before anything runs.
- 5
Set up the hiring campaign for short branches
With the branch manager we list the villages from which officers can reasonably travel, and write the job post and the page it points to. Applicants are sent to a named person at head office. You decide the entry requirements. The campaign runs only for branches that have said they need officers.
- 6
Read the field and the online side together
We sit with the area managers and set what the branches recorded, such as groups formed, applicants and urban enquiries, beside what the online channels logged. Each is compared with the starting note. Which channels carry on and which stop is your decision. We report what the figures show and promise no borrowers.
Where this fits
Three pieces of sales work, in this order.
This work sits inside sales process design, at stage 0, foundation. The audit comes before it, and sales management keeps it running.
Step 1
Sales audit
Find where deals are being lost and what to fix first.
Start here if you cannot say where orders are lost.
Step 2 · you are here
Sales process design
One written way to sell, from first enquiry to repeat order.
Start here if every salesperson sells differently.
Step 3
Sales management
A target, a review routine and someone who owns the number.
Start here if the team has targets and no routine.
FAQ
Questions owners ask before they call.
Not here? More answers, or ask on WhatsApp.
What budget does a microfinance company need?
Can we measure online results for villages?
Is digital marketing allowed for lenders?
Which part of digital should a microfinance company do first?
Is it better to spend on digital or on more field officers?
Who holds the accounts and the data once the work ends?
How long is the contract?
Who will actually do the work?
What do you need from us?
What if we are not happy with the work?
More for microfinance companies
Related work to consider.
Closest to this: strategy and research
Also for microfinance companies
Or start from the overview: sales and marketing for microfinance companies.
Your next practical step
Tell us what you are trying to grow, and we will read it before we call.
Eight short steps, mostly taps. Skip anything you would rather answer on the call.