Payment and fintech companies · Buyer persona
Write for two people: the developer who integrates and the finance head who signs.
A buyer persona for a payment or fintech company is a one-page description of the person who chooses you, written from your own signups and sales calls. GullySales builds a card for the merchant owner, the developer and the finance head, checks each against real conversations, and uses them for pages, ads and sales scripts.
Scope, fee, reporting and term are agreed in writing after we have read your brief and spoken to you.
What buyer persona means
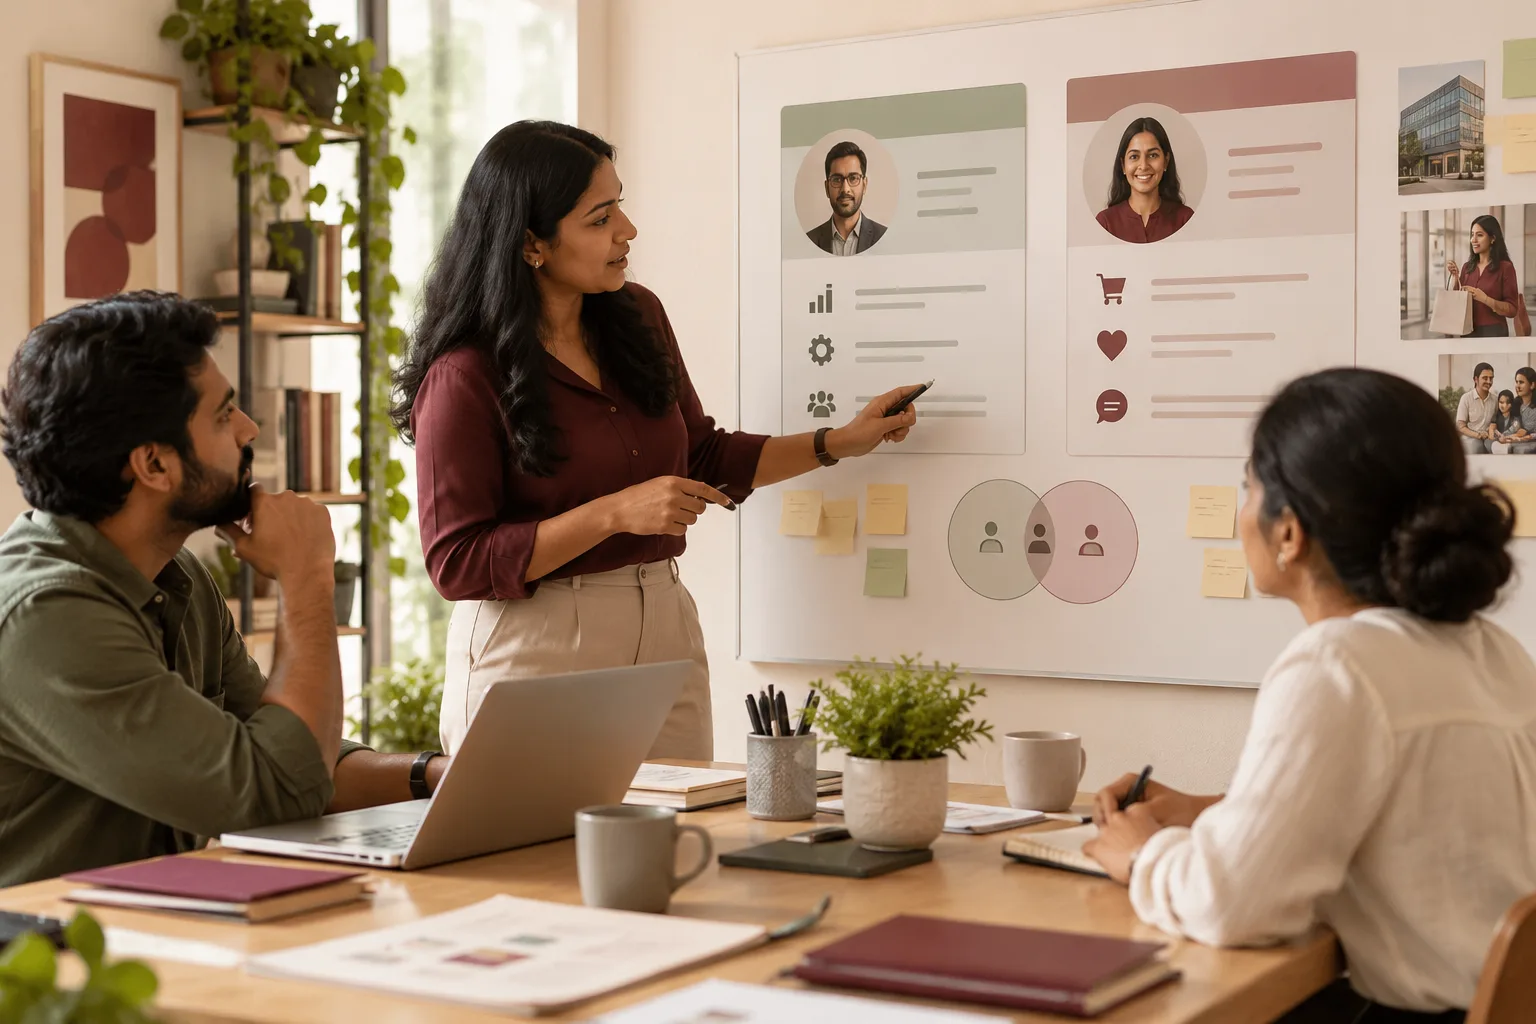
A buyer persona is a plain description of the kind of customer who actually buys from you. It includes what they search, what worries them and who else they ask before deciding. GullySales builds this from real enquiries and past sales rather than a generic template, then uses it to write every page and advert.
Also for payment and fintech companies
- SEO for payment and fintech companies
- Content marketing for payment and fintech companies
- Lead generation for payment and fintech companies
- PPC ads for payment and fintech companies
- Email marketing for payment and fintech companies
- Sales process for payment and fintech companies
- Website development for payment and fintech companies
- Reputation management for payment and fintech companies
Sales and marketing for payment and fintech companies, the overview.
Last updated 6 Oct 2026. Rules for this trade differ by state and professional body, and they change. We describe restrictions in general terms, so check the current position with your own council or adviser before you publish anything.
For payment and fintech companies
Where it usually goes wrong, and what we would do.
“The signer and the integrator are different people”
A page written for the owner ignores the developer who will try the sandbox, and a docs-only site ignores the finance head who must approve the fee.
“Small sellers and enterprises share one card”
A seller on Instagram with a UPI QR and a company with a procurement team want different things, and one SMB merchant card describes neither.
“Template personas read like every other company's”
A card saying tech-savvy and values security fits every payment company. A card that names the platform, the paper that stalls and the worry about holds is yours.
What we do
What we deliver for payment and fintech companies.
Every deliverable, what it covers for you, and the result it is there to produce. Nothing here is an extra.
Three persona cards
Merchant owner, developer and finance head, one page each, built from your own signup data, sales call notes and support tickets.
Result: Each page and ad is written to someone specific.
A check against real merchants
A call plan for speaking to merchants who went live and those who dropped out, with the questions to ask and what to record.
Result: The cards change where real answers differ.
Messages by persona
For each card, the first line on the homepage, the ad headline and the opening on a sales call, each in that person's words.
Result: The developer and the owner stop reading the same sentence.
A landing route for each persona
Documentation for the developer, rate and settlement pages for the finance head, a one-page start guide for the owner.
Result: Each person lands where their question is answered.
A persona sheet for sales and support
One sheet for sales and support staff saying what each person asks and what they should be sent.
Result: Staff reply the same way to the same worry.
How the result is measured
- Enquiry match to persona
- Conversion rate by persona
- Content aligned to persona
Recorded as a baseline before work starts, so every later report has an honest comparison.
A persona card for this buyer
A typical card for a small online seller choosing a payment gateway, to be checked against your own merchants.
- Who they are
- Typical: the owner of a home-textile or skincare brand selling through its own site and Instagram, with one freelance developer. Check against the merchants you onboarded last quarter.
- What starts the search
- Typical: a held settlement, a failed checkout during a sale, or a plan to add UPI. Ask your merchants what happened in the week they began looking.
- What worries them
- Typical: money held for review, a plugin that breaks the store, and fees that change after signup. Check these against support tickets from new merchants.
- What they compare you with
- Typical: two or three other gateways and the payment service their bank offers. Ask which they opened, and note what each page showed them.
- Who else decides
- Typical: the developer who tests the plugin, the CA who books the fees, and sometimes a co-founder. Find out who actually asked for the documents.
- What makes them say yes
- Typical: a working plugin on a test order, a clear page on holds and refunds, and a reply from a person when they got stuck. Confirm with merchants who stayed.
Who it is for
This is written for these payment and fintech companies.
- Payment gateways and aggregators for online sellers
- UPI and QR providers with soundboxes and card machines for shops
- Prepaid wallet and card issuers working with a partner bank
- Digital lenders and buy-now-pay-later apps working with a bank or NBFC
- B2B payment, vendor payout and payables platforms
- Payroll, expense and corporate card tools for companies
- Cross-border payment and remittance platforms
- Neobanks and current account apps for startups and small businesses
How it works
From your first message to the first report.
No open-ended retainer. Every step gives you something in writing.
First
Your brief
You tell us what you need in a few short steps: your business, what you want, where enquiries come from and how they are handled.
After the brief
A conversation and a written scope
We read it, then talk with whoever handles your enquiries. If you want our help, the scope, the fee and the reporting come in writing, and nothing starts before you have read them.
Before work starts
Baseline recorded
The numbers this work is meant to move, such as enquiries, quotations, orders, visits or renewals, written down so every later report has an honest comparison.
After the baseline
The first fix goes live
The fix we agreed to start with is put in place and measured against the baseline, whether that is a reply, a follow-up, a page, a listing or the handover between marketing and sales.
As agreed
Report against the baseline
What moved, what did not, and what changes next, in plain words. How often you get it is set in writing before work starts.
At renewal
Renew on the numbers
The term ends and you decide whether to continue from the results. The length is agreed in writing before anything starts.
How the buyer persona work runs
- 1
Understand the current view
We start with how your team currently describes the customer, since the gap between belief and reality is often the finding itself.
- 2
Audit past enquiries and sales
We look at recent enquiries and closed deals to see who actually bought, not who was assumed to buy.
- 3
Interview customers and staff
Short, structured conversations surface the real language, worries and triggers behind a purchase.
- 4
Build the personas
Findings are written into short, usable persona documents rather than a long report.
- 5
Apply to your marketing
We show exactly where each persona should change a page, an ad or a script you already have.
Why us
Why owners pick GullySales over an agency.
Marketing and sales, as one job
Most agencies stop at the enquiry. We also fix what happens after it: the reply, the follow-up, the quote and the CRM.
The person on the first call does the work
No account managers in between. You are never handed to someone you have not met.
A baseline before anything starts
Your numbers are written down on day one, so every later report compares against something honest.
The fee in writing, split three ways
Our time, your media spend and production on separate lines. You always see what goes to us.
No guarantees we cannot keep
The term is agreed in writing and never a default twelve months. We never promise a ranking or a lead count, because nobody controls those.
One office, and we say so
Nagarbhavi, Bengaluru. We work across India by call and WhatsApp and travel when a session needs to be in person.
#257, 3rd floor, Sri Nanjundeshwara Complex, Nagarbhavi 8th Block, Outer Ring Road. How we work.
Your brief
Tell us what you need, and we will read it before we call.
Eight short steps about your business, what you want and who decides. Most questions are a tap, and you can skip any you would rather answer on the call.
FAQ
Questions owners ask before they call.
Not here? More answers, or ask on WhatsApp.
How many personas do we need?
How do we test a persona card on merchants we already have?
Can the same persona be used for ads and for staff training?
We sell to businesses and to consumers. Do we need separate sets?
How much does it cost?
How long is the contract?
How soon will we see results?
Who will actually do the work?
What do you need from us?
What if we are not happy with the work?
From the blog
Further reading for payment and fintech companies.
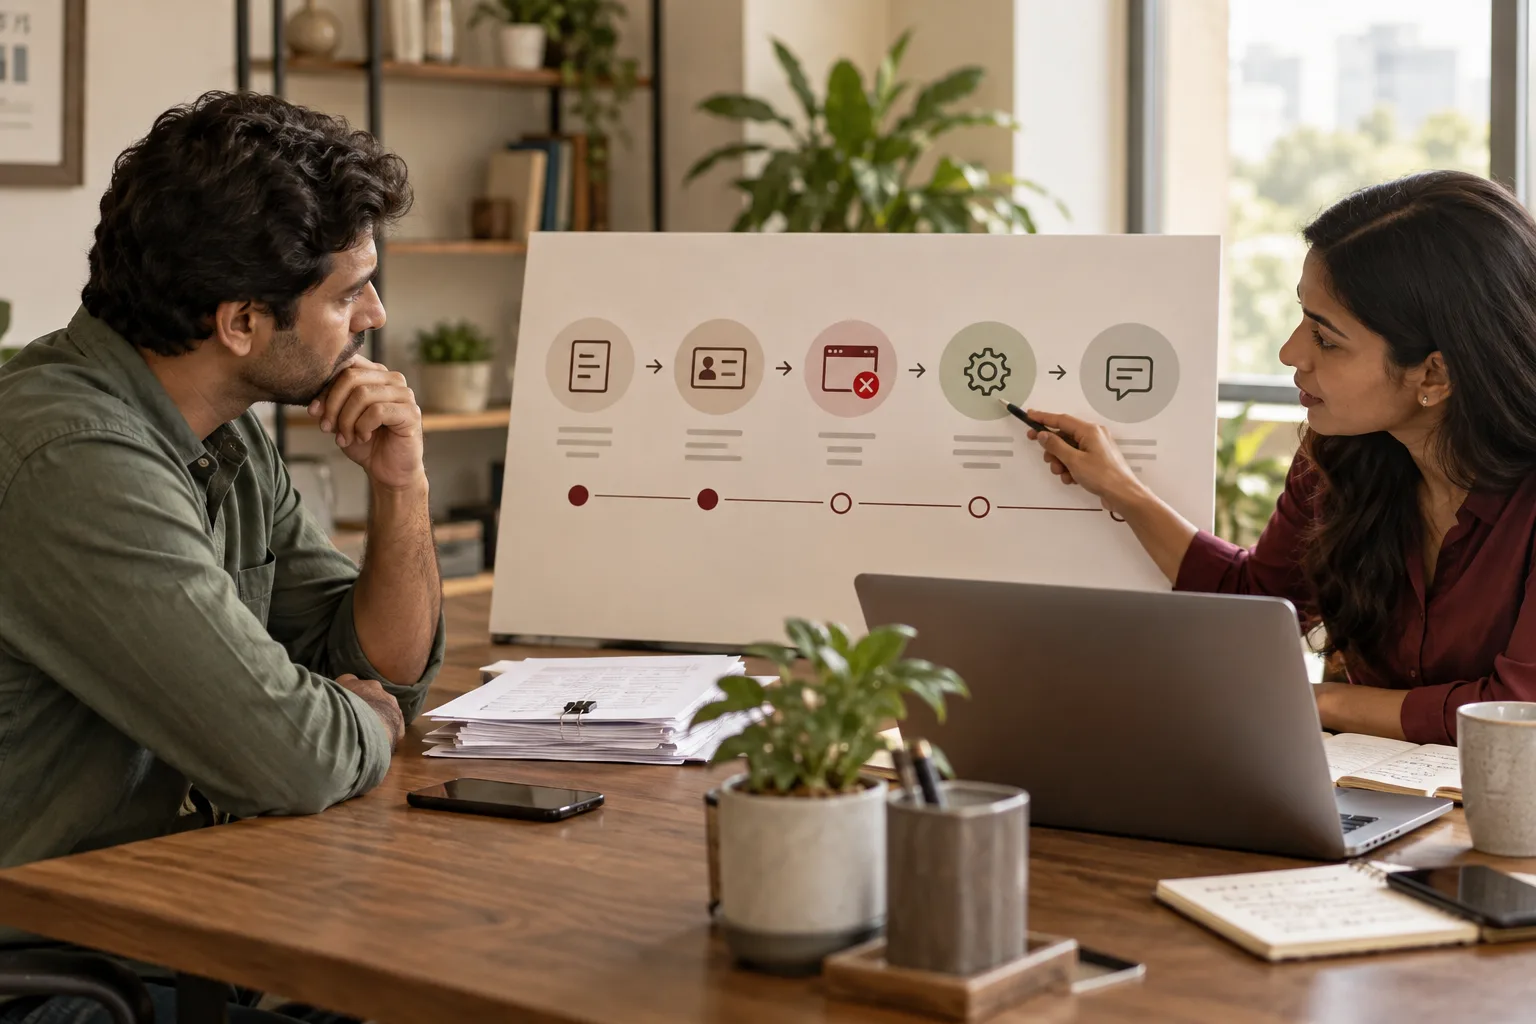 5 min read · 6 Oct 2026Why signed-up merchants never take a live paymentMerchants stall between signup and the first live payment at a few known points: KYC paperwork, a site that fails review, the integration, and silence. How to find which one and clear it.
 6 min read · 6 Oct 2026How buyers decide which lender or adviser to trustPeople choosing a bank, lender, insurance agent, adviser or payment company start from a name someone gave them, then check you before they call. This post sets out what they look for and where firms lose them.
More for payment and fintech companies
Everything else we would do for you.
Or start from the overview: sales and marketing for payment and fintech companies.
Your next practical step
Tell us what you are trying to grow, and we will read it before we call.
Eight short steps, mostly taps. Skip anything you would rather answer on the call.